Category: CRE Market Analytics & Data

  • Deal Ground Review: Find CRE properties, owners and reasons to call

    Deal Ground Review: Find CRE properties, owners and reasons to call

    BestCRE 9AI Score

    78/100 · Contender

    Deal Ground ranks #117 of 404 commercial real estate AI tools scored on the 9AI Framework. Nine dimensions, each scored out of 10: CRE relevance, data quality, ease of adoption, output accuracy, integration fit, pricing transparency, support, innovation and market reputation.

    DealGround is a CRE native data and prospecting platform for brokers, investors and acquisitions teams. It changes the work between defining a target market and contacting an owner. Instead of searching property databases, state records, offering memorandums and separate contact services, a user can identify matching assets, review property context, investigate the ownership entity and find potential decision makers within one workflow. The product is especially relevant to professionals whose pipelines depend on direct owner outreach rather than marketed listings alone.

    The platform combines searchable property records with tenant, lease, transaction, debt and financial information. It also extracts information from brochures, offering memorandums and rent rolls, turning documents into structured records that can be searched and mapped. Users can filter properties by criteria such as location, asset class, tenant, ownership, lease term, prior marketing activity and last sale. That makes DealGround more than a contact lookup service: its intended value is helping users determine why a particular owner may be worth calling now.

    Owner research is the product’s central commercial proposition. DealGround traces an ownership entity toward a principal, supplies available phone and email information, summarizes its research and displays related holdings. Lists can then be ranked using property and lease variables, researched in bulk, shared with a team and exported. BestCRE analysis: the unified view is useful because ownership identity without asset context produces weak outreach, while property data without a reachable decision maker often leaves a prospecting workflow unfinished.

    The main buying question is not whether this workflow is sensible. It is whether DealGround’s coverage, contact accuracy and document derived fields are dependable in the buyer’s exact markets. The vendor makes broad accuracy and productivity claims, but it does not publish enough methodology for an independent buyer to treat those claims as established benchmarks. A serious evaluation should therefore test a representative sample of known properties, ownership structures and contacts before committing a production team.

    What Deal Ground Does and How It Works

    A user begins with an address, geography, tenant, owner name or asset class, then applies filters aligned with an acquisition thesis or brokerage territory. Property pages bring together ownership entities, sale history, debt, tenants, lease terms, net operating income, capitalization rates and prior marketing information when those fields are available. Saved searches and lists support recurring prospecting rather than isolated lookups. Weekly alerts can notify users when relevant records or searches change, allowing a broker to revisit targets without rebuilding the query.

    DealGround also ingests brochures, offering memorandums and rent rolls. Its automation extracts property, tenant, lease and financial fields and incorporates them into a searchable database. Users can upload their own documents, which the vendor says remain private to the user and team, or work from documents already indexed by the platform. An AI chat interface can answer questions about a property or list. BestCRE analysis: this is valuable when it reduces document review time, but extracted lease dates, rent figures and financial values should remain traceable to the underlying source and reviewed before underwriting or client distribution.

    For ownership research, the system attempts to move from the recorded LLC to an individual decision maker through skip tracing and research. It returns available emails, mobile numbers, a contact summary, source links and the owner’s broader property portfolio. Research can run on individual properties or an entire list. Users can track progress inside DealGround, share work with colleagues, export records to Excel or CSV, use a Chrome extension, connect through HubSpot or access enterprise APIs. The product also advertises use from Claude or ChatGPT through supported connectivity, which may help teams query data without remaining in the primary interface.

    9AI Framework: Dimension by Dimension Analysis

    CRE Relevance: 10/10

    DealGround earns a 10 for CRE relevance because its data model and workflow are built around commercial property prospecting. Searches can use asset class, tenant, lease timing, ownership, financial and transaction criteria that matter to brokers and acquisitions teams. The system does not merely append generic contact records to addresses. It connects legal ownership, potential principals, related portfolios, marketing history and property level context in the same workspace. Document ingestion also focuses on CRE source material, including offering memorandums, brochures and rent rolls. BestCRE analysis: few product categories sit closer to the daily work of sourcing off market opportunities. The score does not imply that every record is complete or suitable for underwriting. It means the product’s purpose, terminology, inputs and outputs are directly aligned with commercial real estate.

    Data Quality and Sources: 8/10

    DealGround earns an 8 for data quality. Its useful distinction is the combination of conventional property records, document extracted information, owner research and links back to sources. Portfolio context can help users notice when a single purpose entity belongs to a larger ownership group. Brochure and rent roll ingestion can add fields that ordinary public records do not contain. However, freshness and completeness can vary across jurisdictions, document types and assets. The vendor does not publish a sufficiently detailed field by field coverage table, refresh methodology or independent audit that would let buyers generalize its accuracy claims. BestCRE analysis: source links and document provenance make errors easier to investigate, but they do not remove the need for sampling. Buyers should test recent sales, layered LLCs, outdated phone records and lease data in several representative markets.

    Ease of Adoption: 8/10

    DealGround earns an 8 for ease of adoption. The workflow follows a familiar sequence: search, filter, inspect, research ownership, save to a list and export or contact the prospect. A free plan and trial reduce the administrative burden of testing the product, while mapped results and property pages should be understandable to users accustomed to CRE databases. Bulk research can also remove repetitive visits to state registries and contact sites. Adoption becomes more involved when a firm wants shared research standards, CRM synchronization, private document controls or API based workflows. BestCRE analysis: an individual broker should be able to judge the core experience quickly, but a brokerage should still define naming, deduplication and verification rules before a wider rollout. The vendor does not publish typical implementation time, formal training requirements or enterprise onboarding benchmarks.

    Output Accuracy: 7/10

    DealGround earns a 7 for output accuracy. Its outputs combine recorded facts, extracted document fields and inferred ownership contacts, which carry different levels of certainty. A sale date tied to a public source is not equivalent to a phone number associated through skip tracing, and neither is equivalent to a lease term extracted from an offering memorandum. The product’s inclusion of source links and research summaries is therefore important because users can examine how a result was assembled. BestCRE analysis: the platform appears well designed for prioritizing outreach, but its results should not automatically become underwriting facts, legal conclusions or client facing claims. Buyers should compare a test set against known ownership, call selected numbers, inspect bounced emails and reconcile extracted financial fields with original documents. Public precision, recall and contact deliverability studies are not published.

    Integration and Workflow Fit: 7/10

    DealGround earns a 7 for integration. It offers practical paths out of the application through Excel and CSV exports, plus a Chrome extension and a HubSpot connection. Enterprise customers can obtain REST API access for property data, address matching and ownership research, with administrative usage reporting. The ability to work with DealGround data from supported AI assistants is a notable option for teams experimenting with conversational research. These capabilities cover the most common bridge from prospect discovery to spreadsheet analysis or CRM follow up. BestCRE analysis: the integration story is credible but not yet broad enough to assume a ready made connection for every brokerage stack. Public materials do not establish native support for every major CRE CRM, data warehouse or transaction system. Buyers should confirm field mappings, update direction, duplicate handling, authentication and API limits during evaluation.

    Pricing Transparency: 9/10

    DealGround earns a 9 for pricing transparency because individual users can see both a permanent free tier and clearly stated Pro subscription options before speaking with sales. The site identifies included research allowances, trial terms, exports, alerts, document automation and other feature boundaries. It also explains that additional ownership research can be purchased. Enterprise pricing remains custom, which is reasonable when team size and API usage affect cost, but procurement teams will need a quote for deployment economics. BestCRE analysis: this is substantially clearer than CRE data products that hide every price behind a demonstration request. The remaining questions concern overage pricing, enterprise minimums, renewal treatment and what constitutes a completed ownership research when results are sparse. Those terms should be documented before a team bases recurring prospecting operations on the service.

    Support and Reliability: 6/10

    DealGround earns a 6 for support. The company provides a help center, contact channels and sales assisted enterprise access, which gives buyers several routes for product guidance. Shared lists and administrative usage reporting also suggest some attention to team deployment. Yet the vendor does not publish support response targets, named service tiers, coverage hours, escalation procedures or uptime commitments for the standard plan. It also does not publish enough detail about implementation services, data correction workflows or dedicated customer success coverage. BestCRE analysis: support appears adequate for self directed prospecting, but larger firms should negotiate expectations rather than infer them from general contact availability. During diligence, buyers should submit a data correction, ask a technical integration question and test account administration. The quality and speed of those responses will be more informative than a polished demonstration.

    Innovation and Roadmap: 9/10

    DealGround earns a 9 for innovation. The strongest idea is not any single AI feature, but the assembly of a prospecting chain that usually spans several tools. Property search produces a candidate, document extraction adds operating context, ownership research identifies a likely principal, portfolio mapping explains the relationship and ranking gives the user a reason to make contact. Conversational querying and automated processing make that combined dataset easier to navigate. BestCRE analysis: the product advances beyond static parcel lookup because it treats context and contactability as parts of the same decision. That said, AI extraction and skip tracing are not inherently reliable, and competitors can reproduce individual components. The defensible advantage will depend on source breadth, entity resolution, correction loops and how consistently the system identifies actionable prospects before rivals do.

    Market Reputation: 6/10

    DealGround earns a 6 for market reputation. The company publishes testimonials from recognizable CRE professionals and organizations, indicating credible use across brokerage, investment and corporate real estate workflows. Its public positioning is specific enough that prospective customers can evaluate concrete tasks rather than an undefined AI promise. However, the vendor does not publish independently verified customer counts, retention figures, usage depth or broad third party accuracy studies. A collection of favorable customer statements is useful evidence, but it is not the same as long term category dominance. BestCRE analysis: DealGround has visible practitioner validation and a focused market identity, while its public track record remains less established than larger property data platforms. Reference calls should cover data corrections, contact success, renewal decisions and performance across more than one geography.

    9AI Score Card Deal Ground
    78
    78 / 100
    Solid Platform
    CRE Prospecting Intelligence
    Deal Ground
    DealGround combines property screening, document extraction, ownership research and portfolio context so brokers and acquisitions teams can move from a target property to outreach.
    9 Dimensions, Scored 1 to 10
    1. CRE Relevance
    10/10
    2. Data Quality & Sources
    8/10
    3. Ease of Adoption
    8/10
    4. Output Accuracy
    7/10
    5. Integration & Workflow Fit
    7/10
    6. Pricing Transparency
    9/10
    7. Support & Reliability
    6/10
    8. Innovation & Roadmap
    9/10
    9. Market Reputation
    6/10
    BestCRE.com, 9AI Framework v2 Reviewed October 2026

    Who Should Use Deal Ground

    DealGround best suits investment sales brokers, tenant focused brokers, developers and acquisitions teams that repeatedly identify off market owners. It is particularly relevant when an analyst spends meaningful time moving among property databases, offering memorandums, Secretary of State records, search engines and contact services. Retail and industrial teams can use tenant and lease timing to prioritize outreach, while multifamily buyers can screen property and transaction attributes before researching the ownership chain. Appraisers may also find document and transaction context useful, although they should verify every valuation input independently.

    The strongest buyer has a defined territory or acquisition thesis, a repeatable calling process and a CRM or spreadsheet where qualified prospects can be managed. BestCRE analysis: DealGround creates the most value when users act on the research quickly and record the result of each contact attempt. A firm should nominate an owner for list standards, deduplication and corrections. Before purchase, it should test known entities, difficult LLC structures, recent trades and several properties with internally verified lease information. A successful pilot should measure time to a usable contact, contact validity, new portfolio relationships found and the percentage of records that produce a defensible reason to call.

    Who Should Not Use Deal Ground

    DealGround is a weaker fit for teams that only pursue publicly marketed listings or already receive sufficient ownership intelligence from an established enterprise data contract. It may also be excessive for a small operator making occasional acquisitions without a systematic outbound program. Firms seeking a full transaction room, electronic signature platform, commission system or end to end CRM should not treat DealGround as a substitute. Its center of gravity is prospect discovery and owner research.

    The product should not be the sole source for underwriting, legal ownership conclusions or regulated communications. Extracted financial and lease data can inherit errors from source documents or automated interpretation, while skip traced contacts may be stale or incorrectly associated. Teams without a verification process, privacy policy or clear rules for outreach should resolve those gaps first. BestCRE analysis: if a buyer cannot identify who will use the lists, how contacts will be validated and where activity will be recorded, the platform risks becoming another searchable database rather than a revenue producing workflow.

    Pricing and ROI Analysis

    DealGround publishes a free plan with no credit card requirement. It includes limited ownership research, full records for a limited property set, uploads and the Chrome extension. Pro is listed at $99 per user per month or $999 per user when billed annually, following a 14 day trial. The annual option saves $189 against twelve monthly payments. Pro adds broader property records, document automation, AI chat, alerts, exports, shared research and defined ownership research allowances. Enterprise pricing is not published because it varies with team size and API usage. Buyers can also purchase additional research capacity, although public add on prices are not stated.

    Analysis: at the annual Pro price, a single user needs to create at least $999 in yearly value to break even before considering training or workflow costs. If the platform saves two hours each month, the implied break even labor value is about $41.63 per hour, calculated as $999 divided by twenty four hours. That is a modest threshold for many brokerage and acquisitions roles, but time saved is only valuable when it becomes more calls, better qualified targets or faster decisions. A pilot should therefore track both research hours and commercial outcomes. Enterprise buyers should request total contract cost, API limits, included research volume, overage rates, onboarding charges, renewal terms and data export rights.

    Integration and CRE Tech Stack Fit

    DealGround fits naturally between market research and a firm’s system of record. Users can build and enrich a target list, then export it to Excel or CSV for analysis, review or import elsewhere. HubSpot connectivity can support movement into a conventional sales workflow, while the Chrome extension helps users research properties during browser based work. Shared lists keep initial collaboration inside the platform. Supported access through Claude or ChatGPT may appeal to firms already using conversational interfaces for research.

    Enterprise API access is the more important option for firms that need address matching, ownership research or property information inside internal applications. BestCRE analysis: buyers should determine whether the API returns source metadata, confidence indicators and stable identifiers, not just display fields. They should also test how corrections and refreshed ownership data propagate. Public information does not establish native connections to every common CRE CRM or transaction platform, so firms using specialized systems may need exports, middleware or custom development. Security review should cover uploaded documents, team permissions, retention, API credentials and the handling of personally identifiable contact data.

    Competitive Landscape

    Reonomy, owned by Altus Group, is the clearest enterprise property intelligence alternative. It brings established property and ownership search capabilities and may fit teams that prioritize broad institutional data infrastructure. PropertyRadar also combines property information, owner data and list building, with particular appeal where parcel based prospecting is central. Compared with these products, DealGround’s distinction is the attempt to connect document extracted lease and financial context with owner research and portfolio visibility in one prospecting view.

    Terrakotta and PropTracer are closer comparisons for brokers focused on finding owners and running outbound campaigns. Buyers should compare entity resolution, phone and email validity, geographic depth, portfolio matching, list management and CRM fit on the same sample. Lev is a different kind of alternative, centered more on commercial real estate financing and capital workflows than general owner prospecting. It belongs in the evaluation only when debt placement or financing intelligence is the primary job.

    BestCRE analysis: DealGround should be shortlisted when the buyer values a reason to call as much as the contact itself. CompStak is stronger as a lease and transaction comparables reference, while ClientLook and RealNex address broader relationship or brokerage operations. No competitor comparison should rest on a scripted demonstration. Give each vendor an identical file of known assets, difficult ownership entities and outdated contacts, then score completeness, accuracy, research time and usable introductions.

    The Bottom Line

    DealGround is a credible buy for CRE teams whose growth depends on systematic owner prospecting. Its combination of property screening, document derived context, entity research and portfolio visibility addresses a real gap between finding an asset and starting a relevant conversation. Published individual pricing makes a controlled pilot easy to justify. BestCRE analysis: the platform deserves particular attention from brokers and acquisitions professionals who currently assemble the same answer across several databases and spreadsheets.

    Purchase should remain conditional on a market specific data test. Verify ownership on known difficult entities, call a sample of returned numbers, reconcile extracted lease and financial fields, and confirm how results move into the firm’s CRM. If DealGround materially improves valid contacts and prioritization, adopt it with defined verification rules. If coverage is inconsistent in the target geography or the team lacks an outbound process, keep the free tier for occasional research and defer a broader commitment.

    About BestCRE

    BestCRE.com is the definitive authority on commercial real estate AI, analysis, and investment intelligence. Every article advances the platform’s mission to help CRE professionals identify, evaluate, and adopt the best tools and strategies in the industry. We benchmark platforms using the 9AI Framework so CRE leaders can compare tools with clear evidence. Explore the category map at 20 CRE sectors for deeper coverage across the CRE stack.

    Frequently Asked Questions

    What is DealGround for commercial real estate?

    DealGround is a commercial real estate data and prospecting platform for brokers, investors and acquisitions teams. Users search for properties by geography, tenant, owner, asset class and other CRE criteria, then review available transaction, lease, financial, debt and marketing context. The platform also researches the legal ownership entity to identify potential principals, contact information and related holdings. Its document tools extract structured information from brochures, offering memorandums and rent rolls, making those materials searchable alongside other property records. BestCRE analysis: its main purpose is to shorten the path from a target property to an informed owner conversation. It is not a replacement for legal title work, final underwriting, a transaction room or a complete brokerage CRM.

    How does DealGround compare with Reonomy and PropertyRadar?

    DealGround, Reonomy and PropertyRadar can all support property and owner prospecting, but their emphasis differs. Reonomy is an established enterprise property intelligence option with broad ownership and property search capabilities. PropertyRadar is strong for parcel centered research, owner information and list building. DealGround differentiates itself by combining owner research with information extracted from CRE documents, including tenant, lease and financial details, then displaying portfolio context and source information in the prospecting workflow. BestCRE analysis: DealGround is most compelling when a buyer wants both a reachable principal and a property specific reason to call. The right choice depends on local coverage and actual contact quality, so buyers should run the same representative property sample through each platform rather than compare feature pages alone.

    How much does DealGround cost?

    DealGround offers a free plan with limited ownership research and property records. Its published Pro subscription costs $99 per user when billed monthly or $999 per user when billed annually, with a 14 day trial. Pro includes expanded records, document automation, AI chat, saved search alerts, spreadsheet export, team sharing and specified research capacity. Enterprise plans use custom pricing based on team size and API usage. Prices for extra ownership research packages are not publicly stated. BestCRE analysis: prospective customers should confirm which usage events consume an allowance, whether unsuccessful research counts, how overages are priced and what happens to data after cancellation. Enterprise buyers should also document implementation, renewal, API and export terms in the order form.

    Who should use DealGround?

    DealGround suits investment sales brokers, developers, acquisitions analysts and investors who build pipeline through direct owner outreach. It is especially relevant for teams that repeatedly search public records, review offering materials, trace LLCs and assemble contact information before making a call. Retail and industrial specialists can use tenant and lease context, while multifamily buyers can combine property filters with ownership and portfolio research. BestCRE analysis: the ideal customer has a defined market, repeatable target criteria and a system for recording outreach. Teams that only pursue marketed deals, make very few acquisitions or already have satisfactory ownership data may see less incremental value. Any buyer should validate local coverage and contact accuracy before deploying the platform across a brokerage or investment team.

    Can DealGround become the main AI prospecting layer for a CRE team?

    DealGround could become a central prospecting layer if it continues connecting property data, private document extraction, ownership resolution, portfolio relationships, alerts and external workflows. Its API and supported AI assistant access provide a foundation for users to query or route information outside the main application. BestCRE analysis: becoming the main layer will depend less on chat features and more on durable data quality, transparent sourcing, stable property identifiers, permission controls and reliable synchronization with systems of record. Buyers should watch for broader CRM coverage, clearer confidence indicators, documented correction processes and stronger administrative controls. Even if those capabilities mature, the platform should guide prospect selection and research rather than make unsupervised underwriting, legal or outreach decisions.

    Related Reviews

    Compare Deal Ground with other tools BestCRE has scored in the same category: CompStak, Dan AI, Happenstance AI. Explore more CRE AI tool reviews in our Best CRE AI Tools directory. For sector-specific analysis and market intelligence, visit our 20 CRE Sectors hub.
  • Density Review: Privacy-safe occupancy data for workplace decisions

    Density Review: Privacy-safe occupancy data for workplace decisions

    BestCRE 9AI Score

    77/100 · Contender

    Density ranks #137 of 400 commercial real estate AI tools scored on the 9AI Framework. Nine dimensions, each scored out of 10: CRE relevance, data quality, ease of adoption, output accuracy, integration fit, pricing transparency, support, innovation and market reputation.

    Density is an occupancy sensing and workplace analytics company used by corporate occupiers, workplace strategists and real estate teams. Its role begins after space exists but before leaders decide how much of it they need, how it should be configured or where underuse justifies consolidation. Sensors collect anonymous people counts, while software turns those observations into utilization patterns across rooms, desks, open areas and entrances. That makes Density relevant to portfolio planning, occupancy planning and workplace design, although it is adjacent to core CRE systems rather than a transaction, accounting or building design platform.

    The buying case rests on a familiar problem: badge swipes, bookings and employee surveys reveal intent or access, not dependable use of individual spaces. Density gives decision makers another evidence layer by observing actual presence without identifying occupants. Analysis: this can improve confidence when choosing room mixes, comparing locations or testing whether assigned capacity reflects demand. The data still requires interpretation. A low utilization rate can indicate excess space, an unsuitable layout, hybrid work patterns or an operational issue, and the platform cannot determine the cause by itself.

    The product range spans Waffle, Open Area and Entry sensors, plus Atlas analytics, workplace applications, live wayfinding and an API. Waffle is positioned as a self-installable radar sensor for rooms, phone booths and desks. Density says it reports counts in bands of zero, one, two or three-plus people, with real-time and historical data. Its compact, powered design and Wi-Fi connectivity reduce deployment friction compared with sensor programs that require extensive wiring, batteries or specialized installation.

    BestCRE analysis: Density is a strong occupancy intelligence product for organizations prepared to use measured utilization in real estate governance. Its privacy posture, sensor design and portfolio application are meaningful strengths. The constraints are equally important. Counts are not explanations, workplace policies can change faster than planning cycles, and hardware coverage must be sufficient to support the decision being made. Buyers should run a defined pilot, compare readings with manual observations and establish which portfolio actions will follow before scaling.

    What Density Does and How It Works

    Density measures how many people occupy selected spaces and sends those observations into software for current and historical analysis. Waffle uses radar and is designed for self-installation in rooms, phone booths and desk settings. Published specifications include an adjustable range of up to 18 feet, dual-band Wi-Fi, powered operation and latency below one second. Its reported output distinguishes zero, one, two and three or more occupants rather than identifying individuals. Open Area and Entry products address broader spatial and threshold-counting requirements. Together, these devices can create a utilization dataset across several layers of a workplace, from an individual booth to a floor entrance.

    Atlas is the analytical layer. Workplace teams can examine occupancy and utilization patterns, compare spaces and use the results in planning discussions. Density also presents applications for workplace design, occupancy planning, adaptive cleaning, live wayfinding and Atlas for Workplace. The value comes from connecting time-stamped observations to recognizable space types and locations. A planner can test whether meeting rooms are routinely full, whether large rooms host small groups, or whether certain areas remain unused. Analysis: the most decision-useful metrics are sustained patterns across representative periods, not isolated peaks or a single weekly average.

    The API provides real-time and historical access for organizations that want Density data in another system, dashboard or operational workflow. That can support internal business intelligence, wayfinding interfaces or connections with workplace applications. Buyers still need a reliable inventory of spaces, naming conventions and ownership of data governance. Sensor placement, connectivity and physical changes can affect continuity, while unusual events can distort comparisons. Density supplies the measurement and analytical environment, but portfolio recommendations remain a management judgment. A defensible deployment therefore combines technical validation, an agreed measurement window and explicit thresholds for actions such as reconfiguration, cleaning changes or lease-event analysis.

    9AI Framework: Dimension by Dimension Analysis

    CRE Relevance: 8/10

    Score: 8 out of 10. Density addresses a consequential corporate real estate question: how much space is actually being used, when and by how many people. Its outputs can inform occupancy planning, workplace design, consolidation studies and discussions around upcoming lease events. That is more specific to the built environment than generic business intelligence, but the platform remains CRE-adjacent because it does not design buildings, execute transactions or manage leases. Analysis: its relevance is highest when a workplace team has authority to act on the findings and can connect sensor data to portfolio costs and planning decisions. It is lower for owners concerned primarily with investment underwriting, construction delivery or tenant financial performance. The score reflects strong alignment with occupier workflows, tempered by a relatively narrow focus on physical utilization.

    Data Quality and Sources: 8/10

    Score: 8 out of 10. Density produces first-party observations from installed sensors rather than relying only on reservations, access events or self-reported attendance. Anonymous counting is well suited to utilization analysis because it measures presence while limiting collection of personally identifiable information. Multiple sensor types can also support different spatial contexts. Data quality nevertheless depends on correct placement, network reliability, configuration and adequate coverage. Waffle’s occupancy bands are useful for many planning questions but do not provide an exact count once occupancy reaches three or more people. Analysis: that tradeoff is reasonable for booths, desks and smaller rooms, yet it may constrain analyses requiring precise group sizes. Buyers should validate readings against manual counts, document exclusions and monitor gaps before treating the dataset as a portfolio baseline.

    Ease of Adoption: 8/10

    Score: 8 out of 10. Waffle’s self-installable, powered design directly addresses two common barriers to occupancy programs: installation labor and battery management. Wi-Fi connectivity and flexible mounting options should make a limited pilot practical for many workplace teams, subject to corporate network approval. The software offers both current and historical views, allowing users to begin with standard analysis before building custom workflows. Adoption still involves more than attaching sensors. Information security review, facilities coordination, communications with employees, space mapping and agreement on metric definitions can slow deployment. Analysis: Density has reduced the physical burden, but organizational readiness remains decisive. A buyer with clean floor and room records can move quickly. A fragmented enterprise with inconsistent naming, restrictive networks or no owner for utilization decisions may find that governance takes longer than installation.

    Output Accuracy: 7/10

    Score: 7 out of 10. Density publishes concrete Waffle specifications, including occupancy bands, field of view, range and data latency. Those details help buyers match the device to appropriate environments. The privacy-safe approach avoids identity inference, but it also means the system explains how many people are present rather than who they are or why they selected a space. Accuracy in practice will vary with placement, room geometry and the product selected. The vendor does not publish a universal accuracy rate applicable to every installation and space type. Analysis: buyers should avoid treating any sensor claim as a substitute for site validation. A pilot should include representative booths, rooms and open areas, plus manual observations at different demand levels. The score recognizes credible measurement mechanics while reserving judgment on accuracy across diverse real estate conditions.

    Integration and Workflow Fit: 8/10

    Score: 8 out of 10. Density offers an API with real-time and historical data, which is the key requirement for organizations that want occupancy information outside the vendor interface. Potential destinations include business intelligence tools, workplace applications, wayfinding experiences and internal portfolio dashboards. Density also offers its own Atlas applications, so a buyer does not need to create every analytical view from scratch. The harder integration issue is semantic rather than technical: sensor identifiers must map correctly to buildings, floors, rooms and space types used elsewhere. Analysis: the API makes Density more adaptable than a closed sensor product, but buyers should confirm authentication, rate limits, retention, export formats and connector responsibility during procurement. Public information does not establish a complete list of supported third-party CRE platforms, so specific integrations should be demonstrated before contract signature.

    Pricing Transparency: 9/10

    Score: 9 out of 10. Density publishes unusually specific Waffle pricing. The sensor is listed at $229 per unit. Software for rooms and phone booths is listed at $8 per unit per month when billed annually, while desk software is listed at $2.50 per unit per month on the same billing basis. An All Spaces option is listed at $15 per unit billed monthly, and large-volume buyers are directed to contact the company. This transparency gives buyers a credible starting point for pilot budgeting and comparison. It does not establish the complete cost of every Density product, deployment or enterprise service. Open Area, Entry, advisory work, networking effort and negotiated volume terms may require a quote. Analysis: the score reflects clear entry pricing, with one point withheld because total enterprise cost still depends on scope.

    Support and Reliability: 6/10

    Score: 6 out of 10. Density provides a help center and publishes support-related resources, including a service level agreement and support policy. It also offers advisory services, which may help customers translate utilization data into workplace design or occupancy decisions. However, the vendor does not publish enough detail to assess the typical quality, speed or depth of implementation support across customer tiers. Public pricing does not clarify which onboarding, training or account-management services are included with each software option. Analysis: support requirements will differ sharply between a self-installed room pilot and a portfolio deployment involving multiple networks, sensor types and business systems. Buyers should negotiate response targets, replacement procedures, installation responsibilities, data-quality monitoring and named escalation paths. The score is neutral-positive because support infrastructure is visible, but independently verifiable service performance is not sufficiently published.

    Innovation and Roadmap: 8/10

    Score: 8 out of 10. Density’s strongest innovation is not people counting alone, which is an established category, but the combination of privacy-safe sensing, compact hardware, self-installation and immediate analytical access. Waffle’s radar approach and powered design target practical deployment constraints that have limited the scale of earlier workplace sensor programs. The availability of real-time and historical data through both applications and an API broadens the product beyond a stand-alone counter. Analysis: this is useful product engineering directed at adoption economics, privacy and operational maintenance. The occupancy bands also illustrate a deliberate tradeoff between detailed counting and a simpler use case. Density does not eliminate the need for planning judgment, and artificial intelligence is not the core source of value. The score reflects differentiated execution in occupancy intelligence rather than a wholly new category.

    Market Reputation: 7/10

    Score: 7 out of 10. Density is a venture-backed company with a recognizable position in occupancy sensing and workplace analytics. Its product range, public technical materials, trust resources and direct pricing for Waffle indicate a more established commercial offering than an early prototype. The vendor also operates in a competitive market where buyers can compare its approach with VergeSense, Occuspace and broader workplace platforms. Density does not publish enough current information to verify total customers, installed sensor count, revenue, profitability or customer retention, so those measures should not be inferred. Analysis: the company appears credible enough for an enterprise pilot and formal procurement review, but market standing should be validated through recent references matching the buyer’s scale and use case. The score recognizes category visibility while avoiding assumptions about undisclosed operating performance.

    9AI Score Card Density
    77
    77 / 100
    Solid Platform
    Occupancy Analytics
    Density
    Density combines anonymous people-counting sensors, historical utilization analytics and APIs to help workplace teams plan offices using observed demand rather than assumptions.
    9 Dimensions, Scored 1 to 10
    1. CRE Relevance
    8/10
    2. Data Quality & Sources
    8/10
    3. Ease of Adoption
    8/10
    4. Output Accuracy
    7/10
    5. Integration & Workflow Fit
    8/10
    6. Pricing Transparency
    9/10
    7. Support & Reliability
    6/10
    8. Innovation & Roadmap
    8/10
    9. Market Reputation
    7/10
    BestCRE.com, 9AI Framework v2 Reviewed October 2026

    Who Should Use Density

    Density is best suited to corporate occupiers with a meaningful office portfolio, hybrid attendance patterns and an active decision calendar. Workplace strategy, facilities and corporate real estate teams can use it when evaluating room mix, desk supply, floor consolidation or renewal options. The strongest buyer has a specific hypothesis, such as whether large conference rooms are being consumed by small groups, and a defined action if the evidence supports it. Organizations that need anonymous counts rather than employee-level monitoring should also find the privacy model attractive.

    It also suits operators seeking real-time inputs for wayfinding or occupancy-informed services, provided they can maintain reliable connectivity and space records. Smaller organizations may find Waffle’s published entry pricing and self-installation approachable for a focused deployment. Analysis: the ideal customer is not simply data curious. It has an executive sponsor, a representative measurement period and authority to change layouts, operating schedules or portfolio commitments. Teams approaching a lease event can gain particular value if installation occurs early enough to observe normal demand before options must be decided.

    Who Should Not Use Density

    Density is not the right primary system for owners or investors seeking underwriting, leasing, accounting, construction management or asset valuation. It measures use of physical space but does not replace a lease administration platform, integrated workplace management system or architectural design application. Organizations looking for individual attendance records should also choose another approach, since anonymous counting is a deliberate product characteristic.

    Buyers should hesitate if they lack a decision tied to the data, cannot obtain network approval or cannot maintain an accurate space inventory. A few sensors installed only in convenient locations may produce an unrepresentative view that is weaker than a disciplined manual study. Analysis: companies with highly volatile attendance, frequent physical reconfiguration or very small offices may struggle to recover the operating effort unless the deployment supports a concrete planning or service outcome. Exact headcounts above Waffle’s highest occupancy band may require a different Density sensor or another measurement method.

    Pricing and ROI Analysis

    Density publishes Waffle hardware and software pricing, which supports preliminary budgeting without a sales call. A sensor costs $229. Annual-billing software is listed at $8 per room or phone booth each month and $2.50 per desk each month. The All Spaces plan is listed at $15 per unit when billed monthly. Large-volume orders require direct contact. Pricing for the broader Open Area and Entry products, advisory services and enterprise deployment is not fully published, so buyers should request an itemized quote covering installation, replacements, software, data retention, support and integrations.

    Analysis: consider a pilot with 20 room sensors using the annually billed room plan. Hardware would total $4,580, and the first year of software would total $1,920, producing a first-year product cost of $6,500 before tax, networking, labor or professional services. If the resulting evidence prevents one unnecessary room build, supports a floor consolidation or improves a material lease decision by more than that amount, the pilot has paid for itself. That is a decision test, not a promised return. Buyers should define the financial action and required confidence level before deployment.

    Integration and CRE Tech Stack Fit

    Density can fit beside an integrated workplace management system, reservation platform, business intelligence environment or internal real estate data warehouse. Its API exposes real-time and historical occupancy information, while Atlas supplies native analysis for teams that do not want to build every dashboard. A practical architecture maps each sensor to the same building, floor, room and space identifiers used by the rest of the CRE stack.

    Buyers should test more than data transfer. They should verify refresh timing, history availability, authentication, export controls and the behavior of mappings when rooms are renamed or reconfigured. Public information does not confirm every connector or implementation pattern, so a claimed integration should be demonstrated using the buyer’s systems. Analysis: Density is most valuable as an observed-use layer. Reservations show planned demand, badges indicate access and lease systems show obligations. Combining those records can explain portfolio performance better than any source alone.

    Competitive Landscape

    VergeSense is the closest broad alternative for buyers comparing workplace occupancy intelligence, sensor coverage and portfolio analytics. Occuspace is another direct option, particularly where customers want occupancy measurement across larger areas with a different sensing architecture. Density distinguishes itself through privacy-safe devices, multiple sensing formats and Waffle’s self-installation and published pricing. A structured evaluation should compare accuracy in representative rooms, deployment labor, network requirements, analytical workflows and total multi-year cost.

    Occupier competes at a different layer. It focuses more heavily on lease administration, transaction management and portfolio workflows, making it more appropriate when the main problem is obligations and real estate process rather than physical-use measurement. Eptura offers a broader workplace and asset-management suite and may suit buyers seeking reservations, facilities workflows and portfolio capabilities from fewer vendors. Density can complement either type of platform if occupancy observations can be mapped cleanly into the wider data model.

    Autodesk Forma, TestFit, qbiq, Snaptrude, Motif, LightTable and ArchiLabs address planning or design workflows more directly. They can help generate, test or communicate spatial options, while Density supplies evidence about how existing space performs. Analysis: buyers should not frame these as perfect substitutes. The choice depends on whether the immediate bottleneck is measuring current use, administering the portfolio or producing a future design.

    The Bottom Line

    Buy Density when an upcoming portfolio or workplace decision requires defensible evidence about actual occupancy, and when the organization is prepared to act on the findings. Start with a representative pilot, validate sensor results against manual observations and connect the measurement period to a lease, design or operating decision. The published Waffle pricing makes that first test easier to budget than many enterprise sensor programs.

    Do not buy it merely to create another dashboard. Density’s measurements become valuable only when combined with accurate space records, cost data and accountable decision making. BestCRE analysis: the product ranks as a strong choice for privacy-conscious occupiers that want scalable occupancy evidence, especially where self-installation matters. Buyers requiring exact counts in every setting, extensive lease workflows or architectural generation should evaluate complementary products or alternatives before committing.

    About BestCRE

    BestCRE.com is the definitive authority on commercial real estate AI, analysis, and investment intelligence. Every article advances the platform’s mission to help CRE professionals identify, evaluate, and adopt the best tools and strategies in the industry. We benchmark platforms using the 9AI Framework so CRE leaders can compare tools with clear evidence. Explore the category map at 20 CRE sectors for deeper coverage across the CRE stack.

    Frequently Asked Questions

    What is Density occupancy software?

    Density is a workplace occupancy sensing and analytics platform. Corporate real estate, facilities and workplace teams install its sensors in entrances, open areas, rooms, phone booths or desk settings, depending on the product. The resulting anonymous people counts feed software that shows current and historical use. Teams can use those patterns to evaluate room mix, desk demand, workplace services and potential portfolio changes. Density is not a lease administration, architectural design or employee-tracking system. Its core role is to provide observed evidence about how physical space is used. Analysis: it is most valuable when a buyer has a defined real estate decision and enough representative coverage to support that decision.

    How does Density compare with VergeSense and Occuspace?

    Density, VergeSense and Occuspace all help organizations measure workplace occupancy, but their sensor architectures, installation models, spatial coverage and analytical experiences differ. Density offers Entry and Open Area products plus Waffle, a powered radar sensor designed for self-installation in rooms, phone booths and desk environments. Waffle reports anonymous occupancy bands and supplies real-time and historical data. Buyers should compare each platform in representative spaces rather than selecting from a feature sheet. Test counting performance, network approval, installation labor, maintenance, privacy review, API access and multi-year cost. Analysis: Density is especially compelling when compact hardware, anonymous measurement and a low-friction room-level pilot are priorities. Another vendor may fit better where area-level coverage or an existing enterprise relationship dominates.

    How much does Density cost?

    Density publishes pricing for Waffle but not a complete price schedule for every product and service. Waffle hardware is listed at $229 per sensor. Software for rooms and phone booths is listed at $8 per unit per month when billed annually, and desk software is listed at $2.50 per unit per month on the same billing basis. An All Spaces option is listed at $15 per unit billed monthly. Large-volume orders require direct contact. Pricing for Open Area sensors, Entry sensors, advisory services and some enterprise requirements is not fully published. Buyers should ask for a complete quote that identifies hardware, subscriptions, installation, support, replacement terms, retention and integration costs.

    Who should use Density occupancy sensors?

    Density best suits corporate occupiers, workplace strategy teams, facilities leaders and real estate groups managing hybrid offices or material space commitments. Strong use cases include evaluating meeting-room mix, measuring booth and desk demand, testing workplace changes, informing consolidation and supplying live occupancy data to wayfinding or operational applications. Privacy-conscious organizations may prefer its anonymous counting approach to camera-based or identity-linked attendance systems. Analysis: the best buyer has a clear question, a representative deployment plan and authority to act on the answer. It is less suitable as a primary tool for investment underwriting, lease accounting, construction management or architectural generation. Small organizations should confirm that the expected decision value exceeds the effort of maintaining sensors and data.

    Will Density become more useful as hybrid work evolves?

    Density could become more useful as workplace demand remains variable because periodic surveys and badge records do not fully describe how individual spaces perform. Real-time and historical occupancy data can help teams revisit assumptions as attendance patterns, policies and layouts change. Future value will depend on how well Density connects observations with reservations, portfolio costs, service workflows and planning tools. The vendor already offers an API and applications spanning analytics, wayfinding and occupancy planning, providing a foundation for those connections. Analysis: the important development is not simply more automation or more charts. It is whether the platform helps customers move from counts to repeatable decisions, while maintaining privacy, data quality and manageable deployment costs across a portfolio.

    Related Reviews

    Compare Density with other tools BestCRE has scored in the same category: Autodesk Forma, TestFit, qbiq. Explore more CRE AI tool reviews in our Best CRE AI Tools directory. For sector-specific analysis and market intelligence, visit our 20 CRE Sectors hub.
  • NIC MAP Vision Review: Senior housing market data for investment decisions

    NIC MAP Vision Review: Senior housing market data for investment decisions

    BestCRE 9AI Score

    76/100 · Contender

    NIC MAP Vision ranks #152 of 398 commercial real estate AI tools scored on the 9AI Framework. Nine dimensions, each scored out of 10: CRE relevance, data quality, ease of adoption, output accuracy, integration fit, pricing transparency, support, innovation and market reputation.

    NIC MAP Vision, now presented primarily under the NIC MAP brand, is a market intelligence platform built for senior housing and care real estate. Investors use it to compare markets and assets, lenders use it to test underwriting assumptions, developers use it to assess demand and construction pipelines, and operators use it to benchmark property performance. Its core workflow contribution is replacing fragmented market research with standardized property, occupancy, rent, supply and demographic information.

    The platform matters because senior housing cannot be evaluated adequately through conventional apartment or general commercial property data. Care type, resident needs, operator performance, local demographics, inventory composition and development pipelines can materially change an investment thesis. NIC MAP organizes those variables around senior housing rather than forcing analysts to adapt a broad property database. The company says its coverage includes more than 35,000 properties across the United States, giving users a substantial starting universe for screening and comparison.

    Its strongest position is as a reference source for market occupancy, supply and performance trends. That makes it particularly useful during market selection, acquisition screening, development feasibility and credit review. A buyer can move from a metropolitan overview into property comparisons without assembling every input manually. The platform also includes a CMBS financial dataset, extending its relevance to debt and transaction research, although buyers should confirm the fields, history and export rights included in their proposed subscription.

    BestCRE analysis: NIC MAP Vision is one of the clearest examples of a vertical CRE data product earning its place through specialization rather than feature breadth. It should not be treated as a complete underwriting system, operating platform or universal property database. Its value depends on whether senior housing is important enough to the buyer’s portfolio to justify a dedicated source. For firms active in the sector, the evidence suggests a serious diligence product. For occasional users, price, coverage and workflow fit require closer examination.

    What NIC MAP Vision Does and How It Works

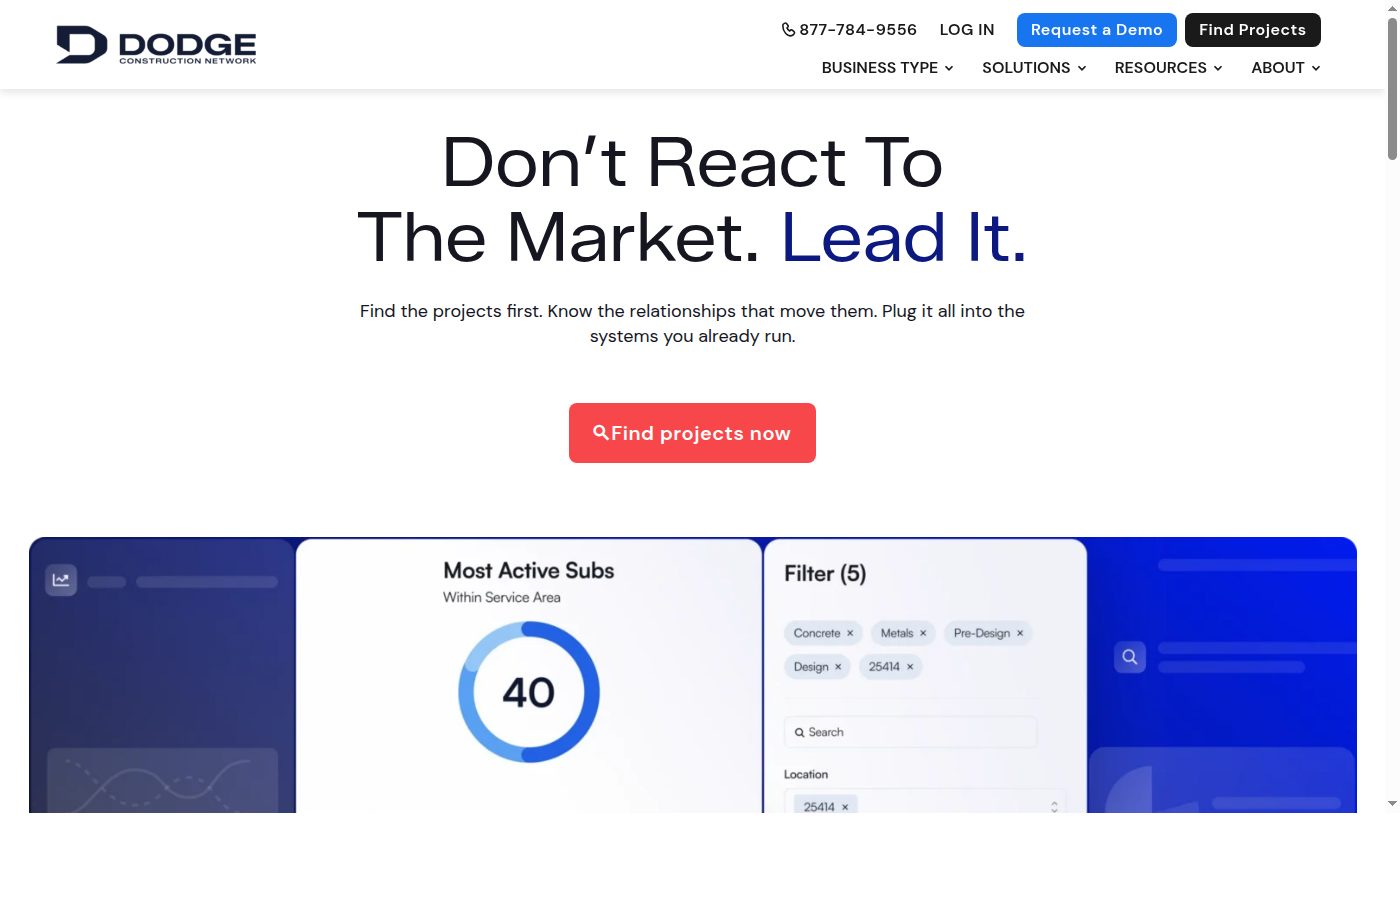
    NIC MAP Vision centralizes market and property intelligence used to evaluate senior housing opportunities. Users can examine occupancy, asking rents or rates, inventory, absorption, construction activity, ownership, operators and local demand indicators. The practical mechanic is comparison: an analyst selects a market, property set or competitive area, reviews standardized observations, and tests whether an asset’s performance or development assumptions are credible relative to peers. Side by side market analysis can reduce the spreadsheet work required to normalize inconsistent broker packages and operator disclosures.

    For development and investment work, the platform connects existing supply with planned inventory and demographic demand. That helps users identify markets where population growth may support additional capacity, then examine whether the pipeline already absorbs that opportunity. Operators can use property and market benchmarks to find performance gaps, while vendors and healthcare providers can use ownership, operator and location data for account targeting or partnership planning. Its published market fundamentals report draws from over 15,000 senior housing and care properties in 214 metropolitan markets, illustrating the type of sector benchmark the underlying data can support.

    The product should be understood as decision support, not an automated investment committee. Occupancy and rate comparisons can sharpen an underwriting case, but they do not independently establish property condition, staffing stability, care quality, regulatory exposure or achievable cash flow. Data frequency, field definitions and coverage can also vary by market and property type, so serious users should inspect source methodology and sample depth before treating a result as representative. BestCRE analysis: the platform’s best use is to establish market context, challenge sponsor assumptions and direct deeper diligence toward the variables most likely to change a deal.

    9AI Framework: Dimension by Dimension Analysis

    CRE Relevance: 10/10

    NIC MAP Vision is CRE native and unusually specific within the sector. Its data maps directly to senior housing acquisition, development, lending, operating and market selection decisions. Occupancy, rates, inventory, absorption, construction pipelines, demographics, ownership and operator information are not peripheral research inputs here. They are central to underwriting and portfolio strategy. The inclusion of care property coverage and CMBS financial information further connects the platform to healthcare real estate and debt analysis. BestCRE analysis: the maximum score is justified because the product is designed around identifiable commercial property workflows and serves participants who own, finance, develop or operate physical assets. Its narrow sector focus limits applicability outside senior housing, but that does not reduce its relevance within the category. Buyers seeking a general CRE database should view specialization as a boundary, while sector specialists should view it as the main advantage.

    Data Quality and Sources: 9/10

    The platform’s strongest asset is the depth and continuity of its senior housing dataset. Longitudinal occupancy, rate, inventory and construction information allows users to distinguish a temporary movement from a structural market pattern. Standardized property and market fields also support comparisons that would be difficult to produce consistently from individual offering memoranda. The vendor publicly describes more than two decades of historical market information and 16,000 or more rate and occupancy comparables. BestCRE analysis: those characteristics support a high score, but buyers still need field level diligence. They should ask how properties enter the database, how frequently each measure is refreshed, how estimates are distinguished from reported values, and where coverage becomes thin. A large national universe does not guarantee equal sample quality in every local submarket, care segment or competitive set. Data licensing and permissible downstream use also need contractual confirmation.

    Ease of Adoption: 8/10

    NIC MAP Vision organizes research around recognizable senior housing questions, including market comparison, deal evaluation, supply pipelines and operating benchmarks. That should shorten adoption for analysts already familiar with occupancy, inventory and rate terminology. The platform’s audience specific positioning also suggests that investors, lenders, developers and operators can begin from workflows relevant to their roles rather than navigating a generic property database. BestCRE analysis: adoption is likely easier at the research layer than at the organizational layer. Users still need agreement on competitive sets, market boundaries, care categories and acceptable underwriting uses. Teams should establish when NIC MAP data overrides, supplements or merely checks information supplied by an operator or broker. Training requirements, onboarding duration and implementation services are not published in sufficient detail to assume a uniform experience. A controlled pilot using several familiar markets is the safest way to measure usability and analyst time savings.

    Output Accuracy: 8/10

    NIC MAP Vision provides standardized observations and benchmarks, which can improve consistency compared with manually assembled market surveys. Its historical perspective is especially valuable when analysts need to assess whether current occupancy, rent or construction conditions depart from established patterns. Accuracy, however, must be separated from decision validity. A correctly reported market average may still be a poor comparison for a property with different care levels, age, quality, unit mix or operator profile. BestCRE analysis: the score recognizes a credible sector dataset while preserving room for verification at the asset level. Buyers should test known properties against platform records, document the dates associated with each field and examine how missing observations are handled. They should also distinguish reported data from modeled demand or forward projections. The platform can make an underwriting process more disciplined, but it cannot eliminate judgment about competitive positioning or future operating performance.

    Integration and Workflow Fit: 6/10

    NIC MAP Vision can fit naturally into a research workflow through exports and analyst review, but the vendor does not publish enough technical detail to treat it as an open data infrastructure layer. Public information emphasizes the platform and its decision workflows more than APIs, warehouse connectors, identity standards or packaged integrations with underwriting and CRM systems. The CMBS dataset may expand its usefulness for debt research, although access format and linkage methods should be confirmed during procurement. BestCRE analysis: the integration score is therefore moderate. A buyer that mainly needs browser based analysis and spreadsheet output may find the available workflow sufficient. A firm seeking automated ingestion into a data lake, proprietary scoring model or portfolio dashboard should request documentation, sample exports, update schedules and licensing terms before committing. The decisive question is not whether data can leave the interface, but whether it can do so reliably, repeatedly and within contractual rights.

    Pricing Transparency: 4/10

    NIC MAP Vision does not publish standard subscription prices, plan thresholds or data licensing fees on its public website. Prospective customers are directed toward a consultation, which means a buyer cannot estimate total cost without entering a sales process. The final quote may vary with user count, modules, markets, coverage, exports or permitted uses, but the vendor does not publicly explain the pricing formula in enough detail for direct comparison. BestCRE analysis: this materially limits pricing transparency and caps the score below the framework threshold. Enterprise data products often require scoped contracts, yet buyers still benefit from published starting prices or clear packaging. Procurement teams should request an itemized proposal that separates platform access, additional seats, datasets, historical depth, implementation, support, exports and renewal increases. They should also confirm whether internal presentations, investment memoranda, portfolio models and client deliverables are permitted uses under the license.

    Support and Reliability: 7/10

    NIC MAP positions its service around consultation and industry expertise, and its public customer commentary references responsiveness and delivery. That is directionally encouraging for a specialized product because users often need help interpreting definitions, coverage and competitive sets, not merely resolving login problems. The platform also publishes market research that can help customers understand broader sector conditions. However, the vendor does not publish detailed service levels, support hours, response commitments, onboarding schedules or named success coverage for each subscription tier. BestCRE analysis: support appears credible but cannot receive a top score without clearer evidence about contracted service. Buyers should ask who handles data questions, how suspected errors are investigated, whether methodology specialists are available and what assistance is included during implementation. A useful pilot should include at least one support case involving a disputed property field, because the quality and speed of that response reveal more than a generic product demonstration.

    Innovation and Roadmap: 7/10

    NIC MAP Vision’s innovation lies primarily in sector specialization, longitudinal data and the combination of market, property, demographic and financial context. It is not necessary for the product to depend on novel generative AI to improve a difficult CRE workflow. A well maintained reference dataset, designed around senior housing decisions, can create more defensible value than an experimental interface. The platform also supports forward looking work through demand indicators and development pipeline analysis. BestCRE analysis: the score reflects meaningful analytical differentiation without assuming capabilities the vendor has not publicly documented. Public materials do not provide enough technical detail about machine learning, automated forecasting, natural language analysis or model governance to judge those areas highly. Buyers should evaluate the product on coverage, methodology and workflow speed rather than on an AI label. Future gains are most likely to come from easier interrogation, stronger interoperability and clearer connection between market signals and asset level decisions.

    Market Reputation: 9/10

    NIC MAP has a long standing position in senior housing research and is widely recognized among investors, lenders, developers, operators and industry advisers. Its historical market series and recurring sector benchmarks give it a reference role that newer entrants would find difficult to reproduce quickly. The company states that its information is used by more than 8,000 senior housing stakeholders, although buyers should interpret that as a vendor reported measure rather than a count of paying customer organizations. BestCRE analysis: the platform earns a high reputation score because it is associated with a defined professional market, a durable dataset and repeated use in investment and operating discussions. It stops short of the maximum because public brand recognition does not substitute for contract specific validation. Buyers should still request references resembling their own organization, especially if they need smaller market coverage, enterprise integration, lender workflows or extensive redistribution rights.

    9AI Score Card NIC MAP Vision
    76
    76 / 100
    Solid Platform
    CRE Market Analytics
    NIC MAP Vision
    NIC MAP Vision gives senior housing investors, lenders, developers and operators a specialized benchmark for occupancy, rents, supply, demand and property performance.
    9 Dimensions, Scored 1 to 10
    1. CRE Relevance
    10/10
    2. Data Quality & Sources
    9/10
    3. Ease of Adoption
    8/10
    4. Output Accuracy
    8/10
    5. Integration & Workflow Fit
    6/10
    6. Pricing Transparency
    4/10
    7. Support & Reliability
    7/10
    8. Innovation & Roadmap
    7/10
    9. Market Reputation
    9/10
    BestCRE.com, 9AI Framework v2 Reviewed October 2026

    Who Should Use NIC MAP Vision

    NIC MAP Vision is best suited to senior housing investors, acquisition teams and lenders that repeatedly evaluate properties across multiple markets. These buyers can use consistent occupancy, rate, supply and demand information to screen opportunities, challenge offering materials and build comparable market sections for investment or credit memoranda. Developers assessing site feasibility are another strong fit because pipeline and demographic context can expose markets where apparent demand is already being addressed by planned inventory. Healthcare real estate teams expanding beyond medical office properties may also value a purpose built view of senior living supply.

    Operators with regional or national portfolios should consider the product when they need external benchmarks for property performance or strategic market planning. Research teams, valuation professionals and vendors serving senior housing may also benefit from ownership and operator intelligence. BestCRE analysis: the economic case becomes strongest when several professionals reuse the same data across acquisitions, development, finance and operations. A buyer should have enough transaction or portfolio volume to make standardized research a recurring process rather than an occasional project. The ideal customer also has an analyst or research lead responsible for methodology, permissions and consistent competitive set construction.

    Who Should Not Use NIC MAP Vision

    Firms with little or no senior housing exposure should not buy NIC MAP Vision as their primary CRE intelligence platform. Its specialization is an advantage only when the sector matters to the portfolio. A generalist brokerage, industrial investor or retail operator will probably receive broader utility from CoStar or another cross sector property database. Small teams evaluating one isolated opportunity may be better served by targeted third party research, local market interviews and operator diligence, depending on subscription cost.

    The product is also a weaker fit for buyers seeking a complete financial underwriting, asset management or operational care system. Market data can inform assumptions, but it does not replace a property model, accounting system, resident platform or physical diligence. Teams requiring an extensively documented API or automated warehouse feed should not assume NIC MAP will meet that need without written technical confirmation. BestCRE analysis: if the purchase case depends mainly on automation rather than proprietary senior housing coverage, another data architecture may deserve priority.

    Pricing and ROI Analysis

    NIC MAP Vision does not publish subscription prices, standardized packages or a public rate card. Buyers must schedule a consultation to receive a proposal. That approach prevents a reliable public estimate of annual cost and makes competitive comparison harder. A proposal should specify included markets, datasets, historical access, seats, exports, onboarding, support, renewal terms and internal distribution rights. Firms should also ask whether the CMBS dataset is included or separately licensed. Any cost figure offered without a vendor quote would be speculation.

    Analysis: calculate return using avoided research hours and decisions improved, not vague claims about better intelligence. If an acquisition team reviews 40 opportunities annually and the platform saves four analyst hours on each, the direct benefit is 160 hours multiplied by the firm’s fully loaded hourly cost. Add any avoided spending on separate market studies, then compare that total with the quoted subscription and implementation cost. Do not assign value to a prevented bad investment unless the firm can document how the data changed a real decision. A pilot should record time spent before and after adoption, data gaps found, assumptions revised and work products reused across teams.

    Integration and CRE Tech Stack Fit

    NIC MAP Vision fits most clearly between external market research and internal underwriting. Analysts can use its benchmarks to set or challenge assumptions, then carry approved findings into spreadsheet models, investment committee materials, portfolio dashboards or credit files. Ownership and operator information may also support CRM research and business development. The practical fit depends on export formats, field definitions and licensing permissions, all of which should be reviewed before designing a recurring workflow.

    Public technical information does not establish the availability or scope of an API, packaged data warehouse connector or native integrations with common CRE systems. Buyers should therefore avoid assuming automated interoperability. BestCRE analysis: start with a controlled export into the firm’s existing model, test record matching and document every manual transformation. If enterprise ingestion is required, request technical documentation, update cadence, identifiers, sample files, authentication requirements and permitted storage duration in writing. Cherre may be the more relevant alternative when data integration and normalization are the primary problem.

    Competitive Landscape

    CoStar is the most obvious alternative for firms wanting broad commercial property coverage, transaction context and prospecting tools across many asset classes. It has greater cross sector utility, but senior housing teams should compare the depth, definitions and historical consistency of its care property data directly with NIC MAP. Placer.ai approaches market selection from location intelligence and observed visitation patterns. It can help explain trade areas and consumer behavior, but it is not a substitute for specialized occupancy, rate and senior housing supply benchmarks.

    Cherre competes more as a data management and connectivity layer than as a direct senior housing reference source. It is worth considering when the buyer’s main challenge is combining internal and external property information across systems. In that case, NIC MAP data could potentially serve as an input rather than a replacement, subject to technical access and licensing. General demographic providers and local market studies may also supplement any of these products, particularly in thinly covered areas.

    BestCRE analysis: sector specialists should begin with NIC MAP Vision, then test alternatives against a fixed set of known assets and markets. Generalists should reverse that order, starting with CoStar and adding NIC MAP only if senior housing volume justifies dedicated coverage. The decisive comparison should examine property coverage, history, update frequency, definitions, export rights and analyst time, not the number of features shown in a demonstration.

    The Bottom Line

    Buy NIC MAP Vision if senior housing is a recurring investment, lending, development or operating focus and your team needs a common market benchmark. Its specialized dataset addresses variables that general CRE platforms can treat inconsistently or too broadly. Make the purchase contingent on validation in several familiar markets, clear licensing terms and a proposal showing exactly which data and services are included.

    Do not buy it merely to add another research portal. Assign an owner, define the decisions it will support and measure whether it reduces research time or changes underwriting assumptions. BestCRE analysis: NIC MAP Vision is a category leader for senior housing intelligence, but opaque pricing and limited public integration detail prevent an unconditional recommendation. For the right sector specialist, it belongs on the shortlist. For a generalist or occasional buyer, the business case must be proven through a scoped trial.

    About BestCRE

    BestCRE.com is the definitive authority on commercial real estate AI, analysis, and investment intelligence. Every article advances the platform’s mission to help CRE professionals identify, evaluate, and adopt the best tools and strategies in the industry. We benchmark platforms using the 9AI Framework so CRE leaders can compare tools with clear evidence. Explore the category map at 20 CRE sectors for deeper coverage across the CRE stack.

    Frequently Asked Questions

    What is NIC MAP Vision?

    NIC MAP Vision is a commercial real estate market intelligence platform focused on senior housing and care properties. It provides property, market, occupancy, rate, inventory, construction, demographic, ownership and operator information for investors, lenders, developers, operators and related service providers. The product is now presented primarily under the NIC MAP brand. Its role is to give analysts a standardized basis for comparing markets and testing deal assumptions that may otherwise depend on broker packages, operator disclosures and manually assembled surveys. It also includes a CMBS financial dataset. BestCRE analysis: buyers should treat it as a specialized research and benchmarking source, not as a complete underwriting, accounting, resident management or asset management system.

    How does NIC MAP Vision compare with CoStar?

    NIC MAP Vision is narrower than CoStar but more deliberately organized around senior housing. Its value centers on sector specific occupancy, rates, inventory, absorption, construction pipelines and care property comparisons. CoStar covers a much wider range of commercial real estate and may be more useful to firms working across office, industrial, retail, multifamily and other property types. The right choice depends on portfolio concentration. BestCRE analysis: a dedicated senior housing investor should test NIC MAP first because specialized definitions and history may matter more than broad coverage. A diversified CRE firm may prefer CoStar as its primary platform and consider NIC MAP as a specialist addition. Buyers should compare both products using the same known markets, properties and underwriting questions.

    How much does NIC MAP Vision cost?

    NIC MAP Vision does not publish standard prices, subscription tiers or a public starting rate. Prospective customers must request a consultation and obtain a scoped proposal. Pricing may depend on coverage, datasets, users, exports or licensing rights, but the vendor does not publicly provide enough detail to confirm the formula. Buyers should request an itemized quote covering seats, markets, historical data, onboarding, support, renewal increases and permitted internal use. They should also confirm whether specialized financial data is included. BestCRE analysis: compare the final quote with documented analyst hours saved and third party research avoided. Without those measurements, a buyer cannot distinguish productive data spending from another underused software subscription.

    Who should use NIC MAP Vision?

    NIC MAP Vision suits organizations that make repeated decisions about senior housing properties or markets. The strongest buyer profiles are acquisition teams comparing opportunities, lenders validating underwriting assumptions, developers testing demand and planned supply, and operators benchmarking portfolio performance. Healthcare real estate investors, valuation teams, researchers and vendors targeting senior living owners may also find useful intelligence. BestCRE analysis: the product is most defensible when several people reuse the same data across multiple decisions. A firm evaluating only one senior housing asset may not generate enough recurring value to justify a subscription. General CRE teams without meaningful exposure to the sector should begin with a broader property platform and use specialist research only when a transaction requires it.

    Will NIC MAP Vision add more AI and predictive analytics?

    The vendor’s public positioning emphasizes market data, benchmarks and forward looking intelligence, but it does not publish enough technical detail to confirm a specific roadmap for generative AI, machine learning features or automated investment recommendations. Buyers should not base a current purchase on capabilities that have not been released or contractually described. BestCRE analysis: the most valuable future development would be easier natural language interrogation of the dataset, clearer model documentation and stronger connections between market signals and asset level underwriting. Any predictive feature should show its source data, assumptions, update date and uncertainty. For procurement today, evaluate the platform on current coverage, history, workflow speed, exports and decision usefulness, then ask the vendor to demonstrate rather than describe planned analytics.

    Related Reviews

    Compare NIC MAP Vision with other tools BestCRE has scored in the same category: Matterport, Cotality, HelloData. Explore more CRE AI tool reviews in our Best CRE AI Tools directory. For sector-specific analysis and market intelligence, visit our 20 CRE Sectors hub.
  • Dodge Construction Network Review: Construction project intelligence from planning through bidding

    Dodge Construction Network Review: Construction project intelligence from planning through bidding

    BestCRE 9AI Score

    72/100 · Contender

    Dodge Construction Network ranks #202 of 389 commercial real estate AI tools scored on the 9AI Framework. Nine dimensions, each scored out of 10: CRE relevance, data quality, ease of adoption, output accuracy, integration fit, pricing transparency, support, innovation and market reputation.

    Dodge Construction Network is a construction intelligence provider used by general contractors, subcontractors, developers, building product firms, architects, and service providers. For a CRE principal, its central value is earlier visibility into projects moving from planning and design toward procurement and construction. Dodge combines project records, participant relationships, specifications, bidding information, historical starts, forecasts, and research services. This can change how an acquisitions, development, or construction team identifies opportunities, monitors competing supply, finds partners, and prepares for bid activity.

    The company says it tracks more than 700,000 unique projects annually. Its flagship Dodge One product presents project and contact intelligence through web and mobile access, while related offerings address supplier discovery, invitations to bid, specification research, public project signals, and demand forecasting. The breadth is meaningful, but buyers should distinguish between the wider Dodge product portfolio and the specific modules included in a proposed subscription. A familiar company name does not guarantee that every dataset or workflow is available in one package.

    For commercial real estate, Dodge is adjacent rather than purpose built. Its information can support development sourcing, construction planning, market analysis, and contractor outreach, but it is not a property operating system, underwriting platform, leasing database, or investment sales tool. BestCRE analysis: the strongest fit is a CRE organization with a recurring construction pipeline and a team prepared to convert project intelligence into decisions. A small owner buying stabilized assets may find much of the platform outside its daily workflow.

    The principal buying question is therefore not whether Dodge has substantial construction information. It is whether its records arrive early enough, match the buyer’s markets, and contain the contacts and project attributes needed to produce action. Prospective customers should test coverage against known projects, examine update histories, and confirm integration rights before signing. Dodge offers an unusually established data foundation and broad workflow coverage, but unpublished pricing makes value harder to assess without a structured pilot and a clear baseline for current research costs.

    What Dodge Construction Network Does and How It Works

    Dodge One organizes construction opportunities around project stage, location, participants, documents, specifications, bid status, and alerts. Users can search for relevant work, follow projects, identify owners and design or construction firms, and receive notice when matching records change. Dodge describes its reports as field verified and combines automated monitoring with human research. The practical workflow begins with a territory, building type, project stage, or relationship filter, then moves into record review and contact prioritization. For developers, the same information can help monitor planned supply, identify active consultants, and understand where contractors are concentrating.

    The broader platform extends beyond lead discovery. The Blue Book supports connections with subcontractors and suppliers, Bid Board consolidates bid invitations, Sweets addresses product specification, IMS surfaces public work before formal requests are issued, and Principia provides construction market analysis. Dodge also offers forecasts, historical construction starts, custom data, research, and consulting. Its archive includes more than 10 million projects, plans, and specifications, while its historical starts series spans more than five decades. Buyers should verify which history, documents, forecasts, and export permissions belong to their proposed product tier because the company does not publish a simple public entitlement matrix.

    Delivery options include browser access, iOS mobile access, CRM connections, an application programming interface, data feeds, and custom exports. The mobile experience is designed for checking projects, bid status, and alerts away from a desk. Named CRM destinations include Salesforce, HubSpot, and Microsoft Dynamics. Programmatic delivery can support internal dashboards, territory models, relationship systems, or market monitoring, although technical documentation, rate limits, field availability, and implementation terms are not fully published for open evaluation. BestCRE analysis: Dodge works best as a source and monitoring layer feeding an established business development or development workflow, not as the sole system for underwriting, project controls, or asset management.

    9AI Framework: Dimension by Dimension Analysis

    CRE Relevance: 7/10

    A score of 7 reflects strong relevance to development and construction, with clear limits elsewhere in commercial real estate. Project pipelines, participant records, specifications, market forecasts, and bid intelligence can inform supply tracking, development sourcing, consultant selection, and construction business development. These are material workflows for developers and vertically integrated owners. Dodge is less applicable to leasing, property operations, loan surveillance, investment sales, tenant experience, and stabilized asset underwriting. BestCRE analysis: its value rises with the share of a buyer’s strategy tied to ground up development, renovation, public construction, or contractor relationships. A CRE organization should not treat broad construction coverage as a substitute for parcel, ownership, rent, transaction, or operating data. The resulting score recognizes a credible CRE use case without classifying Dodge as a comprehensive real estate platform.

    Data Quality and Sources: 9/10

    A score of 9 reflects the depth, verification model, and historical continuity of the underlying construction dataset. Dodge says records are checked by human researchers for contacts, stage, estimated value, specifications, and related details, with a research organization numbering more than 400 field specialists. The company also reports monitoring municipalities and proprietary sources. That approach is more defensible than relying only on scraped permits or self reported opportunities. No project database is complete, and estimated values, schedules, participants, and bid dates can change quickly. BestCRE analysis: buyers should test recent records in their exact counties and asset classes, rather than assuming national scale produces uniform local coverage. Dodge earns a high score because it combines extensive history with active verification, but it stops short of a perfect score because public evidence does not establish error rates, coverage rates, or update latency by market.

    Ease of Adoption: 7/10

    A score of 7 reflects accessible search, alerts, web access, and mobile delivery, balanced against the complexity of a large construction information environment. Business development users familiar with project leads should understand the core workflow quickly. CRE investment or development teams may need more configuration to define useful stages, territories, asset types, and alert thresholds. The broad portfolio can also complicate purchasing and onboarding because similarly related needs may sit across different products. BestCRE analysis: adoption depends less on interface familiarity than on operating discipline. A team needs ownership for saved searches, lead qualification, record assignment, CRM hygiene, and follow up. Without that process, users can receive abundant information without improving decisions. Public onboarding timelines, training requirements, and standard implementation scope are not published, so buyers should request a guided trial using live target markets and actual internal workflows.

    Output Accuracy: 8/10

    A score of 8 recognizes a credible verification process while separating verified records from inherently uncertain forward looking fields. Contact identities, documents, reported stages, and observed project events can be researched and checked. Estimated construction values, anticipated schedules, procurement dates, and future participants are more fluid, particularly early in planning. Forecasts and market outlooks are analytical products, not guaranteed outcomes. BestCRE analysis: Dodge appears suitable for prioritization and market monitoring, but important investment or bidding decisions still require confirmation with owners, municipalities, design teams, or contractors. The vendor does not publish a comprehensive accuracy audit, field level confidence score, or standardized correction rate. Buyers should sample known completed, delayed, canceled, and confidential projects to see how the system represents uncertainty. The score is high because human verification supports dependable output, but it acknowledges that construction intelligence cannot eliminate changes occurring after a record is reviewed.

    Integration and Workflow Fit: 8/10

    A score of 8 reflects several practical delivery paths. Dodge identifies direct connections for Salesforce, HubSpot, and Microsoft Dynamics, alongside a REST interface, data feeds, custom exports, web access, and mobile access. That range can serve both a business development team working inside a CRM and an analytics group building internal territory or supply dashboards. BestCRE analysis: integration value will depend on contract rights, field mapping, identifiers, refresh frequency, duplicate handling, and access to historical changes. Those implementation details are not sufficiently public to assume a turnkey deployment. Buyers should request sample payloads and test how project companies and contacts match their existing records. Dodge does not publicly present native connections to every common CRE underwriting, property management, or development accounting system. Even so, the available CRM and data delivery options place it above products that confine users to a standalone interface.

    Pricing Transparency: 3/10

    A score of 3 reflects the absence of public subscription prices, standard package costs, user limits, data fees, or implementation charges. Prospective customers are directed toward a demo and sales conversation. That may accommodate different territories and data needs, but it makes early comparison and budgeting unnecessarily difficult. Buyers cannot determine from public information whether mobile access, CRM delivery, forecasts, archived documents, exports, or programmatic access require separate contracts. BestCRE analysis: opacity also makes it harder to compare Dodge with narrower alternatives whose scope may be easier to price. A serious evaluation should require a written breakdown of license units, geography, modules, seats, onboarding, renewals, usage restrictions, and any charges for additional data delivery. The score is below average because a buyer must engage sales before establishing even a realistic cost range, not because the eventual price is necessarily unreasonable.

    Support and Reliability: 7/10

    A score of 7 reflects the vendor’s visible sales contact channel, research organization, specialist products, and consulting capabilities, but public support terms remain limited. Dodge publishes a telephone contact and offers demonstrations, expert research, and advisory engagements. A company serving multiple construction audiences should have substantial domain knowledge available, yet the public site does not establish standard response times, service levels, customer success staffing, after hours availability, or escalation procedures. BestCRE analysis: support quality will likely vary by product, contract, and account scope. Buyers should ask who handles data corrections, CRM mapping, training, search design, and technical incidents, then put response expectations into the agreement. References from customers with similar territories and workflows would be more informative than general testimonials. The score recognizes evidence of organizational depth while withholding a higher rating until service commitments and customer outcomes can be evaluated more transparently.

    Innovation and Roadmap: 7/10

    A score of 7 reflects continued modernization of an established dataset through Dodge One, mobile access, automated monitoring, analytics, CRM delivery, and AI assisted search. The product direction addresses a real problem: converting a large construction database into timely, searchable signals that can travel into daily workflows. The innovation is mainly in distribution, synthesis, and usability rather than in creating an entirely new category. BestCRE analysis: this is sensible product development because construction teams benefit more from dependable information and efficient routing than from novelty alone. However, public information does not provide enough technical detail to judge model architecture, evaluation methods, explainability, or safeguards for AI generated responses. Buyers should test whether AI search preserves filters, cites underlying records, distinguishes facts from inferences, and produces repeatable results. Dodge earns an above average score, but newer interface features should be judged against measurable research time saved and opportunities identified.

    Market Reputation: 9/10

    A score of 9 reflects Dodge’s long standing role in North American construction information and the breadth of its recognized data products. The company traces its construction reporting history back more than a century and states that the United States Census Bureau relies on its information. Its market indexes and construction starts analysis are commonly referenced in industry reporting, reinforcing credibility beyond lead generation. BestCRE analysis: that institutional standing lowers vendor maturity risk and supports confidence that the dataset will remain relevant to industry participants. Reputation does not remove the need to test local coverage, product usability, contract terms, or customer service. It also should not cause a buyer to assume that a legacy data position automatically produces the best workflow for every specialist use case. The score is near the top of the framework because few construction intelligence providers match Dodge’s history and market recognition, while retaining room for independent validation of current customer experience.

    9AI Score Card Dodge Construction Network
    72
    72 / 100
    Solid Platform
    Construction Intelligence
    Dodge Construction Network
    Dodge gives construction and development teams early project signals, verified contacts, bidding context, market forecasts, and access through mobile, CRM, and data feeds.
    9 Dimensions, Scored 1 to 10
    1. CRE Relevance
    7/10
    2. Data Quality & Sources
    9/10
    3. Ease of Adoption
    7/10
    4. Output Accuracy
    8/10
    5. Integration & Workflow Fit
    8/10
    6. Pricing Transparency
    3/10
    7. Support & Reliability
    7/10
    8. Innovation & Roadmap
    7/10
    9. Market Reputation
    9/10
    BestCRE.com, 9AI Framework v2 Reviewed October 2026

    Who Should Use Dodge Construction Network

    Dodge should be considered by developers, vertically integrated owners, construction managers, and general contractors that repeatedly evaluate planned commercial projects across multiple markets. It is particularly relevant when a team needs to see projects before formal bidding, track changes in stage or participants, identify architects and contractors, or monitor future competitive supply. Building product manufacturers and subcontractors also fit the platform’s core audience because specifications, relationships, and bid timing can guide account selection. A CRE research group may find the historical starts and forecasting products useful for market sizing and development strategy.

    The best buyer has a defined territory, a repeatable qualification process, and a CRM or internal data environment capable of turning records into assigned action. BestCRE analysis: value should be measured through qualified opportunities found earlier, research hours avoided, useful contacts added, and decisions improved, not through raw lead volume. Before purchase, the buyer should supply a sample of known projects and ask Dodge to demonstrate discovery timing, update history, document access, participant accuracy, and export behavior. Teams with recurring construction exposure and dedicated ownership of the workflow are more likely to capture value than occasional users searching for isolated projects.

    Who Should Not Use Dodge Construction Network

    Dodge is a weak primary purchase for owners focused almost entirely on stabilized acquisitions, leasing, property management, tenant engagement, or loan servicing. Those teams need property financials, ownership, rents, leases, transactions, operating benchmarks, or debt information that construction project intelligence does not replace. A small operator working in one narrow area may also struggle to justify a broad platform if municipal records, broker relationships, and occasional contractor outreach already cover its needs.

    It may also be unsuitable for teams seeking a complete development management system. Dodge can help identify and monitor projects, but it does not publicly position itself as the system of record for budgets, schedules, change orders, draws, contracts, or asset operations. BestCRE analysis: buyers who lack a lead qualification process should fix that operating gap before adding another source. Firms requiring transparent self service pricing, a short month to month commitment, or fully disclosed interface specifications may find the sales process restrictive. A paid pilot or limited territory test is preferable when expected usage is uncertain.

    Pricing and ROI Analysis

    Dodge Construction Network does not publish standard pricing for Dodge One or a complete public price list for its wider portfolio. It also does not publicly specify how charges vary by user count, geography, project type, module, document access, CRM connection, data feed, or application programming interface usage. A buyer should request an itemized proposal showing subscription length, included seats, covered markets, export rights, onboarding, support, renewal terms, and optional products. The contract should also clarify data retention and permitted use after cancellation.

    BestCRE analysis: simple return math should begin with the fully loaded annual cost, then divide it by the gross profit expected from one qualified win or the value of analyst time saved. For example, if a subscription and implementation cost C, annual research savings equal H hours multiplied by the team’s loaded hourly cost R. The buyer’s break even contribution from new opportunities is C minus H times R. If that result is positive, divide it by the expected contribution per converted project to estimate the required wins. Use conservative conversion assumptions, exclude unqualified lead volume, and compare results with a manual research baseline during a pilot.

    Integration and CRE Tech Stack Fit

    Dodge can fit into a CRE technology stack as an upstream construction intelligence source. Salesforce, HubSpot, and Microsoft Dynamics connections support teams that qualify and manage relationships in a customer relationship system. Data feeds, custom exports, and programmatic access can support development pipeline dashboards, market research environments, and competitive supply models. Mobile access is useful for field teams that need to check records or alerts away from an office.

    The missing piece is detailed public implementation information. Buyers should confirm available objects, unique identifiers, refresh schedules, history, attachments, contact permissions, field definitions, and write back behavior. BestCRE analysis: a successful deployment should keep Dodge as the source for construction observations while the CRM or development system remains the source for internal decisions and ownership. Data teams must also plan entity matching because project names, addresses, companies, and contacts rarely align perfectly across systems. Native connections to major property management and underwriting platforms are not publicly listed, so those workflows may require exports or custom engineering.

    Competitive Landscape

    Mercator.ai is a relevant alternative for contractors seeking early project signals and relationship intelligence, with a more focused modern prospecting experience. Shovels.ai is better aligned with teams that want permit centered data and developer or contractor activity analysis. Datagrid takes a different approach, using AI agents to collect, transform, and move information across workflows rather than supplying Dodge’s long established national construction corpus. Buyers should compare these products on the actual job being purchased, because their labels can obscure major differences in source data and operating model.

    Within the wider CRE Construction and Development category, ALICE Technologies is oriented toward construction scheduling and scenario optimization, while OpenSpace focuses on visual documentation and site capture. Field Materials addresses purchasing and material workflows. Civils.ai and LandScout AI are more relevant to site assessment, planning, and early development analysis. None is a direct replacement for all of Dodge’s project, bidding, relationship, specification, and market intelligence functions.

    BestCRE analysis: choose Dodge when breadth of construction coverage, historical context, human verification, and several delivery methods matter more than a narrowly designed point workflow. Choose a specialist when the core problem is permit analytics, site diligence, schedule optimization, field documentation, or procurement execution. A disciplined selection process should test the same markets and known projects in Dodge, Mercator.ai, Shovels.ai, and any internal research method, then compare discovery timing, usable contacts, false positives, workflow effort, contract restrictions, and total cost.

    The Bottom Line

    Dodge Construction Network is a strong candidate for organizations whose revenue or investment decisions depend on seeing commercial construction activity early and understanding the people attached to it. Its established dataset, human verification, historical context, mobile access, and delivery options justify a serious evaluation. It is most compelling for development and construction teams with repeatable territories and a clear process for acting on new information.

    BestCRE analysis: buy only after a market specific validation and a fully itemized proposal. Require Dodge to demonstrate records your team already knows, including delayed or canceled projects, and measure when each useful fact became available. Confirm integration rights and module boundaries in writing. If the test produces earlier qualified opportunities or meaningful research savings, Dodge can become valuable infrastructure. If the need is primarily underwriting, property operations, or occasional local lead discovery, select a narrower CRE product or retain the existing research process.

    About BestCRE

    BestCRE.com is the definitive authority on commercial real estate AI, analysis, and investment intelligence. Every article advances the platform’s mission to help CRE professionals identify, evaluate, and adopt the best tools and strategies in the industry. We benchmark platforms using the 9AI Framework so CRE leaders can compare tools with clear evidence. Explore the category map at 20 CRE sectors for deeper coverage across the CRE stack.

    Frequently Asked Questions

    What is Dodge Construction Network?

    Dodge Construction Network is a construction intelligence company serving contractors, subcontractors, developers, architects, building product firms, and related service providers. Its products provide information about planned and active commercial construction, including project stage, location, participants, specifications, documents, bid activity, market trends, and forecasts. Dodge One is its primary modern project intelligence experience, with web and mobile access. Other products address subcontractor discovery, bid invitations, specifications, public projects, and market analysis. For CRE buyers, Dodge is most useful in development, construction, competitive supply monitoring, and relationship sourcing. It is not a replacement for property underwriting, leasing, asset management, project accounting, or building operations software.

    How does Dodge Construction Network compare with other construction data platforms?

    Dodge distinguishes itself through an established national construction dataset, human research, historical starts information, project documents, participant records, and several delivery methods. Mercator.ai emphasizes early opportunity and relationship discovery for construction sales teams. Shovels.ai centers more heavily on building permit data and contractor or developer activity. Datagrid uses AI agents to assemble and process information across business workflows. BestCRE analysis: Dodge is the stronger candidate when a buyer wants broad construction intelligence and historical context from one established provider. A specialist may be preferable when the requirement is narrowly defined around permits, automated research, site assessment, scheduling, or field execution. Buyers should compare the same known projects and measure discovery timing, contact usefulness, update quality, workflow effort, and contract cost.

    How much does Dodge Construction Network cost?

    Dodge Construction Network does not publish standard subscription prices or a complete public rate card. Public information does not establish the cost per user, territory, module, data feed, CRM connection, export, or programmatic request. Buyers must contact the company for a demonstration and proposal. Request a written breakdown covering included products, seats, geography, project types, document access, implementation, training, support, renewal increases, usage limits, and data rights. BestCRE analysis: compare the total annual commitment with research labor saved and contribution from opportunities that the team can document as discovered or acted upon earlier. A limited territory pilot is preferable when possible. Pricing should be evaluated against usable qualified records, not the total number of projects available in the platform.

    Who should use Dodge Construction Network?

    Dodge is best suited to general contractors, subcontractors, building product firms, developers, and vertically integrated CRE owners with recurring construction activity. It can also support market research teams monitoring planned supply, project starts, active developers, design firms, and contractors. The strongest user has a defined geography, clear project criteria, assigned responsibility for reviewing alerts, and a customer relationship or development system for recording action. It is less suitable as a primary platform for stabilized property investors, leasing teams, property managers, or lenders whose daily work depends on rents, tenants, transactions, operating statements, or debt performance. BestCRE analysis: an organization should buy Dodge when early construction visibility repeatedly affects revenue or capital decisions, not merely because it wants a large lead database.

    Will Dodge One become more useful for CRE teams?

    Dodge One has the ingredients to become more useful to CRE teams as search, mobile delivery, analytics, and system connections improve. The largest opportunity is not simply adding more records. It is helping users distinguish confirmed facts from estimates, understand why a project changed, match entities across systems, and route timely signals into investment or development decisions. AI assisted search could reduce research time if answers remain traceable to project records and filters behave consistently. BestCRE analysis: future value will depend on field level transparency, measurable data freshness, integration detail, and clearer packaging. Buyers should evaluate current capabilities rather than purchasing on a roadmap. Contract reviews should establish what is available now, which enhancements are committed, and whether future data or interface access will carry additional fees.

    Related Reviews

    Compare Dodge Construction Network with other tools BestCRE has scored in the same category: Civils.ai, Field Materials, Attentive.ai. Explore more CRE AI tool reviews in our Best CRE AI Tools directory. For sector-specific analysis and market intelligence, visit our 20 CRE Sectors hub.
  • Buxton Review: Customer analytics for physical location decisions

    Buxton Review: Customer analytics for physical location decisions

    BestCRE 9AI Score

    72/100 · Contender

    Buxton ranks #202 of 388 commercial real estate AI tools scored on the 9AI Framework. Nine dimensions, each scored out of 10: CRE relevance, data quality, ease of adoption, output accuracy, integration fit, pricing transparency, support, innovation and market reputation.

    Buxton is a location intelligence and customer analytics provider used by retailers, restaurant chains, healthcare organizations, landlords, franchise systems and economic development teams. Its central role in a commercial real estate workflow is to turn customer, competitive and geographic data into decisions about markets, trade areas and individual sites. For a real estate planner, the practical question is not simply whether an intersection looks attractive. It is whether the surrounding consumers fit the brand, whether demand is already served and whether the proposed location can achieve an acceptable level of performance.

    The company has operated from Fort Worth, Texas, since 1994 and is now part of Audiense. Its location intelligence offering is presented as Audiense In-Person, powered by Buxton, while SCOUT remains the web-based platform used for market planning, whitespace analysis, site scoring and geographic reporting. That history matters because location models improve through repeated exposure to store networks, customer files and realized performance. It does not, however, remove the need for buyers to test model assumptions against their own portfolio.

    Buxton is CRE-adjacent rather than a complete property intelligence system. It can influence where a tenant opens, relocates or invests, but it is not primarily designed for lease administration, underwriting, property accounting, transaction management or construction. Its strongest users are occupiers and advisers making network decisions. Landlords can also use its trade area and consumer analysis to assess tenant fit, merchandising plans and leasing narratives, although they may need separate systems for property and deal data.

    BestCRE analysis: Buxton earns consideration when a location decision depends on identifying the right customers rather than merely finding available space. Its combination of customer profiling, market capacity analysis, site scoring and performance optimization is deeper than a basic mapping subscription. The main buying risks are limited public pricing, dependence on model configuration and an integration story that must be verified during diligence. A buyer should run a paid or controlled validation using known locations before treating any forecast as investment evidence.

    What Buxton Does and How It Works

    SCOUT organizes Buxton’s location analysis around planning, scoring, visualization and optimization. A team can map existing and proposed locations, define or inspect trade areas, compare consumer concentrations, identify competitors and evaluate visitation patterns. Market optimization analysis is intended to estimate how many locations a market may support and where whitespace remains. Scenario tools let planners compare different expansion approaches, territory configurations or levels of market penetration before directing brokers toward specific search areas.

    At the site level, Buxton combines characteristics of nearby consumers, competitors and local conditions into scoring and forecasting workflows. Customer analytics can begin with a brand’s own customer records, from which Buxton develops profiles of high-value or otherwise relevant audiences. Teams can then look for similar households in other markets and compare candidate sites according to audience fit. Where first-party data is limited, industry profiles and location visitor insights can provide another starting point. The result is a decision aid, not a substitute for lease economics, access analysis, physical due diligence or local operating judgment.

    The optimization workflow extends beyond new openings. Users can compare observed sales with forecast potential, identify locations that appear to underperform and direct marketing or operational attention accordingly. Foot traffic trends can add context to changes in visitation, while reporting and maps help communicate conclusions to real estate committees and field teams. Buxton publicly describes a no-code, cloud-based and mobile-friendly setup. BestCRE analysis: those characteristics should make routine exploration approachable, but the difficult work sits upstream in matching customer identities, defining outcomes, choosing variables and validating forecasts. Buyers should establish who controls model definitions, how frequently data refreshes and whether scores remain comparable after methodology changes.

    9AI Framework: Dimension by Dimension Analysis

    CRE Relevance: 8/10

    Buxton scores 8 for CRE relevance because its analysis directly informs market entry, site selection, relocation, network optimization and tenant strategy. These are consequential real estate decisions, especially for retail, restaurants, healthcare and other location-dependent operators. SCOUT can help a real estate team narrow markets, compare trade areas and rank candidate locations before committing brokerage and diligence resources. The deduction reflects product scope. Buxton does not replace underwriting, lease management, property accounting, transaction coordination or building operations software. Its primary object is the consumer and the physical network, not the property record or lease. BestCRE analysis: occupiers will find a more direct CRE fit than investment managers or property operators. Landlords can use the platform for tenant and merchandising questions, but will need other sources for ownership, availability, rents, expenses and transaction evidence.

    Data Quality and Sources: 9/10

    Buxton scores 9 for data quality because the offering combines customer analytics, consumer profiles, competitive context, visitation information and geographic analysis in a mature location planning discipline. The company publicly states that its platform draws on more than 50 data sources and offers household-level insight. It also reports third-party attestation for SOC 2 Type II and HITRUST standards, which is relevant when customer records or sensitive business information enter the workflow. Data breadth does not guarantee fitness for every concept or geography. BestCRE analysis: buyers should request source-level documentation covering provenance, update frequency, geographic coverage, identity resolution and permitted uses. They should also test whether rural areas, emerging districts and recently developed locations receive comparable coverage. First-party customer data quality will materially influence the usefulness of any custom profile, so duplicate records, incomplete addresses and inconsistent transaction histories need attention before modeling.

    Ease of Adoption: 8/10

    Buxton scores 8 for ease of adoption. SCOUT is publicly described as a cloud-based, mobile-friendly platform with no-code setup, and its core actions map closely to familiar real estate questions: where to grow, how to compare sites and which existing locations need attention. Maps, reports and location scores can be easier for an investment committee to consume than raw demographic files. Adoption becomes more demanding when a buyer wants custom customer profiles, sales forecasts or portfolio-wide optimization. Those workflows require clean internal data, agreed performance definitions and disciplined interpretation. BestCRE analysis: the interface may reduce technical friction, but organizational friction remains. Real estate, marketing, operations and finance must agree on what a good location means. A pilot should therefore include actual end users, known winners and known misses, plus a repeatable approval process for exceptions when field evidence conflicts with the model.

    Output Accuracy: 8/10

    Buxton scores 8 for output accuracy because its approach is designed around brand-specific customer patterns, trade area conditions and observed location performance rather than generic demographic ranking alone. That can produce more decision-relevant results for established chains with sufficient operating history. No public evidence supports treating every site score or sales forecast as universally accurate, and the vendor does not publish a single accuracy rate applicable across clients. Performance will vary with concept maturity, input quality, market volatility, site novelty and the selected outcome variable. BestCRE analysis: buyers should measure accuracy with a holdout test. Exclude a group of existing locations from model training, generate predictions without revealing their results and compare forecasts with realized performance. Review error by market type, format and opening cohort, not just in aggregate. A useful model should also identify uncertainty and explain major drivers rather than presenting a precise number without context.

    Integration and Workflow Fit: 6/10

    Buxton scores 6 for integration. The offering is positioned as a web-based analysis environment, and Audiense also promotes data services for placing its intelligence into customer systems and workflows. However, detailed public documentation for packaged connectors, supported CRE platforms, API scope, export formats, implementation timing and associated fees is limited. That creates diligence work for a buyer expecting automated movement of property, customer, sales or campaign data. BestCRE analysis: basic map and report use should require less integration than custom forecasting or closed-loop performance measurement. Buyers should diagram each required flow, including point-of-sale data, CRM records, property candidates, lease facts and approved site scores. They should then ask which flows are native, which require services and which rely on file transfer. The platform should be tested with the buyer’s actual identifiers because matching stores, customers and geographies often causes more difficulty than displaying the resulting analysis.

    Pricing Transparency: 3/10

    Buxton scores 3 for pricing transparency because the vendor does not publish standard subscription prices, implementation fees, data charges or contract terms. Prospects are directed toward a demo or information request, suggesting that scope and pricing are developed through a sales process. Customization may justify tailored quotes, particularly when models, customer records and portfolio sizes differ, but buyers cannot independently estimate ownership cost from public information. BestCRE analysis: procurement should request an itemized proposal separating software access, datasets, model development, implementation, training, support and future refreshes. It should also clarify user limits, geographic limits, exports, API access, renewal increases and charges for additional concepts or brands. Without those details, a seemingly comparable quote can conceal materially different rights and deliverables. The low score reflects opacity, not necessarily poor value. Value can only be judged after the buyer defines the decisions, users and data required.

    Support and Reliability: 7/10

    Buxton scores 7 for support. Its work naturally involves more than software access because customer profiling, model design and forecast interpretation require domain knowledge. The company’s long operating history and emphasis on analytics suggest an established client service capability, but public information does not provide enough detail to compare service levels, response commitments, onboarding timelines or named account coverage across packages. BestCRE analysis: support quality will matter most during model construction and when results challenge internal expectations. Buyers should identify who will explain variables, document methodology, resolve data discrepancies and retrain users after staff changes. Contract diligence should establish support hours, escalation paths, scheduled business reviews and turnaround expectations for refreshed models. References should come from organizations with a similar number of locations, data maturity and decision cadence. A polished demonstration is not evidence that routine questions, model revisions and executive requests will receive the same attention after implementation.

    Innovation and Roadmap: 7/10

    Buxton scores 7 for innovation. Its differentiated strength is not a newly introduced interface feature, but the sustained application of customer analytics to physical network decisions. The combination of audience profiling, location scoring, market capacity analysis, visitation context and existing-store optimization creates a useful bridge between marketing intelligence and real estate planning. Becoming part of Audiense may broaden the connection between in-person behavior, online audiences and campaign analysis. BestCRE analysis: that potential is meaningful, but buyers should separate available functionality from future product direction. The underlying concepts of geographic information systems, trade area analysis, lookalike audiences and predictive site selection are established. Innovation should therefore be judged by model adaptability, explainability, workflow speed and the ability to combine first-party and external information responsibly. Buxton appears advanced within its specialty, yet it is not enough to award a higher score without clearer public evidence of differentiated automation or measurable gains.

    Market Reputation: 9/10

    Buxton scores 9 for market reputation. It has operated since 1994 and is associated with location planning for retail, restaurants, hospitality and healthcare, giving it a longer track record than many newer analytics vendors. The company positions its work around national brands and complex physical networks, and its inclusion within Audiense expands the corporate context surrounding the product. The vendor does not publish all customer relationships, retention measures or independently standardized performance results, so reputation should not substitute for reference checks. BestCRE analysis: longevity is particularly valuable in site selection because the provider has had time to encounter multiple formats, economic cycles and network strategies. Buyers should still speak with current clients whose concepts resemble their own and ask how recommendations performed after opening. They should also examine whether the individuals and methods responsible for earlier successes remain available within the current Audiense structure.

    9AI Score Card Buxton
    72
    72 / 100
    Solid Platform
    Location Intelligence
    Buxton
    Buxton helps chains and property teams rank markets, score sites, map trade areas and compare forecast potential against actual location performance.
    9 Dimensions, Scored 1 to 10
    1. CRE Relevance
    8/10
    2. Data Quality & Sources
    9/10
    3. Ease of Adoption
    8/10
    4. Output Accuracy
    8/10
    5. Integration & Workflow Fit
    6/10
    6. Pricing Transparency
    3/10
    7. Support & Reliability
    7/10
    8. Innovation & Roadmap
    7/10
    9. Market Reputation
    9/10
    BestCRE.com, 9AI Framework v2 Reviewed October 2026

    Who Should Use Buxton

    Buxton best suits multi-location retailers, restaurant groups, healthcare networks, hospitality operators and franchise systems that have enough operating data to distinguish strong locations from weak ones. The ideal buyer has a recurring site pipeline, a customer or transaction file and an internal team responsible for market planning. For these organizations, a repeatable scoring process can focus broker searches, create consistent committee materials and reduce decisions based solely on intuition. The platform is especially relevant when customer fit varies meaningfully between neighborhoods that appear similar on conventional demographic reports.

    Landlords, brokers and economic development organizations should consider Buxton when their work requires consumer demand analysis rather than property facts alone. A landlord may use it to evaluate which concepts fit a center or where a tenant could expand. An adviser may use it to test market strategy before assembling candidate sites. Economic developers may use location and audience evidence to frame recruitment conversations. BestCRE analysis: these users should confirm that the available outputs match their rights and responsibilities. An occupier with first-party performance data can usually build a more specific model than an outside party relying on general profiles and visitation estimates.

    Who Should Not Use Buxton

    Buxton is a poor fit for buyers seeking an all-purpose commercial property database or transaction platform. It is not the primary system for ownership research, comparable sales, rent surveys, lease abstracts, debt analysis, pipeline management or property operations. Investment sales brokers, lenders and institutional acquisition teams may find parts of the location analysis useful, but they will still need property-level financial and market evidence elsewhere. A small operator considering one location may also struggle to justify a specialized platform and custom analysis.

    Teams without clean customer, sales or store data should not assume that software alone will resolve weak decision processes. General profiles can support exploration, but a brand-specific model needs dependable inputs and a sufficient performance history. Buyers requiring transparent self-service pricing or extensive public API documentation may find the procurement process frustrating. BestCRE analysis: if the organization cannot name the decision owner, define a successful location or commit to testing predictions, it should first improve governance and data readiness before purchasing.

    Pricing and ROI Analysis

    Buxton does not publish standard prices for SCOUT, analytics services, implementation or ongoing model work. Public materials direct buyers to request a demonstration or more information. The final cost may depend on portfolio scale, users, geography, data requirements, customer matching, custom models and service scope, but the vendor does not publish a rate card explaining those variables. Buyers should require a multiyear cost schedule that identifies subscription fees, implementation, data licensing, model refreshes, support, exports and integration. Renewal terms and rights to retain outputs after termination should also be explicit.

    BestCRE analysis: simple ROI math should begin with avoidable decision cost, not an unsupported promise of forecast improvement. Suppose a team evaluates 40 candidate sites annually and its fully loaded internal and external diligence cost is $7,500 per site. If better market screening removes eight weak candidates before full diligence, the gross avoided cost is $60,000. Subtract the quoted annual platform and service cost, plus internal implementation labor, to estimate first-year return. This example is analysis, not a Buxton claim or published price. Buyers should run a second case based on one avoided poor opening, using their own lease obligations, buildout exposure and closure costs.

    Integration and CRE Tech Stack Fit

    Buxton can sit between customer systems and the real estate decision process. Likely inputs include customer addresses, transaction histories, store performance, candidate locations and operational attributes. Useful outputs include maps, market priorities, site scores, trade area reports and location performance comparisons. Those outputs can inform broker assignments, site approval packages and portfolio reviews, but Buxton is not presented as the system of record for leases, properties or transactions.

    Public information does not fully specify packaged connectors to common CRE platforms, CRM systems, data warehouses or geographic tools. Audiense offers data services, but buyers should confirm available APIs, file formats, authentication, refresh schedules and implementation responsibility. BestCRE analysis: integration should be treated as a defined workstream whenever custom modeling is involved. Establish a shared location identifier, document geographic definitions and test exports before contract signing. If the intended workflow depends on automated writeback to another system, require a technical demonstration rather than relying on a general statement about data availability.

    Competitive Landscape

    Placer.ai is the clearest alternative for teams that place heavy weight on visitation patterns, trade areas and competitive movement. It often enters the conversation when landlords, retailers and brokers want accessible location activity analysis across many properties. Buxton is more naturally framed around customer profiles, brand-specific site selection and network planning. BestCRE analysis: compare them using the same markets and known stores, then judge which product better explains performance and supports the actual approval workflow.

    SiteZeus competes more directly in predictive site selection and expansion planning, with an emphasis on mapping, sales forecasting and collaborative workflows. Locate.ai is another relevant option for retailers and restaurant operators seeking technology-assisted market and site decisions. GrowthFactor should be considered where the buyer wants retail growth planning and location strategy support. Each vendor differs in model configuration, data access, service intensity and interface design, so a feature checklist alone will not reveal the best fit.

    Buxton’s strongest competitive argument is its long experience applying consumer analytics to location networks. Its weakest point in a comparison is the limited ability to assess price and integration scope before engaging sales. A disciplined selection should use historical holdout locations, include both strong and weak performers and score vendors on forecast error, explanation quality, workflow fit and total cost. Buyers should also verify whether they receive model documentation and portable outputs.

    The Bottom Line

    Buxton should make the shortlist for established location-based operators that need a defensible process for market prioritization, customer fit and site scoring. It is particularly credible for chains with first-party customer and performance data, repeated expansion decisions and enough downside exposure to justify custom analysis. Do not buy it as a substitute for property underwriting or local fieldwork. Buy it to make those activities more focused and consistent.

    BestCRE analysis: proceed only after a controlled validation and a fully itemized commercial proposal. Require Buxton to score withheld locations, explain the principal drivers and show how results enter the existing approval process. If the model distinguishes known winners from misses and the avoided diligence or location risk exceeds total cost, the platform merits adoption. If outputs remain generic, poorly explained or difficult to transfer into other systems, choose a lighter location analytics product.

    About BestCRE

    BestCRE.com is the definitive authority on commercial real estate AI, analysis, and investment intelligence. Every article advances the platform’s mission to help CRE professionals identify, evaluate, and adopt the best tools and strategies in the industry. We benchmark platforms using the 9AI Framework so CRE leaders can compare tools with clear evidence. Explore the category map at 20 CRE sectors for deeper coverage across the CRE stack.

    Frequently Asked Questions

    What is Buxton location intelligence?

    Buxton is a customer analytics and location intelligence provider for organizations operating physical locations. Its SCOUT platform supports market planning, whitespace analysis, trade area evaluation, site scoring, mapping and performance optimization. Retailers, restaurants, healthcare networks, hospitality groups, franchise systems, landlords and economic development teams can use it to examine where relevant consumers live, which locations they visit and how candidate sites compare. Buxton has operated since 1994 and is now part of Audiense, where the offering is presented as Audiense In-Person, powered by Buxton. It is CRE-adjacent rather than a full property platform. It informs location and network decisions but does not replace lease administration, property accounting, transaction management, construction systems or conventional investment underwriting.

    How does Buxton compare with Placer.ai for site selection?

    Buxton and Placer.ai overlap in trade area, visitation and location analysis, but their centers of gravity differ. Buxton is strongly oriented toward customer profiling, brand-specific site scoring, market capacity and physical network optimization. Placer.ai is commonly evaluated for broad visitation intelligence, location trends and competitive movement across properties and brands. BestCRE analysis: an occupier with meaningful first-party customer and sales data may prefer Buxton’s custom planning orientation, while a landlord or broker seeking quick comparative visitation analysis may favor Placer.ai. The right test is a historical holdout exercise using the same locations. Compare forecast error, driver explanations, geographic coverage, workflow speed, integration requirements and total contract cost rather than relying on demonstration sites selected by either vendor.

    How much does Buxton cost?

    Buxton does not publish standard pricing for SCOUT, customer analytics, custom models, implementation or ongoing services. Prospective buyers must contact the company for a demonstration and proposal. A useful quote should separate software access, included users, geographic coverage, licensed datasets, customer matching, model development, implementation, training, support, refreshes, exports and any API work. Buyers should also ask about contract length, renewal increases, fees for additional brands and rights to retain reports or model outputs after termination. BestCRE analysis: judge the quote against measurable decision costs. Estimate avoided diligence on rejected candidates, staff time saved and the financial exposure of a poor location, then subtract the complete first-year and recurring cost. Do not calculate return from vendor projections that have not been validated on your portfolio.

    Who should use Buxton?

    Buxton is best suited to multi-location retailers, restaurant groups, healthcare systems, hospitality operators and franchise networks that make recurring market and site decisions. The strongest buyer has clean customer or transaction data, a history of location performance and a real estate team that needs consistent market ranking and site approval. Landlords can also use consumer and visitation analysis to assess tenant fit, while brokers and economic developers may use it to support market strategy and recruitment. It is less suitable for a small operator evaluating a single site or for teams seeking ownership records, comparable sales, rent data, lease administration or property accounting. BestCRE analysis: the organization should have enough decision volume and financial exposure to justify structured modeling, validation and ongoing data management.

    What should buyers expect from Buxton after its move into Audiense?

    Buxton is now positioned within Audiense as the in-person component of a broader consumer intelligence offering. The strategic opportunity is a closer connection between physical visitation, customer profiles, online audience behavior and marketing analysis. Public information does not establish exactly which future integrations, shared datasets or product changes will be delivered, so buyers should not contract based on an assumed roadmap. BestCRE analysis: ask for a written distinction between functionality available today, contracted implementation work and planned development. Buyers should also confirm the future identity of SCOUT, continuity of existing models, data governance, account support and any changes to licensing. The combination could make location decisions more connected to marketing and customer strategy, but its practical value will depend on delivered workflows and clear responsibility across the combined product organization.

    Related Reviews

    Compare Buxton with other tools BestCRE has scored in the same category: Matterport, Cotality, HelloData. Explore more CRE AI tool reviews in our Best CRE AI Tools directory. For sector-specific analysis and market intelligence, visit our 20 CRE Sectors hub.
  • Regrid Review: Standardized parcel data for property and location decisions

    Regrid Review: Standardized parcel data for property and location decisions

    BestCRE 9AI Score

    78/100 · Contender

    Regrid ranks #116 of 387 commercial real estate AI tools scored on the 9AI Framework. Nine dimensions, each scored out of 10: CRE relevance, data quality, ease of adoption, output accuracy, integration fit, pricing transparency, support, innovation and market reputation.

    Regrid is a parcel data and location intelligence company used by developers, site selectors, land teams, analysts and GIS professionals. Its core job is to replace fragmented county records with a standardized parcel layer that can support site screening, ownership research, mapping and application development. For a commercial real estate team, the practical change is straightforward: analysts can begin with a consistent national parcel foundation instead of finding, cleaning and joining local files market by market.

    The platform is most relevant when parcel geometry is central to the decision. A development team can examine boundaries, ownership information, building footprints, addresses, zoning fields and surrounding geography before advancing a site. A data team can purchase county or state files, connect an API, consume map tiles or use an Esri Feature Service. The Property App gives less technical users a map interface for searching, saving places and recording field observations.

    Regrid is CRE adjacent rather than a complete commercial property intelligence system. It provides the geographic and cadastral foundation beneath many real estate workflows, but it is not primarily a sales comparable database, leasing platform, underwriting model or transaction marketplace. Buyers should expect to combine it with internal records and specialist sources for rents, operating statements, debt, tenants, ownership entities and verified zoning conclusions.

    BestCRE’s analysis is that Regrid earns consideration because its product design addresses two persistent parcel data problems: inconsistent local schemas and difficult delivery. Complete United States coverage, county level purchasing, matched spatial layers and direct ArcGIS access make the platform unusually practical for organizations that operate across jurisdictions. The limitation is equally important. Government sourced parcel records vary in timing and completeness, so standardization does not eliminate source limitations. Regrid should accelerate research and system building, not replace title work, surveys, legal zoning review or direct verification with public authorities.

    What Regrid Does and How It Works

    Regrid collects parcel boundaries and associated public record information, then converts the source material into a common schema. Users can inspect coverage by county, including refresh information and field availability, before deciding whether a market is suitable for a particular analysis. Available enrichments include ownership details, matched building footprints, secondary addresses, standardized zoning and demographic or geographic context. Because field availability depends on underlying sources and selected products, buyers should test the exact counties and attributes that matter rather than treating national coverage as uniform completeness.

    Delivery options span both individual research and production data infrastructure. The Property App provides desktop and mobile parcel lookup, boundary viewing, saved places, notes and photos. The Data Store supports self service purchases by county or state, with selectable formats and add ons. Larger teams can receive bulk files for recurring workflows. Developers can use parcel APIs and tiles to place data inside applications, pipelines or internal search tools. Regrid also offers an MCP server for conversational access by compatible AI clients, although buyers should treat that interface as another query method, not evidence that source records have become more authoritative.

    For Esri environments, Regrid offers a hosted Feature Service that connects parcel layers to ArcGIS Pro, ArcGIS Online and supported Esri applications. This can reduce the storage, loading and maintenance work associated with large static files. In a typical CRE workflow, a site selector might identify candidate parcels, join internal criteria, examine buildings and access, then export qualified locations for deeper diligence. A developer might query parcels around infrastructure, filter on acreage or ownership attributes, and pass results into an acquisition pipeline. The important control is validation: parcel boundaries are useful analytical representations, but they are not surveys, and ownership, zoning or address fields can be delayed, incomplete or interpreted differently across jurisdictions.

    9AI Framework: Dimension by Dimension Analysis

    CRE Relevance: 8/10

    Score: 8. Regrid addresses parcel level questions that appear early in development, acquisition, site selection, infrastructure planning and land research. Boundaries, ownership fields, addresses, buildings and zoning context can materially shorten the first pass through a market. Its national standardization is particularly valuable to portfolios crossing many counties. The score stops below the top tier because Regrid is not an end to end CRE intelligence system. It does not, by itself, supply the complete rent, tenancy, transaction, debt and operating information required for investment underwriting. Analysis: its strongest role is as the spatial system of record beneath a broader real estate data stack. Principals seeking finished investment conclusions will need additional products and analyst judgment, while land and GIS teams can use Regrid much closer to the center of their daily workflow.

    Data Quality and Sources: 9/10

    Score: 9. Regrid’s central value is the normalization of fragmented government sourced parcel information into a consistent schema. It also exposes county coverage, refresh timing and field availability, which helps data teams assess fitness before deployment. Matched building footprints and other spatial additions can reduce the joining work normally required to assemble a usable land dataset. The unavoidable weakness comes from the source environment. Assessor, recorder and local GIS systems differ in update cycles, definitions and completeness, and a standardized field cannot correct information that was absent or stale at origin. Analysis: Regrid appears strongest as a well organized national foundation with visible local variation, not as a guarantee that every attribute is equally current everywhere. A serious buyer should benchmark several representative counties, compare critical fields against authoritative local records and document acceptable gaps before committing to an enterprise workflow.

    Ease of Adoption: 8/10

    Score: 8. Regrid offers several entry points for different levels of technical maturity. A broker or field researcher can begin in the Property App, while an analyst can purchase a county or state file and work in familiar GIS or data software. APIs, tiles and bulk delivery support more technical implementations without forcing every customer into the same interface. Self service purchasing is particularly helpful for a limited market test. Adoption still requires decisions about geography, attributes, formats, refreshes and permitted uses. Large national files can challenge teams without spatial database experience, and interpreting parcel or zoning fields requires domain knowledge. Analysis: deployment should be fast for an established GIS group and manageable for an analyst using selected downloads. A CRE team with no mapping capability may need implementation help, governance rules and training before the data becomes dependable in routine investment decisions.

    Output Accuracy: 8/10

    Score: 8. Regrid can produce consistent parcel boundaries and standardized attributes at a scale that local source gathering rarely matches efficiently. That consistency improves filtering, mapping and cross market comparisons. Accuracy, however, must be defined by use case. A parcel polygon can be suitable for screening while still being unsuitable for construction staking, legal boundary determination or title resolution. Ownership, mailing address and zoning fields can also lag official changes or reflect local conventions. Analysis: the output is credible for research, prioritization and application development when users retain source awareness and quality controls. It should not be treated as dispositive evidence in a closing, entitlement application or boundary dispute. Buyers should test geometry alignment, null rates, update timing and attribute agreement in representative jurisdictions. They should also create escalation rules requiring surveys, title records or municipal confirmation whenever an analytical result becomes a legal or capital decision.

    Integration and Workflow Fit: 9/10

    Score: 9. Regrid supports the principal delivery patterns expected by modern location and data teams: bulk files, downloadable datasets, APIs, map tiles and a hosted Esri Feature Service. Direct compatibility with ArcGIS Pro and ArcGIS Online is a significant advantage for organizations already standardizing land analysis in the Esri ecosystem. The MCP server also provides an emerging access path for AI oriented clients, though it should be governed like any other data interface. Analysis: the breadth of delivery options makes Regrid easier to position as shared infrastructure rather than an isolated application. The remaining integration work sits with the buyer, including entity matching, internal identifiers, permissions, refresh orchestration and joins to CRM, underwriting or transaction systems. Regrid can supply the parcel key and spatial context, but it does not remove the need for data engineering or reconciliation across the rest of the CRE stack.

    Pricing Transparency: 5/10

    Score: 5. Regrid supports self service county and state purchasing through its Data Store, which is more transparent than a sales only buying process and enables a buyer to price a defined geography during checkout. However, the vendor does not publish a single comprehensive enterprise price schedule covering recurring national files, Feature Service access, API volumes, premium attributes, refresh terms and organizational licensing. That prevents a buyer from estimating full production cost from general product information alone. Analysis: transparency is adequate for a small pilot but limited for annual budgeting and vendor comparison. Procurement teams should request an itemized proposal that separates geography, base parcel data, add ons, refresh frequency, API or service capacity, user rights and redistribution terms. They should also confirm renewal treatment and charges for expanding coverage. Under the BestCRE methodology, the absence of published enterprise pricing caps this dimension at five.

    Support and Reliability: 7/10

    Score: 7. Regrid publishes a support site, tutorial videos, parcel schema information and coverage resources. Those materials address common onboarding questions and give technical users a basis for inspecting fields before integration. Multiple delivery models also suggest that support can be aligned with applications, files or Esri workflows. The vendor does not publicly provide enough detail to score the full service experience at the highest level. Response targets, named account coverage, implementation hours, escalation procedures and service commitments may depend on the contract and are not comprehensively published. Analysis: prospective customers should assess support during a pilot by submitting both a schema question and a county specific discrepancy. Enterprise buyers should negotiate contacts for data quality issues, refresh failures and API incidents. A strong knowledge base helps routine adoption, but parcel data problems often require jurisdiction specific investigation, making accountable human support important for production use.

    Innovation and Roadmap: 8/10

    Score: 8. Regrid has extended a standardized parcel foundation across several access patterns rather than confining the product to downloadable shapefiles. Matched building footprints, secondary addresses, zoning fields, daily ownership update options, hosted Esri delivery and an MCP server show active product development around spatial workflows. The innovation is practical: it reduces friction between raw government records and the systems where analysts actually work. Analysis: the MCP interface is promising for natural language exploration and agent workflows, but its value depends on query controls, traceability and the underlying data. Buyers should not award extra confidence merely because an AI client can retrieve a parcel. Regrid’s more durable innovation lies in normalization, matching and distribution across jurisdictions. The score remains below the maximum because several capabilities are delivery improvements around established parcel information, and their operational advantage must still be proven against each buyer’s existing GIS architecture.

    Market Reputation: 8/10

    Score: 8. Regrid has a visible position in the parcel data market and serves use cases across real estate, government, construction, utilities, insurance and other spatially intensive industries. Its relationship with Esri and direct Feature Service delivery provide meaningful credibility among GIS buyers. Public customer stories and educational resources add evidence that the company operates beyond a narrow or experimental product stage. Regrid does not publish all metrics a buyer might want, including a complete customer count, independently verified retention figures or detailed service performance results. Analysis: its reputation appears strongest among parcel, civic technology and GIS practitioners rather than as a universal CRE brand. That distinction is not a weakness for technical land teams, but principals should evaluate whether internal users recognize and can operate the product. References should match the intended geography, delivery method and commercial use case rather than merely confirming general satisfaction.

    9AI Score Card Regrid
    78
    78 / 100
    Solid Platform
    Parcel Data Platform
    Regrid
    Regrid combines nationwide parcel coverage, building footprints, property attributes, self service downloads, APIs and direct Esri delivery in one standardized data product.
    9 Dimensions, Scored 1 to 10
    1. CRE Relevance
    8/10
    2. Data Quality & Sources
    9/10
    3. Ease of Adoption
    8/10
    4. Output Accuracy
    8/10
    5. Integration & Workflow Fit
    9/10
    6. Pricing Transparency
    5/10
    7. Support & Reliability
    7/10
    8. Innovation & Roadmap
    8/10
    9. Market Reputation
    8/10
    BestCRE.com, 9AI Framework v2 Reviewed October 2026

    Who Should Use Regrid

    Regrid best suits developers, site selectors, renewable energy teams, infrastructure planners and land acquisition groups that evaluate many parcels across county lines. These buyers often lose time locating local files, reconciling fields and joining buildings or addresses before analysis begins. A standardized national layer can shift effort from data collection to screening. It is particularly useful when teams need to filter land by location and parcel attributes, map ownership patterns, review surrounding context or create repeatable market studies.

    GIS and data engineering teams are another strong fit. They can use bulk delivery, APIs, tiles or the Esri Feature Service to distribute a common parcel foundation across internal applications. Software companies that need parcel search inside a customer product may also value the developer interfaces, subject to licensing review. Analysis: the ideal buyer has a defined parcel driven workflow, knows which fields are decision critical and can test data quality by jurisdiction. Organizations already using ArcGIS should place Regrid high on the shortlist because direct hosted access may reduce recurring file administration.

    Who Should Not Use Regrid

    Regrid is not the first purchase for an investment team seeking rent comparables, lease expirations, loan maturities, tenant intelligence or complete transaction histories. Those workflows require a CRE intelligence platform or specialist dataset, potentially joined to Regrid later. Small brokerage teams operating in one county may also find that local assessor and GIS portals cover occasional lookup needs at lower cost, though with more manual work.

    The product is also unsuitable as a substitute for a survey, title report, environmental review or formal zoning opinion. Parcel boundaries and standardized attributes support screening, not legal certification. Analysis: buyers without GIS skills, data engineering capacity or a clearly defined mapping workflow should test the Property App before acquiring large files. If the team cannot specify how parcel records will enter a decision or system, a broad data subscription is likely to become underused infrastructure.

    Pricing and ROI Analysis

    Regrid sells parcel data through a self service Data Store where buyers can select counties or states, formats and available add ons. It also offers the Property App and enterprise delivery methods, including bulk files, API access and an Esri Feature Service. A comprehensive public enterprise rate card is not published. Pricing for national coverage, recurring refreshes, premium attributes, service capacity and organizational rights therefore requires a quote. Buyers should request comparable configurations from every vendor and confirm whether internal sharing, derived products and customer facing use are permitted.

    Analysis: use a simple break even calculation before buying. Add the annual Regrid license, implementation labor and ongoing data administration. Then compare that amount with the analyst and engineering hours currently spent finding county files, cleaning schemas, matching footprints and repairing refreshes. For example, if the platform saves H staff hours per month at a fully loaded hourly cost of C, annual labor value equals H multiplied by C multiplied by twelve. Add the value of faster site decisions only when the team can document it. Proceed when conservative, recurring savings exceed total cost and a county sample meets accuracy requirements.

    Integration and CRE Tech Stack Fit

    Regrid fits most naturally beneath GIS, site selection and internal data products. ArcGIS users can connect through the hosted Feature Service, while engineering teams can use bulk files, APIs or map tiles. The parcel identifier, geometry and address or ownership fields can then be joined to internal opportunity records, environmental layers, infrastructure data and underwriting assumptions. A buyer should define a persistent internal key because source identifiers and local records may change.

    CRM and underwriting integration will usually require customer work or an implementation partner. Regrid is not presented as a native replacement for systems managing deals, contacts or financial models. Analysis: the cleanest architecture keeps Regrid as a governed spatial source, stages updates in a warehouse or GIS environment and publishes approved fields to downstream tools. Teams should log refresh dates, preserve source lineage and prevent users from confusing analytical parcel boundaries with surveyed geometry.

    Competitive Landscape

    LandGlide is the clearest alternative for users primarily seeking mobile parcel lookup and field access. It may suit brokers, inspectors or land professionals whose priority is quickly identifying parcels on a map. Regrid is generally the stronger candidate when a company needs standardized data delivery, county purchases, APIs, matched spatial layers or a foundation for internal applications. The decision should turn on workflow depth, not map appearance.

    LandVision competes more directly for real estate site research and land prospecting, with workflows oriented toward finding and evaluating properties. Reonomy, owned by Altus Group, is more appropriate when commercial property intelligence, ownership research and prospecting are central. ATTOM offers broad property data and APIs across many real estate use cases. Regrid remains differentiated by its parcel first design, self service geographic purchasing and close Esri fit.

    Analysis: a serious evaluation should use the same counties and tasks across vendors. Measure boundary coverage, critical field completion, owner matching, refresh timing, query speed, export usability and licensing constraints. Regrid should lead the shortlist for a GIS centered parcel foundation. Reonomy or ATTOM may lead when entity intelligence and wider property attributes matter more, while LandVision may be preferable for a packaged land search workflow.

    The Bottom Line

    Buy Regrid when standardized parcel geometry is a recurring input to site selection, development or a data product, especially if the organization operates across jurisdictions or relies on Esri. Start with representative counties and require acceptance tests for geometry, ownership, addresses, zoning and refresh timing. The product’s delivery flexibility can justify adoption even before advanced AI features enter the case.

    Do not buy it as a substitute for commercial market intelligence or legal diligence. Analysis: Regrid is a high quality spatial foundation whose return depends on workflow volume and internal capability. Approve a broader contract only after the pilot demonstrates fewer preparation hours, reliable joins and acceptable local completeness. If the team merely needs occasional parcel lookup, begin with the Property App or a narrow geographic purchase instead of enterprise coverage.

    About BestCRE

    BestCRE.com is the definitive authority on commercial real estate AI, analysis, and investment intelligence. Every article advances the platform’s mission to help CRE professionals identify, evaluate, and adopt the best tools and strategies in the industry. We benchmark platforms using the 9AI Framework so CRE leaders can compare tools with clear evidence. Explore the category map at 20 CRE sectors for deeper coverage across the CRE stack.

    Frequently Asked Questions

    What is Regrid and what does it do?

    Regrid is a parcel data and location intelligence platform covering the United States, Canada and a growing set of European markets. It organizes government sourced parcel boundaries and property attributes into a standardized schema, then distributes them through a web and mobile Property App, downloadable files, bulk delivery, APIs, map tiles and an Esri Feature Service. Available layers and attributes can include ownership information, addresses, building footprints, zoning and geographic context. Commercial real estate teams use it for site screening, land research, mapping and internal application development. It is not a complete underwriting or transaction database. Analysis: its best role is to provide the common geographic foundation that a buyer can combine with market, financial, environmental and proprietary data.

    How does Regrid compare with LandGlide, LandVision and Reonomy?

    Regrid is differentiated by its parcel first architecture, standardized national coverage, self service county and state downloads, developer interfaces and direct Esri delivery. LandGlide is commonly considered for straightforward parcel lookup and mobile field use. LandVision is oriented toward packaged property and land search workflows. Reonomy focuses more heavily on commercial property intelligence, ownership discovery and prospecting. Analysis: Regrid is the stronger choice when the buyer needs parcel data as reusable infrastructure across GIS, analytics or software. A sales or acquisitions team that wants ready made company and contact intelligence may prefer Reonomy, while a local field user may need less infrastructure than Regrid provides. Buyers should compare identical counties because attribute completeness and update timing can differ by source and vendor.

    How much does Regrid cost?

    Regrid supports self service purchasing through its Data Store, where a buyer selects a county or state, format and available add ons. It does not publish a single comprehensive enterprise rate card covering all national files, recurring deliveries, APIs, hosted Esri access, premium layers and usage rights. Enterprise buyers therefore need a tailored quote. Ask for an itemized proposal separating base geography, attributes, refresh frequency, service capacity, user permissions and redistribution rights. Analysis: calculate value by comparing total annual cost with current labor spent sourcing local files, cleaning schemas, matching other layers and maintaining updates. A limited county purchase or app trial is the appropriate first step when usage volume is uncertain. Avoid comparing vendors until quotes reflect equivalent coverage, fields, refreshes and licensing.

    Who should use Regrid for commercial real estate?

    Regrid is best suited to developers, site selectors, land acquisition teams, renewable energy groups, infrastructure planners, GIS departments and software teams that repeatedly analyze parcels across multiple counties. It is especially relevant when users need consistent geometry, ownership fields, addresses, building footprints or zoning context inside maps, databases or applications. Organizations using ArcGIS should consider it because the hosted Feature Service can place the data directly into supported Esri workflows. Analysis: the strongest buyer can name the fields that drive decisions, test local completeness and maintain data governance. A brokerage team needing only occasional local lookups may be adequately served by a public county portal or simpler mobile product. Investment teams seeking rents, tenants, debt or transaction records will need additional CRE data sources.

    Will Regrid’s MCP server change how CRE teams use parcel data?

    The MCP server could make parcel information easier to query from compatible AI clients, particularly for exploratory questions, application prototypes and agent assisted research. It may reduce the technical effort required to translate a natural language request into a parcel lookup. It does not change the authority or completeness of the underlying government sourced records, and an AI generated response still requires traceability and verification. Analysis: the near term value is likely to be faster access, not autonomous investment decisions. CRE teams should require returned parcel identifiers, source fields, geography and refresh context, then route material findings into established diligence. Before production use, buyers should test permissions, logging, query consistency, error handling and protection of proprietary data sent through the surrounding AI system.

    Related Reviews

    Compare Regrid with other tools BestCRE has scored in the same category: Matterport, Cotality, HelloData. Explore more CRE AI tool reviews in our Best CRE AI Tools directory. For sector-specific analysis and market intelligence, visit our 20 CRE Sectors hub.
  • ATTOM Review: National property data for APIs analytics and AI

    ATTOM Review: National property data for APIs analytics and AI

    BestCRE 9AI Score

    70/100 · Contender

    ATTOM ranks #236 of 386 commercial real estate AI tools scored on the 9AI Framework. Nine dimensions, each scored out of 10: CRE relevance, data quality, ease of adoption, output accuracy, integration fit, pricing transparency, support, innovation and market reputation.

    ATTOM is a property data and analytics provider based in Irvine, California. Its primary buyers include investors, lenders, real estate technology companies and enterprise data teams that need standardized records across a national footprint. In a commercial real estate workflow, ATTOM can replace the slow assembly of assessor, deed, mortgage, foreclosure, boundary and neighborhood information from numerous local sources. The platform is most relevant before underwriting, during portfolio monitoring and when a software company needs property intelligence embedded inside its own product.

    The product is better understood as data infrastructure than as a finished CRE operating system. ATTOM supplies property records, derived analytics and delivery mechanisms, while the customer determines how those elements enter acquisition models, risk systems, prospecting tools or AI applications. Delivery options include an API, bulk licensing, cloud platforms and an MCP server. ATTOM also markets valuation, rental, comparable-sales, market, location and property-risk analytics, alongside specialized AI agents.

    That breadth is the principal attraction. A buyer can source ownership, tax, property characteristics, deeds, mortgages, foreclosure events, permits, parcel boundaries, schools, demographics and points of interest from one vendor. ATTOM publicly states that its data covers more than 160 million United States properties. However, broad property coverage is not the same as deep commercial asset intelligence. Teams still need to test whether the required fields, histories and entity relationships are sufficiently complete for their target markets and property types.

    BestCRE’s analysis is that ATTOM is a strong data foundation for technically capable organizations, especially those operating across many jurisdictions. It is less compelling for a principal who wants an immediately usable acquisition interface, verified tenant information or institutional CRE transaction context without internal engineering. Pricing is not publicly posted, which also makes procurement harder to evaluate before a sales process. The buying decision should therefore rest on a field-level coverage test, permitted-use review and implementation estimate, not on the length of the dataset catalog.

    What ATTOM Does and How It Works

    ATTOM collects and standardizes property information that originates across fragmented public and commercial sources. Its catalog includes assessor and tax records, physical property characteristics, geocodes, ownership, deeds, mortgage records, sales prices, foreclosure data and building permits. It also supplies geographic and contextual layers such as parcel, school and neighborhood boundaries, demographics and points of interest. Customers can use these fields to enrich an address, verify an asset, screen a market, monitor a portfolio or prefill an underwriting workflow.

    Access is designed for several technical operating models. The Property Data API supports application queries and record retrieval, while bulk licensing and file delivery serve teams that maintain internal warehouses or run large recurring analyses. Cloud delivery through Snowflake and Databricks can reduce file movement for customers already working in those environments. The MCP server is intended to make governed property information accessible to compatible AI systems and agents. ATTOM Nexus provides a discovery environment where prospective users can examine datasets and coverage before implementation, although access conditions and any associated cost are not publicly detailed.

    Above the underlying records, ATTOM offers modeled and derived products. These include an automated valuation model, a rental valuation model, comparable sales, sales trends, school ratings, neighborhood information, default propensity and natural hazard indicators. Its advertised AI agents address property and place questions, data analysis and report generation. These tools can shorten the path from a raw record to a usable response, but buyers should distinguish sourced facts from modeled estimates and generated narrative. BestCRE’s analysis is that production use requires field definitions, timestamps, confidence rules and audit trails to remain visible downstream. ATTOM can supply many ingredients for an enterprise property intelligence layer, but the customer remains responsible for workflow design, exception handling and final investment decisions.

    9AI Framework: Dimension by Dimension Analysis

    CRE Relevance: 7/10

    ATTOM earns a 7 for CRE relevance. Its ownership, tax, deed, mortgage, foreclosure, permit, boundary and location data can support acquisition screening, underwriting inputs, portfolio surveillance and loan analysis. Nationwide normalization is particularly useful when a CRE organization operates across counties with inconsistent public systems. The limitation is product orientation. ATTOM serves the broader property and housing market, and much of its public positioning is residential. It does not present itself as a complete commercial transaction, leasing, tenant, building operations or asset management platform. BestCRE’s analysis is that the fit depends heavily on the workflow. It can be central infrastructure for a proptech company or lender, yet only a supplemental source for an acquisitions team that needs institutional sales context, rent rolls, tenants and broker intelligence.

    Data Quality and Sources: 8/10

    ATTOM earns an 8 for data quality because it offers a broad, structured catalog spanning property, ownership, mortgage, transaction, foreclosure, boundary and neighborhood domains. The availability of historical public records, geocodes and parcel information supports cross checking and entity resolution. ATTOM Nexus is also positioned as a way to examine coverage before deployment, which is valuable in a category where national claims can obscure local gaps. Still, public records inherit recording delays, jurisdictional differences and source errors. Modeled outputs introduce additional assumptions. The vendor does not publicly provide one universal field-level completeness or freshness guarantee that applies across every dataset and county. BestCRE’s analysis is that buyers should request samples for representative counties, measure populated fields, compare known assets and document update intervals before assigning production authority to the data.

    Ease of Adoption: 6/10

    ATTOM earns a 6 for ease of adoption. Multiple delivery options let sophisticated customers choose an API, bulk files, cloud access or an MCP connection rather than redesigning their architecture around one channel. The discovery environment can also help teams inspect data before committing engineering resources. Adoption is nevertheless more involved than subscribing to a finished analytics application. A customer may need address matching, schema mapping, identity resolution, data storage, monitoring and business rules before users see value. Licensing restrictions must also be translated into application behavior and user permissions. BestCRE’s analysis is that a data engineering team can make ATTOM productive, but a small brokerage or principal without technical staff may face a significant implementation burden. The vendor does not publish a standard implementation timetable, so buyers should obtain a written deployment plan.

    Output Accuracy: 7/10

    ATTOM earns a 7 for output accuracy. Recorded deeds, assessor attributes, mortgage documents and similar fields can provide a defensible factual base when source dates and jurisdictions are preserved. Derived valuation, rental, risk and AI outputs can accelerate analysis, but they should not be treated as equally authoritative. Automated estimates may be less dependable for unusual commercial assets, thinly traded locations or properties with material conditions that public records do not capture. Generated reports can also present a confident narrative even when underlying fields are incomplete. BestCRE’s analysis is that ATTOM is suitable for screening and evidence gathering, with human review required for investment, credit and appraisal conclusions. Buyers should test known outcomes, retain source lineage and set escalation rules for missing or conflicting records. Public accuracy metrics are not published uniformly across all products.

    Integration and Workflow Fit: 9/10

    ATTOM earns a 9 for integration. The vendor offers API access, bulk delivery, file options, Snowflake, Databricks and an MCP server, covering most common enterprise data patterns. This allows a customer to use transactional queries in an application, load licensed records into a warehouse or expose approved property context to AI agents. The architecture is more flexible than products that confine analysis to a proprietary interface. Integration breadth does not eliminate integration work, however. Customers must map identifiers, manage refreshes, control entitlements and reconcile ATTOM records with CRM, loan, asset management and geographic systems. BestCRE’s analysis is that ATTOM’s delivery design is one of its strongest competitive features. Before contracting, technical teams should confirm endpoints, quotas, schemas, cloud-sharing arrangements, versioning policy and whether every required dataset is available through the preferred channel.

    Pricing Transparency: 3/10

    ATTOM earns a 3 for pricing transparency. The vendor does not publish standard subscription prices, usage tiers, API rates, bulk licensing fees or cloud delivery charges. That may reflect legitimate variation in datasets, geography, volume, refresh frequency, permitted uses and redistribution rights, but it prevents buyers from estimating cost without entering a sales process. It also makes direct comparison with alternative sources more time consuming. BestCRE’s analysis is that procurement should request a detailed quote separating data rights, delivery, implementation, support, overages and renewal terms. Buyers should also ask whether testing access is free, whether historical depth changes the fee and whether generated or enriched outputs may be stored or shared. ATTOM can still offer attractive economics at scale, but public information is insufficient to judge value for a particular customer.

    Support and Reliability: 7/10

    ATTOM earns a 7 for support. The company emphasizes customer and technical assistance, and an enterprise data implementation normally requires both. Its range of delivery methods suggests experience working with developers, analysts and data operations teams rather than only end users. Public resources also include market research, articles, webinars, case studies, white papers and a glossary. However, ATTOM does not publicly state universal response targets, named support tiers or service commitments that would let a buyer compare support quality before contracting. BestCRE’s analysis is that support should be evaluated through the contract and reference process. Buyers should request an escalation path, onboarding responsibilities, schema-change notice periods, data-issue remediation procedures and availability expectations. A technically complex deployment warrants a named owner and clear boundaries between implementation help, data investigation and custom engineering.

    Innovation and Roadmap: 8/10

    ATTOM earns an 8 for innovation. Its MCP server and specialized AI agents show a credible effort to make property records usable inside emerging agent workflows, rather than merely attaching an AI label to a conventional search interface. Cloud delivery, APIs and bulk access also give customers practical ways to combine the same data foundation with their own models and applications. The valuation, rental, market and risk layers extend the offering beyond raw public records. BestCRE’s analysis is that the most meaningful innovation is governed access to structured property context, not report generation by itself. Execution still matters. Buyers need evidence that agents cite source fields, respect permissions and handle uncertainty. The vendor does not publish enough standardized performance evidence to determine how its AI outputs compare across commercial property types, so pilots should focus on repeatability and traceability.

    Market Reputation: 8/10

    ATTOM earns an 8 for market reputation. It is an established property data name with visible research, industry coverage and products used across real estate, mortgage, government, insurance, technology and financial services. Its public positioning and extensive dataset catalog indicate a mature enterprise supplier rather than an early product seeking its first repeatable use case. Media organizations also use ATTOM information in housing market coverage. Even so, reputation in broad property data should not be confused with category leadership in every segment of institutional CRE. ATTOM does not publish a complete customer count, retention rate or independently audited satisfaction measure. BestCRE’s analysis is that buyers can reasonably place ATTOM on a serious enterprise shortlist, but should still obtain references whose property types, jurisdictions, delivery method and licensing needs resemble their own.

    9AI Score Card ATTOM
    70
    70 / 100
    Solid Platform
    Property Data Intelligence
    ATTOM
    ATTOM is best suited to technical teams that need nationwide property records delivered through APIs, bulk files, cloud platforms or an MCP server.
    9 Dimensions, Scored 1 to 10
    1. CRE Relevance
    7/10
    2. Data Quality & Sources
    8/10
    3. Ease of Adoption
    6/10
    4. Output Accuracy
    7/10
    5. Integration & Workflow Fit
    9/10
    6. Pricing Transparency
    3/10
    7. Support & Reliability
    7/10
    8. Innovation & Roadmap
    8/10
    9. Market Reputation
    8/10
    BestCRE.com, 9AI Framework v2 Reviewed October 2026

    Who Should Use ATTOM

    ATTOM is best suited to property technology developers, institutional investors, lenders and data teams that need normalized records across many United States jurisdictions. It is particularly relevant when an organization is building an address-level search product, enriching a CRM, screening collateral, monitoring foreclosure or mortgage activity, or assembling a property intelligence warehouse. Teams using Snowflake or Databricks may value receiving data closer to their existing analytical environment, while application developers can work through the API.

    The strongest buyer has engineers or data analysts who can evaluate fields, integrate identifiers and maintain quality controls. Portfolio managers operating across markets may also benefit when local sourcing has become inconsistent or labor intensive. AI product teams are another plausible fit because the MCP server and agent products provide paths to property context. BestCRE’s analysis is that these teams should choose ATTOM when national breadth, delivery flexibility and machine-readable records matter more than a polished CRE transaction interface. A paid pilot should represent the buyer’s actual counties, asset types and use cases.

    Who Should Not Use ATTOM

    ATTOM is not the natural first purchase for a small brokerage, owner or acquisitions team seeking a ready-made system for deal discovery, tenant research, leasing intelligence or relationship management. Such buyers may find that the data requires more engineering and interpretation than their workflow can support. Teams focused only on a few local markets may also obtain deeper information from specialized regional sources, public systems or a CRE-specific platform.

    It is also a weaker fit when the core requirement is institutional commercial sales comparables, verified company occupancy, rent rolls, lease terms or property operations. Those needs extend beyond ATTOM’s central public-record and property-data strengths. Buyers that require self-serve pricing before evaluation will encounter another obstacle because standard rates are not published. BestCRE’s analysis is that an organization should not buy ATTOM merely to claim an AI capability. It should have a defined data problem, a measurable workflow and staff who can govern the resulting information.

    Pricing and ROI Analysis

    ATTOM does not publish standard prices for its API, bulk licensing, cloud delivery, MCP server or AI agents. Pricing likely depends on the selected datasets, record volume, geography, delivery method, update frequency and rights to display, store or redistribute information, but the vendor does not publish a universal formula. Buyers should request a quote that separates recurring data access, implementation, support, overages and any fees tied to historical records or derived products. Contract review should focus closely on permitted uses, retention and redistribution.

    BestCRE’s analysis: calculate ROI using avoided data work and measurable workflow improvement. If a team currently spends 80 analyst hours each month collecting and normalizing records, and its fully loaded labor cost is $75 per hour, the addressable labor cost is $6,000 monthly. A deployment that removes half of that work creates $3,000 in monthly capacity before considering faster underwriting or improved coverage. Compare the annualized benefit with the complete first-year cost, including engineering, quality assurance and storage. This illustration is analysis, not ATTOM pricing or a promised saving.

    Integration and CRE Tech Stack Fit

    ATTOM fits best as a property data layer beneath a CRE application stack. API calls can enrich records inside underwriting, lending, CRM or portfolio systems. Bulk files can feed a warehouse, while Snowflake and Databricks delivery can support analysis where enterprise data already resides. The MCP server creates another route for approved AI systems to query property context. Customers should use stable internal property identifiers rather than relying only on addresses.

    Implementation should begin with schema and licensing review. Teams need to map ATTOM fields to parcel, loan, contact and asset records, then define refresh schedules and conflict rules. A production design should preserve source dates and separate recorded facts from modeled values or generated text. BestCRE’s analysis is that ATTOM integrates well technically, but business integration remains the customer’s responsibility. Confirm whether required datasets share identifiers, whether historical changes are delivered and how API or schema changes are communicated.

    Competitive Landscape

    Cotality, formerly associated with the CoreLogic brand, is the closest broad property-data comparison and has already scored 91 in this BestCRE category. Buyers should compare field coverage, valuation products, risk information, licensing and service within the precise jurisdictions they operate. ATTOM may appeal more strongly to API-first and AI-oriented product teams because it prominently offers cloud delivery, an MCP server and specialized agents. The deciding evidence should come from matched property samples, not catalog breadth alone.

    Reonomy, an Altus Group product, is a more CRE-specific alternative for commercial property intelligence, ownership discovery and prospecting. It may suit brokers and acquisitions professionals who want an application centered on commercial assets rather than a general property data foundation. Cherre is an alternative for organizations prioritizing data integration, normalization and governance across multiple real estate sources. Its role can overlap with ATTOM’s infrastructure value, although the products approach the problem from different starting points.

    Regrid is worth considering when parcel boundaries, spatial data and land records are the primary requirement. It may offer a more focused parcel-centered proposition, while ATTOM spans a wider mix of mortgage, foreclosure, transaction, valuation and neighborhood information. BestCRE’s analysis is that ATTOM wins consideration through breadth and delivery flexibility. It loses ground when a buyer needs a CRE-native user workflow, public price discovery or a narrowly specialized dataset with greater local depth.

    The Bottom Line

    Put ATTOM on the shortlist if your organization needs a national property data foundation and has the technical capacity to integrate it. Its breadth, API options, cloud delivery and AI access model are credible advantages for lenders, investors and proptech builders. Require a representative data sample and test completeness, freshness, identifiers and modeled outputs against known assets before negotiating a full license.

    Do not select ATTOM solely for its dataset count or AI positioning. The material questions are whether its fields answer your commercial workflow, whether licensing permits the intended product and whether implementation costs preserve the business case. BestCRE’s analysis is that ATTOM is a strong CRE-adjacent infrastructure choice, but not a substitute for specialized leasing, tenant, transaction or asset management systems.

    About BestCRE

    BestCRE.com is the definitive authority on commercial real estate AI, analysis, and investment intelligence. Every article advances the platform’s mission to help CRE professionals identify, evaluate, and adopt the best tools and strategies in the industry. We benchmark platforms using the 9AI Framework so CRE leaders can compare tools with clear evidence. Explore the category map at 20 CRE sectors for deeper coverage across the CRE stack.

    Frequently Asked Questions

    What is ATTOM property data?

    ATTOM is a United States property data and analytics provider. It organizes assessor and tax information, physical property characteristics, ownership, deeds, mortgages, sales, foreclosures, permits, boundaries, schools, neighborhoods and related contextual data. Customers can receive information through an API, bulk files, cloud platforms or an MCP server. ATTOM also offers derived products such as automated valuations, rental estimates, comparable sales, market analytics and risk indicators. For commercial real estate users, it is best viewed as a data foundation that can support underwriting, portfolio monitoring, prospecting and application development. It is not a complete CRE operating platform, and teams seeking lease, tenant or institutional transaction intelligence may need other sources.

    How does ATTOM compare with Reonomy and Cotality?

    ATTOM and Cotality both compete as broad property data suppliers, with records and analytics that can serve real estate, lending, insurance and technology workflows. A useful comparison should test the exact fields, counties, histories, valuation outputs and licensing rights required by the buyer. Reonomy is more explicitly centered on commercial real estate intelligence and may be easier for brokers or acquisitions teams that want ownership research and prospecting in a ready-made interface. ATTOM’s relative strength is its range of delivery options, including API, bulk, cloud and MCP access. BestCRE’s analysis is that technical product teams may prefer ATTOM’s infrastructure orientation, while CRE professionals seeking an end-user workflow may favor Reonomy. No vendor should be chosen without matched asset testing.

    How much does ATTOM cost?

    ATTOM does not publish standard pricing for its Property Data API, bulk data licenses, cloud delivery, MCP server or AI agents. Buyers must contact the company for a quote. The final cost may vary with selected datasets, geography, usage volume, update frequency, delivery method and rights to retain, display or redistribute the data, although ATTOM does not publish one universal pricing formula. Ask for a complete first-year and renewal estimate that separates licensing, onboarding, support, usage limits and overage charges. Also confirm whether a representative evaluation dataset is available before commitment. BestCRE’s analysis is that the absence of public rates is a meaningful procurement weakness because buyers cannot screen affordability or compare alternatives without a sales process.

    Who should use ATTOM?

    ATTOM best suits lenders, institutional investors, property technology companies and enterprise data teams that require standardized property records across many United States markets. Strong use cases include enriching an application, screening collateral, monitoring ownership or mortgage events, building a property warehouse and supplying governed context to an AI assistant. The ideal customer has engineers or analysts who can map schemas, reconcile identifiers, monitor updates and apply licensing controls. A smaller CRE team can still benefit, but only if it has a clear workflow and adequate implementation resources. ATTOM is less suitable for buyers seeking an immediate replacement for a brokerage database, leasing platform, rent roll system or asset management application. BestCRE’s analysis is that technical readiness matters almost as much as data need.

    Will ATTOM AI agents improve CRE underwriting?

    ATTOM’s AI direction could improve early underwriting by making property facts, market context and derived analytics easier to query and summarize. Its MCP server may also help compatible AI systems reach approved data without relying on copied reports or unstructured searches. The forward-looking opportunity is faster evidence gathering with clearer links to structured records. The risk is that generated narrative can conceal missing fields, stale public records or model uncertainty, especially for unusual commercial assets. BestCRE’s analysis is that buyers should treat agents as an analytical interface, not an autonomous investment authority. A pilot should measure source traceability, repeatability, exception handling and time saved on real deals. ATTOM does not publish enough universal performance evidence to assume equal results across CRE property types.

    Related Reviews

    Compare ATTOM with other tools BestCRE has scored in the same category: Matterport, Cotality, HelloData. Explore more CRE AI tool reviews in our Best CRE AI Tools directory. For sector-specific analysis and market intelligence, visit our 20 CRE Sectors hub.
  • Green Street Review: Independent CRE research data valuations and market intelligence

    Green Street Review: Independent CRE research data valuations and market intelligence

    BestCRE 9AI Score

    80/100 · Contender

    Green Street ranks #95 of 372 commercial real estate AI tools scored on the 9AI Framework. Nine dimensions, each scored out of 10: CRE relevance, data quality, ease of adoption, output accuracy, integration fit, pricing transparency, support, innovation and market reputation.

    Green Street is a CRE research, data and analytics provider used primarily by REIT investors, institutional property owners, lenders, advisors and brokers. Its core workflow starts before an acquisition, disposition, financing or allocation decision, when an analyst needs an independent view of pricing, fundamentals and relative value. The platform brings together public market research, private market data, valuation models, transaction evidence and news, reducing the need to reconcile separate research subscriptions and internal spreadsheets.

    Its strongest distinction is the connection between listed real estate securities and private property markets. Green Street built its reputation through independent REIT research, then extended that analytical approach into commercial property pricing, market forecasts, sales comps, debt data and advisory work. For investment committees comparing sectors, markets and ownership structures, that combined perspective can be more useful than a database focused mainly on listings or recorded transactions.

    The product is not simply a searchable comp repository. Users can examine market fundamentals, proprietary forecasts, company analytics, estimated property values and the Green Street Commercial Property Price Index. Delivery options include the Green Street Platform, Excel, Snowflake and API access. The API includes more than 1,500 proprietary data series, giving quantitative teams a practical path to feed Green Street information into underwriting models, portfolio dashboards and internal risk systems.

    BestCRE analysis: Green Street is a high quality institutional product, but it is not automatically the right data source for every CRE organization. Its value depends on whether the buyer needs independent forecasts and cross market analysis, rather than only contact records, property listings or occasional comps. Pricing is not publicly posted, which makes budget qualification and competitor comparison harder. Buyers should request a tightly scoped demonstration using their own markets and assets, then test whether the research changes actual investment decisions.

    What Green Street Does and How It Works

    Green Street organizes its offering around research, data and analytics, news and advisory services. In the research workflow, an investor can evaluate sectors and markets using forecasts, market relative benchmarks, property commentary and reports that condense Green Street’s current view. Public market tools add REIT coverage, company analytics and charting. Private market products provide property fundamentals, transaction comps and market level information. This structure supports both top down allocation work and more specific underwriting questions.

    For valuation, Green Street offers automated valuation models and property analytics intended to estimate asset values, compare portfolios and monitor changes over time. Sales comps provide transaction evidence, while the Commercial Property Price Index supplies a recurring view of property pricing. These outputs should be treated as decision inputs rather than appraisal replacements. BestCRE analysis: the main benefit is consistency. A team can apply one research methodology across repeated market reviews instead of rebuilding assumptions from unrelated reports, broker opinions and spreadsheet tabs.

    Data integrations extend the product beyond its native interface. Excel access fits analysts who build underwriting and portfolio models in workbooks. Snowflake and API delivery are better suited to organizations with a data warehouse, engineering support and governed internal dashboards. GreenStreetAI and its Model Context Protocol server provide another access layer, allowing users to query Green Street intelligence through compatible AI tools. News and packaged workflows add current context to those interactions. Buyers should still verify citations, definitions, geographic coverage and update timing before placing AI generated responses into an investment memorandum.

    9AI Framework: Dimension by Dimension Analysis

    CRE Relevance: 10/10

    Green Street earns a 10 for CRE relevance because commercial property and listed real estate are the center of the product, not an adjacent vertical. Its research, sales comps, market fundamentals, valuation models, debt information, REIT analytics and price indexes map directly to acquisition, disposition, lending, portfolio strategy and capital allocation workflows. Coverage connects public and private markets, which matters to institutions comparing implied REIT values with direct property pricing. The product also serves distinct CRE roles, including investors, lenders, brokers and advisors. BestCRE analysis: few platforms align as closely with the questions an investment committee asks about sector selection, market strength, asset pricing and relative value. The limitation is not relevance but scope fit. A small operator needing basic rent comps or prospecting data may use only a fraction of the available intelligence.

    Data Quality and Sources: 9/10

    Green Street earns a 9 for data quality. Its offering combines proprietary research, market fundamentals, sales comps, forecasts, REIT analytics, property valuation data and more than 1,500 proprietary series available through its API. The firm’s long research history and stated independence strengthen the usefulness of its data for investment work, particularly where a buyer wants a consistent methodology across markets and sectors. Expanded transaction coverage also makes the platform more practical for private market analysis. BestCRE analysis: quality should not be confused with universal completeness. Transaction databases can differ materially in geographic depth, asset classification, reported consideration and update timing. Prospective customers should test recent deals in their target submarkets and review data dictionaries before subscribing. Green Street does not publish enough field level completeness statistics to independently quantify coverage across every market and property type.

    Ease of Adoption: 7/10

    Green Street earns a 7 for ease of adoption. Analysts can work through a dedicated platform and familiar delivery channels such as Excel, while research reports and packaged insights can shorten the path from data to an investment view. Those options make initial consumption easier than implementing a data feed alone. GreenStreetAI may also lower the search burden for users who prefer natural language questions. BestCRE analysis: meaningful adoption still requires training. Users must understand Green Street’s definitions, market boundaries, forecasts and valuation methodology before applying outputs to underwriting or portfolio decisions. API and Snowflake deployments add data mapping, permissions, quality controls and engineering work. The breadth of the product can also create unused access if licenses are purchased without clear workflows. A pilot should focus on a few repeatable decisions, named users and measurable time savings.

    Output Accuracy: 9/10

    Green Street earns a 9 for output accuracy because its research and valuation products are built for institutional decision making and draw on proprietary CRE data rather than generic web content. Independent research, recurring price indexes, transaction evidence and formal valuation models offer a more defensible foundation than an unstructured AI response or broker anecdote alone. The score does not mean every forecast or estimated value will prove correct. Property markets are illiquid, reporting can lag and asset specific conditions may not be visible in market level data. BestCRE analysis: users should distinguish observed facts, modeled estimates and analyst forecasts in every output. Automated valuations need comparison with recent local comps, lease details, capital requirements and professional appraisal work when required. AI generated answers also warrant source review. Green Street does not publish a universal accuracy rate covering every model, market and forecast.

    Integration and Workflow Fit: 9/10

    Green Street earns a 9 for integration because it supports Excel, Snowflake and API delivery in addition to its own platform. The API exposes more than 1,500 proprietary data series, which can support underwriting templates, portfolio monitoring, research portals, risk dashboards and data science workflows. Snowflake access is especially relevant to institutions that already centralize property, accounting and market data in a cloud warehouse. GreenStreetAI’s Model Context Protocol server creates a newer route for bringing licensed intelligence into compatible AI environments. BestCRE analysis: these are strong technical options, but integration quality depends on contract rights, metadata, refresh schedules and the buyer’s internal resources. An API does not remove the need to map identifiers, preserve historical revisions and monitor failed loads. Buyers should ask which products and fields are available through each delivery method, since platform content and licensed feeds may not be identical.

    Pricing Transparency: 3/10

    Green Street earns a 3 for pricing transparency. The vendor does not publish standard subscription prices, seat costs, data feed fees or implementation charges on its public website. Buyers are directed toward a demonstration and sales process, suggesting that pricing varies by product, geography, coverage, user count and delivery method. Customized enterprise pricing is common for institutional CRE data, but it prevents a buyer from estimating total cost before engaging sales. BestCRE analysis: procurement teams should request an itemized quote separating platform access, research modules, news, valuation products, API or Snowflake delivery, implementation and renewal increases. They should also confirm export rights, historical data access and limits on internal distribution. A multiyear proposal should be compared on equivalent coverage and usage rights, not merely the headline subscription amount. The absence of public pricing materially lowers this score.

    Support and Reliability: 7/10

    Green Street earns a 7 for support. Its institutional positioning, advisory services, demonstrations, research operation and multiple delivery channels indicate that customers can access more than a self service software interface. Complex data and valuation products benefit from specialists who can explain methodology, field definitions and appropriate use. Advisory services may provide deeper guidance where a customer needs strategic interpretation rather than technical troubleshooting. However, Green Street does not publicly provide enough detail about standard support packages, response times, service level commitments, onboarding schedules or dedicated account coverage to justify a higher score. BestCRE analysis: support quality should be tested during procurement. Buyers should submit sample methodology, data correction and API questions, then judge the speed and specificity of the responses. Contracts should identify escalation paths, implementation responsibilities, training entitlements and procedures for disputed transaction or property records.

    Innovation and Roadmap: 9/10

    Green Street earns a 9 for innovation. It is extending an established research and data business through automated valuation models, cloud data delivery, an API with more than 1,500 proprietary series and GreenStreetAI. Its Model Context Protocol server is particularly relevant because it can make licensed institutional intelligence available inside compatible AI tools rather than requiring every question to begin in a separate platform. News access and packaged workflows can add context and repeatability to that experience. BestCRE analysis: the innovation is credible because it sits on top of CRE specific research and data. The remaining question is execution. Natural language access must preserve permissions, citations, definitions and update timing, while limiting unsupported synthesis. Buyers should evaluate whether AI responses reliably point back to source material and whether packaged workflows improve completed analysis, not merely make data retrieval feel faster.

    Market Reputation: 9/10

    Green Street earns a 9 for market reputation. It is well known among institutional real estate investors for independent REIT research and has extended that position into private market data, valuation, news and advisory services. Its stated 40 year research history supports confidence that the organization has operated across several property cycles. The combination of public and private market coverage gives it a recognizable place beside larger property databases and specialized comp providers. BestCRE analysis: reputation is strongest among sophisticated investors, securities analysts and other users who value an independent market view. That does not guarantee equal recognition among small property operators or local brokerage teams. Green Street is private equity backed, and the vendor does not publish customer counts or retention rates that would allow an outside reviewer to quantify adoption. Buyers should therefore rely on reference calls with comparable institutions and product specific diligence.

    9AI Score Card Green Street
    80
    80 / 100
    Strong Performer
    CRE Market Analytics
    Green Street
    Green Street gives institutional investors one source for independent research, REIT analysis, property valuations, sales comps, forecasts and private market fundamentals.
    9 Dimensions, Scored 1 to 10
    1. CRE Relevance
    10/10
    2. Data Quality & Sources
    9/10
    3. Ease of Adoption
    7/10
    4. Output Accuracy
    9/10
    5. Integration & Workflow Fit
    9/10
    6. Pricing Transparency
    3/10
    7. Support & Reliability
    7/10
    8. Innovation & Roadmap
    9/10
    9. Market Reputation
    9/10
    BestCRE.com, 9AI Framework v2 Reviewed October 2026

    Who Should Use Green Street

    Green Street best suits institutional owners, asset managers, REIT investors and investment committees that repeatedly compare sectors, markets and property values. These buyers can use the connection between public market signals and private property fundamentals to inform allocation, acquisition and disposition decisions. Portfolio strategy teams should find particular value in recurring forecasts, standardized market views and pricing indexes. Lenders and credit investors can also use the research, debt data, transaction evidence and market outlook to challenge sponsor assumptions and monitor collateral exposure.

    It also fits research intensive advisors and brokers who need an independent analytical reference alongside local market knowledge. The strongest buyer has analysts who will use the platform weekly, clear governance for incorporating external data and enough deal volume to spread subscription costs across many decisions. Organizations with Snowflake, internal dashboards or quantitative models can gain additional value from the API and its more than 1,500 proprietary series. BestCRE analysis: the ideal customer is not buying another database for occasional searches. It is buying a repeatable framework for investment judgment and has designated people responsible for turning that information into decisions.

    Who Should Not Use Green Street

    Small owners, local brokers and occasional investors may find Green Street broader and more institutionally oriented than necessary. A team whose main needs are prospecting, ownership contacts, active listings or a handful of local rent comps may receive clearer value from a narrower property database or brokerage tool. Companies without dedicated analysts may also struggle to convert extensive research and forecasts into repeatable decisions. Since pricing is not published, smaller buyers cannot quickly determine whether the expected usage justifies the cost.

    Green Street is also a weaker fit for organizations seeking a complete operating system for leasing, property management, accounting or construction. It supplies intelligence for decisions, not the transactional workflow that executes every part of asset operations. Buyers wanting appraisal compliant conclusions should not treat automated estimates as a substitute for required professional valuation. BestCRE analysis: if a team cannot name the decisions, users and models that will consume Green Street data, it should delay purchase and run a tightly defined pilot first.

    Pricing and ROI Analysis

    Green Street does not publish standard prices for platform subscriptions, research, private market data, public market data, news, valuation products, API access or Snowflake delivery. Public information does not disclose minimum contract values, per user charges, implementation fees or typical renewal terms. Buyers should expect a customized quote based on selected products, geography, user count, data rights and delivery method. Procurement should request separate prices for each module, historical data, exports, internal sharing, onboarding and technical support. That structure makes it easier to remove low use products and compare a direct interface with a licensed data feed.

    BestCRE analysis: simple ROI math should start with annual fully loaded cost divided by the number of material decisions supported. If a hypothetical subscription and implementation cost is C, and the team expects N acquisitions, dispositions, financings or portfolio reviews each year, the direct cost per decision is C divided by N. The buyer should then add analyst hours saved, using hours saved per workflow multiplied by completed workflows and hourly labor cost. No dollar assumption is necessary. Approval is sensible when documented time savings and expected decision value comfortably exceed C. Buyers should avoid claiming that one better forecast pays for the product unless they can document how Green Street uniquely changed the decision.

    Integration and CRE Tech Stack Fit

    Green Street fits an institutional CRE technology stack through its platform, Excel delivery, Snowflake access and API. Excel supports underwriting and recurring analyst models without forcing every user into a new development environment. Snowflake can place licensed information near internal property, lease, accounting and portfolio data. The API, with more than 1,500 proprietary series, supports automated dashboards, market monitoring and quantitative research. GreenStreetAI’s Model Context Protocol server can connect intelligence to compatible AI tools, subject to licensing and access controls.

    Implementation should begin with identifiers, definitions and refresh policies. CRE systems often use inconsistent property names, market boundaries and sector classifications, so buyers need mapping rules before combining external series with internal records. BestCRE analysis: request a data dictionary, sample payloads, revision policy, uptime terms and a complete list of fields available through each channel. Confirm whether users may store historical snapshots, distribute derived outputs internally and send licensed content into third party AI systems. Those contractual details can matter as much as technical connectivity.

    Competitive Landscape

    CoStar is the broadest alternative for teams prioritizing property records, listings, ownership information, market data and brokerage workflows. MSCI Real Capital Analytics is a strong comparison for transaction data, capital flows and commercial property sales analysis. Moody’s REIS competes in market fundamentals, forecasts and risk analysis. CompStak is especially relevant when lease and sales comps are the primary requirement. Each alternative should be tested in the exact markets and property types the buyer covers, because nominally similar databases can differ in depth and update timing.

    Green Street stands apart through its independent REIT research pedigree and its attempt to connect listed real estate, private property markets, valuations and forecasts within one analytical framework. BestCRE analysis: choose Green Street when sector allocation, relative value and an independent forward view matter as much as individual records. Choose CoStar when daily property and brokerage coverage drives the workflow. Favor MSCI Real Capital Analytics for transaction and capital market analysis, Moody’s REIS for conventional market forecasting comparisons, or CompStak for comp centered underwriting. Many institutions may use Green Street beside one of these products rather than as a complete replacement.

    The Bottom Line

    Green Street is a strong buy candidate for institutional CRE teams that need an independent view across REITs, private markets, property values and sector forecasts. Its research pedigree, proprietary data, valuation tools and integration options justify a serious evaluation. The product is most defensible when several investment, lending or portfolio workflows will use the same intelligence repeatedly.

    Do not approve it solely for brand recognition or occasional comp searches. Require a pilot covering recent deals, known assets and difficult submarkets. Compare results with CoStar, MSCI Real Capital Analytics, Moody’s REIS or CompStak, depending on the primary use case. BestCRE analysis: proceed if Green Street changes decisions or measurably shortens recurring analysis. Negotiate modular scope, data rights and renewal terms because the lack of published pricing limits external cost benchmarking.

    About BestCRE

    BestCRE.com is the definitive authority on commercial real estate AI, analysis, and investment intelligence. Every article advances the platform’s mission to help CRE professionals identify, evaluate, and adopt the best tools and strategies in the industry. We benchmark platforms using the 9AI Framework so CRE leaders can compare tools with clear evidence. Explore the category map at 20 CRE sectors for deeper coverage across the CRE stack.

    Frequently Asked Questions

    What is Green Street?

    Green Street is a commercial real estate research, data, analytics, news and advisory provider. It is best known for independent REIT research and also covers private property markets through market fundamentals, forecasts, sales comps, pricing indexes and valuation tools. Its primary users include institutional property investors, REIT analysts, lenders, advisors and brokers. The product supports capital allocation, acquisition, disposition, financing and portfolio strategy rather than property management or leasing administration. Users can access information through Green Street’s platforms, reports, Excel, Snowflake and API delivery. BestCRE analysis: its defining feature is the connection between public real estate securities and private property markets, which gives sophisticated investors a common analytical frame for comparing sectors, companies, markets and direct assets.

    How does Green Street compare with CoStar and MSCI Real Capital Analytics?

    Green Street emphasizes independent research, forecasts, valuation analysis and the relationship between REITs and private commercial property. CoStar is generally a more operational property information and brokerage platform, with extensive property records, listings, ownership information and market tools. MSCI Real Capital Analytics is a direct alternative for transaction data, capital flows and investment market analysis. Green Street can be preferable when the main questions concern relative value, sector allocation and forward market views. CoStar may fit daily prospecting and property research better, while MSCI Real Capital Analytics may fit transaction focused analysis. BestCRE analysis: these products are often complementary. Buyers should compare recent transactions, geographic coverage, asset classifications, export rights and update timing in their own markets before deciding whether one subscription can replace another.

    How much does Green Street cost?

    Green Street does not publish standard subscription prices. Public information does not state per user fees, minimum contracts, API charges, implementation costs or typical renewal increases. Pricing likely depends on the products selected, geographic coverage, number of users, data delivery method and permitted uses, but the vendor must confirm the actual structure. Buyers should request an itemized proposal covering research, private and public market data, news, valuation products, API or Snowflake access, onboarding, training and support. BestCRE analysis: compare the annual fully loaded cost with analyst hours saved and the number of material investment decisions supported. Also negotiate export rights, historical access, internal distribution permissions and price protections. A lower headline quote can be misleading if it excludes the feeds or usage rights needed for production workflows.

    Who should use Green Street?

    Green Street is best suited to institutional CRE investors, REIT analysts, asset managers, lenders, advisors and research driven brokers. It is particularly useful for teams that compare property sectors and markets, monitor portfolio exposure, assess relative value or challenge underwriting assumptions across many transactions. Organizations with internal data teams can use API and Snowflake delivery, while spreadsheet centered analysts can work through Excel and the native platform. BestCRE analysis: the strongest fit is a buyer with recurring decisions, named users and a documented process for incorporating external research into investment memoranda or portfolio reviews. Small owners seeking only local comps, active listings or ownership contacts may find a narrower service more economical. Green Street is also not a substitute for property management, accounting, leasing or required professional appraisal systems.

    Will GreenStreetAI change how CRE investors use Green Street data?

    GreenStreetAI could make Green Street research and data easier to query inside compatible AI tools. Its Model Context Protocol server is designed to provide access to institutional intelligence, while news and packaged workflows can add current context and repeatable analysis. This may reduce time spent searching reports, locating series and assembling first drafts of market comparisons. The important issue is whether answers preserve sources, permissions, definitions and update timing. BestCRE analysis: buyers should evaluate GreenStreetAI with real investment questions and require links back to underlying evidence. They should also test how it handles ambiguous property names, conflicting time periods and unavailable data. The likely near term role is analyst assistance, not autonomous investment judgment. Human review remains necessary for valuations, forecasts, transaction facts and conclusions presented to an investment committee.

    Related Reviews

    Compare Green Street with other tools BestCRE has scored in the same category: Matterport, Cotality, HelloData. Explore more CRE AI tool reviews in our Best CRE AI Tools directory. For sector-specific analysis and market intelligence, visit our 20 CRE Sectors hub.

  • Trepp Review: CMBS loan data analytics and credit surveillance

    Trepp Review: CMBS loan data analytics and credit surveillance

    BestCRE 9AI Score

    74/100 · Contender

    Trepp ranks #161 of 371 commercial real estate AI tools scored on the 9AI Framework. Nine dimensions, each scored out of 10: CRE relevance, data quality, ease of adoption, output accuracy, integration fit, pricing transparency, support, innovation and market reputation.

    Trepp is a commercial real estate and structured finance data provider used by CMBS investors, lenders, servicers, risk managers and credit analysts. Its central role in the CRE workflow is to turn securitized loan, property and bond information into searchable intelligence for underwriting, surveillance and portfolio decisions. Instead of assembling trustee reports, servicing records and market observations across separate files, users can investigate loans and securities through Trepp products, data feeds and analytical tools.

    The strongest reason to buy Trepp is its depth in CMBS. Its loan level history has become a common reference point for professionals evaluating delinquencies, special servicing, maturities, modifications and collateral performance. That history is particularly useful when a current loan problem needs context from comparable properties, prior cycles or earlier resolutions. Trepp also serves banking, whole loan, CRE valuation and CLO workflows, although its clearest identity remains debt market intelligence.

    Trepp is not a lightweight prospecting database or a general property research subscription. The platform is designed for buyers who already understand CRE credit and need evidence behind a view on risk, pricing or portfolio exposure. Product options include TreppAnalytics, TreppWatch, TreppPricing, TreppCRE, bank risk products, feeds and web services. Choosing among them requires a defined workflow because access, functionality and implementation needs can differ materially.

    BestCRE analysis: Trepp is one of the category’s strongest specialist data purchases, but it is not automatically the best purchase for every CRE team. Its value rises with the number of loans, bonds and recurring surveillance decisions a firm handles. Buyers should test coverage against their actual portfolio, confirm update timing and negotiate data rights before signing. Pricing is not publicly posted, so procurement cannot judge value without a proposal. Trepp scores above workflow platforms such as Blooma when authoritative CMBS depth matters most, but adoption and cost transparency keep it from being an uncomplicated category winner.

    What Trepp Does and How It Works

    Trepp organizes commercial mortgage information at several connected levels, including properties, loans, deals and securities. A credit analyst can begin with a portfolio, market, property type or individual exposure, then inspect characteristics such as balances, maturity schedules, payment status and servicing events where available. Surveillance teams use this structure to identify emerging exceptions and investigate the collateral behind them. The practical benefit is relational context: a troubled property can be evaluated alongside its loan structure, securitization and reported performance rather than as an isolated address.

    Its CMBS products support recurring monitoring, bond and deal analysis, valuation work and the distribution of data into internal systems. TreppWatch is positioned around surveillance, while TreppAnalytics provides analytical access to structured finance information. TreppPricing, TreppDerivative, TreppData Feed, TreppEngine and web services address more specialized pricing, calculation and delivery requirements. TreppCRE and TreppInsights BI extend the offering toward broader property and portfolio analysis. Banking products cover stress testing, default modeling, CECL and consortium data, while TreppLV addresses whole loan valuation. Exact fields, historical availability and refresh schedules depend on the purchased product and contract.

    Trepp has also introduced TreppAI and promotes TreppMCP servers for bringing its CRE finance intelligence into AI workflows. These capabilities may reduce the effort required to query specialized data or connect approved applications, but buyers should distinguish conversational access from verified credit conclusions. BestCRE analysis: AI is most useful here as an interface and research accelerator, while final underwriting and surveillance decisions still require inspection of source fields, definitions and reporting dates. A serious evaluation should use representative loans, known servicing events and difficult entity matches. It should also test exports, entitlements, auditability and the treatment of revised records. Trepp’s mechanics are strongest when its data becomes part of a repeatable credit process rather than an occasional lookup tool.

    9AI Framework: Dimension by Dimension Analysis

    CRE Relevance: 9/10

    Trepp earns a 9 for CRE relevance because commercial mortgage credit is not an adjacent use case. It is the core of the product family. Loan, property, deal and security relationships support underwriting, surveillance, valuation and portfolio risk work performed by CRE debt professionals. Coverage across office, multifamily, retail, lodging, industrial, mixed use and alternative properties gives analysts a common framework for comparing collateral. Banking products also address stress testing, CECL and default analysis. The score stops short of 10 because parts of Trepp extend into CLOs and structured finance beyond commercial property, while some equity investment, leasing and property operations workflows require different datasets. BestCRE analysis: for a CMBS investor or lender studying securitized debt, the fit is unusually direct. For a broker seeking contacts or an operator managing buildings, the relevance is narrower.

    Data Quality and Sources: 9/10

    Trepp earns a 9 for data quality. Its principal advantage is a deep history of loan level CMBS information tied to properties, deals, securities and servicing developments. That structure lets analysts compare current performance with prior events and observe credit migration over time. Trepp also publishes recurring market research based on its datasets, providing another way for users to evaluate definitions and aggregate trends. No database should be treated as error free. Servicer reporting can lag real world conditions, property names and entities can vary, and revisions may affect historical interpretation. Buyers should inspect field provenance, update schedules and correction practices for their licensed products. BestCRE analysis: Trepp’s information is strong enough to serve as a reference dataset in professional debt analysis, but investment conclusions still require source document review and independent judgment.

    Ease of Adoption: 6/10

    Trepp earns a 6 for ease of adoption. Experienced CMBS analysts should recognize the platform’s core objects and credit terminology, but that does not make implementation automatic. The breadth of products, fields and delivery methods creates an initial selection problem, and less specialized users may need training before they can form reliable queries or interpret servicing events. Adoption becomes harder when a firm wants feeds, web services or calculations embedded in internal risk systems. Entitlements and data rights also need coordination across research, technology and compliance teams. Trepp provides educational resources and role based solutions, which should help users establish a working model. BestCRE analysis: a focused surveillance team can gain value relatively quickly, while a broad enterprise rollout requires data mapping, workflow design and governance. The platform rewards expertise more than casual exploration.

    Output Accuracy: 8/10

    Trepp earns an 8 for output accuracy. Its analytical outputs benefit from structured relationships among loans, properties, deals and securities, plus the historical depth needed to test assumptions against earlier performance. This supports defensible surveillance and valuation work when users understand the underlying fields. Accuracy still depends on what is being measured. A reported payment status or servicing event is different from a forecast of default, loss or value, and model driven results depend on inputs and methodology. Public product descriptions do not establish a universal error rate, and the vendor does not publish one accuracy statistic that applies across all products. BestCRE analysis: Trepp is credible as an analytical foundation, but users should preserve source dates, document adjustments and validate modeled conclusions. AI generated responses should be checked against the licensed records before entering an investment memorandum or committee package.

    Integration and Workflow Fit: 8/10

    Trepp earns an 8 for integration because it offers more than a browser interface. TreppData Feed, TreppWeb Services and TreppEngine indicate delivery options for internal databases, applications and quantitative workflows. TreppInsights BI supports business intelligence use cases, while the announced TreppMCP servers target connections between CRE finance intelligence and AI applications. Partnerships with Blooma and Numerix further indicate that Trepp data can sit inside other lending and risk environments. The exact APIs, schemas, usage limits, implementation services and contractual permissions are not publicly detailed for every product. That prevents a higher score. BestCRE analysis: integration potential is strong for institutions with data engineering resources and a defined architecture. Buyers should request sample schemas, identifiers, update behavior, service commitments and redistribution terms before treating any connection as production ready.

    Pricing Transparency: 3/10

    Trepp earns a 3 for pricing transparency. The vendor invites prospects to request a trial, schedule a demonstration or speak with an expert, but it does not publish standard subscription prices for its main products. Public information also does not provide consistent package limits, implementation fees, user tiers, data feed charges or enterprise licensing terms. That makes comparison difficult before a sales process begins. Customized pricing can be understandable for datasets whose value and delivery requirements vary by institution, but buyers still need a clear unit of comparison. BestCRE analysis: procurement should request an itemized proposal separating platform access, named users, feeds, historical data, implementation, support and permitted downstream use. Renewal limits and charges for additional entities or fields should be explicit. Under the BestCRE framework, unpublished pricing cannot receive more than 5, and the lack of usable public benchmarks warrants a lower score.

    Support and Reliability: 7/10

    Trepp earns a 7 for support. Its public presence includes research, educational material, a resource library, an electronic learning portal, market commentary and contact options in New York, London and the Dallas area. Those resources can help analysts understand market concepts and incorporate Trepp information into recurring workflows. A long operating history and specialized product range also suggest an organization accustomed to serving institutional users. However, the vendor does not publicly provide comprehensive response time commitments, support staffing ratios or satisfaction measures across products. Contracted service levels may differ by account and delivery method. BestCRE analysis: prospective customers should evaluate support through a trial or technical review, especially when feeds and valuation workflows are involved. Ask who handles data questions, how corrections are communicated, what onboarding includes and whether support covers methodology as well as software operation.

    Innovation and Roadmap: 8/10

    Trepp earns an 8 for innovation. It continues to extend a mature CMBS franchise into whole loan valuation, business intelligence and AI assisted access. TreppLV targets transparent commercial mortgage portfolio valuation, while TreppAI and TreppMCP servers indicate an effort to make specialized finance data usable in conversational and machine connected workflows. The partnerships with Blooma and Numerix show a willingness to place Trepp information inside complementary underwriting and risk systems. Innovation should still be judged by workflow improvement, not product naming. Public information does not establish how widely the newer AI tools are deployed, how often they reduce analyst effort or what controls govern generated answers. BestCRE analysis: Trepp is moving in a useful direction by pairing specialized historical data with newer interfaces. A higher score would require clearer evidence of production adoption, measurable workflow gains and mature governance for AI outputs.

    Market Reputation: 9/10

    Trepp earns a 9 for market reputation. Founded in 1979, it has a long history in structured finance and commercial real estate information. The company publicly states that it serves more than 1,000 client firms, and its research is frequently used in professional discussions of CMBS performance. Its position is reinforced by products serving investors, lenders, servicers, banks, appraisers and risk managers rather than a single narrow buyer group. Partnerships with other financial technology providers also support its standing as a data source within broader workflows. Reputation does not eliminate the need for diligence, and public visibility is not proof that every module fits every institution. BestCRE analysis: Trepp is among the most established names a CMBS buyer can shortlist. The score stops short of 10 because reputation alone cannot verify individual product service levels, model performance or contract value.

    9AI Score Card Trepp
    74
    74 / 100
    Solid Platform
    CRE Debt Analytics
    Trepp
    Trepp gives lenders and investors a deep loan level CMBS history for surveillance, valuation, benchmarking and credit analysis across commercial real estate debt markets.
    9 Dimensions, Scored 1 to 10
    1. CRE Relevance
    9/10
    2. Data Quality & Sources
    9/10
    3. Ease of Adoption
    6/10
    4. Output Accuracy
    8/10
    5. Integration & Workflow Fit
    8/10
    6. Pricing Transparency
    3/10
    7. Support & Reliability
    7/10
    8. Innovation & Roadmap
    8/10
    9. Market Reputation
    9/10
    BestCRE.com, 9AI Framework v2 Reviewed October 2026

    Who Should Use Trepp

    Trepp best suits institutions that make repeated decisions about commercial mortgage credit. CMBS investors, bond analysts, special servicing teams and portfolio managers can use its connected loan, collateral, deal and security history to monitor exposures and investigate exceptions. Banks and nonbank lenders with meaningful CRE books may also benefit from its stress testing, default, CECL and whole loan valuation products. The strongest buyer has analysts who understand credit structures, a recurring surveillance cadence and enough exposure volume to justify specialist data.

    It also fits research, valuation and risk teams that need a shared reference point across portfolios. A firm comparing maturities, servicing transfers, modifications or property type stress can gain more from Trepp than a group seeking occasional market facts. BestCRE analysis: the ideal customer will identify several high value decisions before contracting, such as pricing a portfolio, reviewing watchlist loans or measuring concentration risk. It will also assign an internal owner for field definitions, integrations and user training. Trepp should be evaluated as an analytical system of record for debt work, not merely as another news or prospecting subscription.

    Who Should Not Use Trepp

    Trepp is a weaker fit for small owners, leasing brokers and property operators whose primary needs are tenant management, pipeline tracking, maintenance, accounting or local prospecting. Those workflows do not require extensive CMBS history, and a specialized subscription may add more complexity than practical value. Equity investors focused chiefly on rent comparables, demographics or transaction discovery may need Moody’s REIS, MSCI Real Capital Analytics or another property market source before they need Trepp.

    It may also be excessive for lenders with small CRE portfolios and infrequent surveillance requirements. A team without dedicated credit expertise can misread servicing fields or treat reported information as a complete view of current property conditions. BestCRE analysis: do not buy Trepp solely because counterparties recognize the name. First document the decisions it will support, the records it will replace and the employees who will use it. If the expected use is a few lookups per quarter, a narrower provider, consultant or transaction specific data purchase may be more economical.

    Pricing and ROI Analysis

    Trepp does not publish standard prices for its core subscriptions, data feeds, web services, banking products or valuation tools. Prospects are directed toward a free trial, demonstration or conversation with the sales team. The final price likely depends on the products selected, number of users, data coverage, delivery method and contractual usage rights, but the vendor does not publish a formula. Buyers should obtain separate prices for interface access, historical data, feeds, implementation, training, support and any right to store or redistribute derived information.

    BestCRE analysis: ROI should be calculated from decisions and labor, not from database size. For example, if five analysts each save three hours per week, multiply 15 weekly hours by the firm’s fully loaded hourly cost and annual working weeks. Add the expected value of avoiding one material underwriting or surveillance error, but probability weight that estimate rather than treating it as guaranteed. Compare the resulting annual benefit with the complete first year and renewal costs. Buyers should also test whether claimed time savings survive required validation. Without a written quote and a representative trial, Trepp’s financial return cannot be determined from public information.

    Integration and CRE Tech Stack Fit

    Trepp can fit into a CRE debt stack through its own analytical interfaces or through TreppData Feed, TreppWeb Services and TreppEngine. Those options matter for institutions that want loan and security information inside a warehouse, risk platform, reporting layer or internal application. TreppInsights BI addresses visualization and reporting, while announced MCP servers are intended to connect CRE finance intelligence with AI workflows. Product availability and technical rights must be confirmed in the contract.

    BestCRE analysis: buyers should make persistent identifiers the center of integration testing. Confirm how properties, borrowers, loans, deals and securities map to internal records, then test changes, duplicates and revised observations. Ask for schemas, data dictionaries, refresh schedules, authentication details, service commitments and sample error responses. Partnerships with Blooma and Numerix may reduce work in those specific environments, but they do not prove compatibility with every lender stack. Data retention, generated output, model governance and downstream sharing should receive legal and technical review before production deployment.

    Competitive Landscape

    CRED iQ is the closest specialist alternative for teams prioritizing CMBS surveillance, distress analysis and loan level research. A serious comparison should use the same watchlist, property types and known servicing events in both systems. Evaluate historical depth, search behavior, export quality, alerting and the speed with which analysts can explain a credit change. Trepp’s principal advantage is its established CMBS history and its role as a reference dataset across debt markets. CRED iQ may appeal to buyers seeking a more focused competitive workflow, but product scope and commercial terms require direct evaluation.

    Moody’s REIS is a stronger comparison when the assignment centers on property markets, rents, vacancies and forecasts rather than securitized loan performance. MSCI Real Capital Analytics is more relevant for transaction activity, capital markets and ownership research. Cherre serves a different role by connecting and governing data across a real estate organization. These platforms can complement Trepp instead of replacing it because they answer different questions.

    Within the broader BestCRE financing category, Blooma focuses more directly on AI supported lending workflow and received a score of 73. Finance Lobby, scored at 70, and StackSource, scored at 66, address lending marketplaces and capital placement rather than Trepp’s reference data role. Snapdocs and Maxwell, both scored at 82, concentrate on mortgage transaction workflows outside Trepp’s institutional CMBS center. BestCRE analysis: choose Trepp when debt data depth is the deciding requirement, then add workflow or property market systems only where distinct needs justify the cost.

    The Bottom Line

    Trepp should be on the final shortlist for any institution that routinely evaluates CMBS loans, deals or securities. Its deep historical dataset, connected analytical structure and standing in CRE debt markets make it a credible foundation for surveillance and credit research. The purchase case is strongest when multiple analysts will use the information every week or when Trepp data will support portfolio valuation, risk reporting or internal models.

    BestCRE analysis: proceed only after a representative data test and an itemized commercial proposal. Require the sales process to demonstrate difficult entity matches, servicing changes, export behavior and the exact history available for your portfolio. Confirm integration rights and renewal economics in writing. Teams seeking property operations, general prospecting or occasional market statistics should buy a narrower product. For specialist CRE debt organizations, however, Trepp’s data depth can justify the adoption burden and opaque pricing.

    About BestCRE

    BestCRE.com is the definitive authority on commercial real estate AI, analysis, and investment intelligence. Every article advances the platform’s mission to help CRE professionals identify, evaluate, and adopt the best tools and strategies in the industry. We benchmark platforms using the 9AI Framework so CRE leaders can compare tools with clear evidence. Explore the category map at 20 CRE sectors for deeper coverage across the CRE stack.

    Frequently Asked Questions

    What is Trepp used for in commercial real estate?

    Trepp is a data and analytics provider for commercial real estate debt, CMBS, banking and structured finance. CMBS investors, lenders, servicers, risk managers and credit analysts use it to research loans, properties, deals and securities, monitor performance and investigate distress. Its products support tasks such as surveillance, valuation, pricing, portfolio analysis, stress testing, CECL work and default assessment. Trepp is best known for its historical loan level CMBS information and the relationships it maintains among collateral, mortgages and securitizations. It is not primarily a property management, leasing or contact prospecting system. BestCRE analysis: its main value is giving debt professionals a consistent dataset for recurring credit decisions, provided that users verify source dates and distinguish reported facts from modeled conclusions.

    How does Trepp compare with CRED iQ and Moody’s REIS?

    Trepp and CRED iQ are the most direct comparison when a buyer needs CMBS loan research, distress monitoring and surveillance. Trepp’s differentiator is its deep historical CMBS dataset and established role across debt market workflows. Buyers should test both products with the same loans and known servicing events rather than selecting from demonstrations alone. Moody’s REIS addresses a different center of gravity, with property market information and forecasts that can support underwriting but do not substitute directly for CMBS surveillance. MSCI Real Capital Analytics is oriented toward transactions, ownership and capital markets, while Cherre helps organizations connect multiple data sources. BestCRE analysis: Trepp is the stronger shortlist candidate when loan, deal and security history drives the decision. Broader market or data management needs may require a complementary platform.

    How much does Trepp cost?

    Trepp does not publish standard pricing for its principal analytics products, data feeds, web services, banking tools or whole loan valuation platform. Prospective customers must request a trial, schedule a demonstration or contact the company for a proposal. Pricing may vary with product scope, users, coverage, delivery method and data rights, but no public formula allows a reliable estimate. Buyers should ask for an itemized quote covering subscription access, implementation, training, feeds, support, historical data and downstream usage. BestCRE analysis: calculate value by multiplying verified analyst hours saved by the firm’s fully loaded labor cost, then add a probability weighted estimate for improved decisions. Compare that benefit with both first year and renewal costs. No responsible ROI conclusion is possible before testing representative records and receiving contractual pricing.

    Who should buy Trepp?

    Trepp is best suited to CMBS investors, CRE lenders, servicers, bank risk teams, credit analysts and portfolio managers that make recurring decisions about commercial mortgage debt. It is particularly relevant when a firm needs to connect property performance with loan terms, servicing developments, securitization structures and historical outcomes. Larger portfolios and frequent surveillance cycles create the clearest economic case because specialist data can be reused across many decisions. It can also support appraisers, valuation professionals and researchers whose assignments involve debt market evidence. BestCRE analysis: the ideal buyer has experienced credit staff, an internal owner for data definitions and several documented workflows to test during a trial. Small operators, leasing teams and occasional users should consider narrower sources because Trepp’s specialist scope may exceed their needs.

    Will TreppAI change how CRE lenders analyze loans?

    TreppAI and TreppMCP servers could make specialized CRE finance data easier to query and connect with approved AI applications. The useful near term role is likely faster research, portfolio screening and retrieval of relevant loan or market context. These interfaces do not remove the need to examine source fields, reporting dates, definitions and model assumptions. Public information does not establish how widely the newer tools are deployed or quantify their effect on analyst productivity. BestCRE analysis: lenders should evaluate AI features with a controlled set of known loans, measure time saved after validation and test whether every answer can be traced to licensed data. Firms should also set permissions, retention rules and review requirements. The long term value will depend more on reliable provenance and workflow integration than on conversational presentation alone.

    Related Reviews

    Compare Trepp with other tools BestCRE has scored in the same category: Snapdocs, Maxwell, Blooma. Explore more CRE AI tool reviews in our Best CRE AI Tools directory. For sector-specific analysis and market intelligence, visit our 20 CRE Sectors hub.

  • Best CRE REITs 2026: The Grade Curve, Sector by Sector

    Public REITs own roughly $1.4 trillion of American commercial real estate, and in 2026 they are doing something they could not do for most of the last four years: buying. Nareit’s REIT Industry Tracker puts second-quarter funds from operations at a record $22.4 billion, 12.4 percent above a year earlier, with FFO per share 17 percent above the same quarter of 2019, dividends at 66.6 percent of FFO and development pipelines, outside data centers, 39 percent below their level at the end of 2019. Fifty-nine of the 161 listed REITs graded by REIT Rankings are paying a higher regular dividend than they were at the end of 2025. By the end of June, S&P Global Market Intelligence put the median REIT at an 8.7 percent discount to net asset value, down from 18 to 21 percent through the second half of 2025, and when the public price of a building approaches its private price, the landlord with the cheapest capital starts winning the auctions again.

    That is the part of the REIT story that matters to anyone who owns, finances or brokers commercial property rather than trading the shares. Four net lease REITs alone bought more than $3 billion of single-tenant real estate in the second quarter. Public Storage absorbed National Storage Affiliates in July. Equity Residential and AvalonBay merged in August into a company with more than 150,000 apartments. Blue Owl and Ares each took a listed REIT private for cash. The public REIT is once again the marginal buyer in net lease, industrial, healthcare and storage, which means its cost of capital is setting the cap rate on the building you are underwriting, whether or not you ever look at its stock.

    The consensus reading of this moment is that REITs are cheap and yields are attractive. The grades say something narrower and more useful. Of 161 listed REITs scored on the REIT Rankings five-pillar methodology (dividend safety, balance sheet, portfolio quality, growth and valuation), five earn an A, 53 a B, 61 a C and 40 a D. The sector’s yield curve is a credit curve. The best CRE REITs in 2026 are not the highest payers; they are the handful whose balance sheets let them borrow below the cap rates they buy at, and that list is short enough to name. This article names it, sector by sector, and explains what each grade means for the private buyer competing against it.

    REITs sit at the intersection of several BestCRE coverage areas: CRE Asset Classes, where the sector fundamentals live; CRE Market Analytics and Data, where the grading data comes from; and CRE Investor Relations and Capital Raising, because a REIT is above all a capital structure. The full map of coverage is on the 20 Best CRE Sectors hub. Grades, yields and market capitalizations below are from REIT Rankings as of the September 25, 2026 close and update automatically on the linked pages.

    Only Five REITs Earn an A, and That Is the Point

    Most ranking sites grade everything a buy. A grade curve where five names out of 161 sit above 85 and forty sit below 55 is uncomfortable, and it is also what the balance sheets say. The five A grades are Welltower (88), Realty Income (87), Prologis (86), Agree Realty (86) and Public Storage (85). Four of the five carry A-range credit ratings from S&P; Agree Realty, at BBB+, has the lowest leverage in net lease and 99.7 percent occupancy. What they share is not sector or yield. Welltower yields 1.5 percent and Realty Income 5.9 percent. What they share is that each can issue ten-year unsecured debt inside 5.5 percent and equity at or above net asset value, then buy real estate at 6.5 to 8 percent cash yields. The spread between those two numbers is the entire business, and only a handful of companies have it wide enough to compound.

    The 40 D grades are the mirror image. They cluster in mortgage REITs (32 names averaging a score of 51), commodity office and the small-cap hotel names, and in 2026 they produced the year’s casualty list: nine dividend cuts, three suspensions and four liquidations by our count. A D grade does not mean the stock is a bad trade; several of the year’s best-performing REIT shares were D grades bought after a cut. It means the dividend is not the reason to own it and the balance sheet does not give management the option of patience. The methodology weights dividend safety and balance sheet strength at more than half of the score for exactly this reason, and the full ranking of all 161 names reads top to bottom as a list of who can still buy.

    The Top-Rated REIT in Every Sector

    The table below shows the highest-graded name in each of the 15 sectors REIT Rankings covers, with the sector’s average score beside it. The gap between the leader and the average is itself information: in gaming and data centers the whole sector is well capitalized, while in office, hotels and mortgage the leader is an exception rather than a representative.

    SectorTop-rated REITScoreYieldMarket capSector average score
    HealthcareWelltower (WELL)881.5%$163B67
    Net LeaseRealty Income (O)875.9%$53B69
    IndustrialPrologis (PLD)863.2%$124B69
    Self-StoragePublic Storage (PSA)854.2%$51B70
    Data CentersEquinix (EQIX)842.1%$100B81
    RetailSimon Property Group (SPG)834.4%$58B66
    GamingVICI Properties (VICI)827.8%$26B79
    ResidentialEssex Property Trust (ESS)823.8%$18B66
    TowersAmerican Tower (AMT)814.2%$79B73
    HotelsHost Hotels and Resorts (HST)783.6%$15B58
    SpecialtyIron Mountain (IRM)753.1%$33B67
    OfficeCousins Properties (CUZ)744.5%$5B58
    TimberWeyerhaeuser (WY)724.2%$14B72
    MortgageRithm Capital (RITM)6811.0%$5B51
    FarmlandFarmland Partners (FPI)623.3%$0.5B59

    Net Lease: The Cost of Capital Is the Cap Rate

    Net lease is the sector where the public REIT and the private buyer compete for the identical asset, a freestanding building leased to a national tenant, and it is the clearest demonstration of why grades matter more than yields. Realty Income (87) owns 15,571 properties, carries an A- rating, and in the second quarter raised its full-year investment target to $10 billion while lifting AFFO guidance to $4.44 to $4.45 per share. Agree Realty (86) runs 99.7 percent occupancy with the sector’s lowest leverage. Essential Properties (80) buys the smaller, middle-market sale-leasebacks the giants ignore. All three borrow at or under 5.5 percent and buy at 7 to 8 percent cash yields, and because they can, the private buyer bidding on a Dollar General or a Kroger is competing against a cost of capital, not a local market.

    That competition runs in both directions. The same REITs are the eventual exit for most well-located net lease property with fifteen or more years of term, which is why the Kroger and Best Buy tenant credit profiles on this site read the REIT playbook alongside the tenant’s. The sector average score of 69 hides a wide spread: sixteen names range from Realty Income at the top to One Liberty and Global Net Lease in the C band, and Modiv, a small industrial net lease REIT, ceased to exist in August when it merged into Global Net Lease at 1.975 shares per share. Consolidation is the sector’s default state when the cost-of-capital gap is this wide. The full net lease ranking updates with market data several times a day.

    Industrial and Data Centers: Power Replaced Location

    Prologis (86) is the largest owner of logistics real estate in the world and the only industrial REIT with an A rating. It leads a sector whose ten graded names average 69, with EastGroup (80) and Terreno (76) the quality names in Sunbelt and coastal infill respectively. The sector’s fundamentals are the ones described in the electrical spec premium analysis on this site: post-2020 buildings with heavy power and clear height command a leasing premium that older stock cannot match, and the REITs own a disproportionate share of the new stock. Prologis runs 95.3 percent occupancy and, more importantly, a data center development pipeline built on its own land and power interconnects, which is where the industrial and data center sectors are converging.

    Data centers are the one property type where supply is growing rather than shrinking. Nareit’s REIT Industry Tracker shows the data center development pipeline at $21.4 billion, about seven times its level at the end of 2019, while the pipeline across all other sectors combined has fallen 39 percent. Equinix (84) and Digital Realty (78) are the only two pure-play data center REITs left after years of privatizations, and they carry the sector’s highest average score (81) because pre-leased hyperscale demand has turned development from a risk into a backlog. The constraint is not capital or tenants but grid interconnection, the argument made in why power is the new location. For the private developer the implication is uncomfortable: the two public landlords with investment-grade balance sheets and utility relationships built over two decades hold the scarce input, and the AI demand wave routes through them first.

    Healthcare: The Largest Sector by Value Still Prices Like a Bond

    Healthcare is the largest REIT sector in the ranking by market value, at roughly $278 billion across fifteen names, and Welltower (88) is the highest-graded REIT in the entire universe. Its $163 billion market capitalization exceeds Prologis and Simon combined, its A- rating is the sector’s best, and its 1.5 percent yield tells you the market is paying for senior housing operating growth rather than income. Ventas (79) is the credible second, and American Healthcare REIT (82) has become the sector’s fastest-growing name on the same senior housing thesis. The demographic argument is familiar; the version made on this site is that AI-driven outpatient care is the second demand engine, and that medical office and outpatient facilities are where it lands first.

    The sector is also where 2026’s private-market bid has been most visible. Blue Owl took Sila Realty Trust private for $2.4 billion in cash at $30.38 per share, a healthcare net lease portfolio that public investors had priced at a persistent discount. Community Healthcare Trust cut its dividend 31 percent in August to fund acquisitions, ending a ten-year streak of quarterly increases and showing what happens when a small-cap tries to grow at a cost of capital that no longer works. The average score of 67 reflects that spread between the giants and the small caps. For family offices and accredited investors the public route is straightforward; the private route into the same medical office and outpatient assets, at cap rates the REITs cannot reach in secondary markets, runs through healthcare real estate fund structures built for exactly that gap, which is where the cost-of-capital argument in this article turns into an allocation decision.

    Residential Consolidated in a Single Summer

    Apartment REITs delivered the year’s largest transaction when Equity Residential and AvalonBay closed their merger in August to form Vivmark Residential (VMRK), roughly $51 billion of equity value and the country’s largest coastal apartment owner. The combination removed two B-grade names from the ranking at once and left Essex (82), Equity LifeStyle (80) and Camden (78) as the highest-graded survivors: coastal California, manufactured housing and Sunbelt respectively. Equity LifeStyle is the quiet one; manufactured housing communities have the sector’s lowest capital expenditure and steadiest rent growth, and the grade reflects it.

    The other end of the residential ranking is where the year’s liquidations sit. Aimco and Elme Communities are both executing plans of sale and liquidation, paying out partial liquidating distributions ($14.67 per share from Elme in January, $2.23, $1.45 and $1.30 from Aimco through June) and shrinking to stubs. Both were subscale public companies whose portfolios were worth more to private buyers than their shares implied, which is the gap between public and private values closing through dissolution rather than repricing. UDR, meanwhile, switched to monthly dividends in July, joining a growing list of REITs (Four Corners and STAG among them in 2026) that changed payment cadence, a detail that trips up any yield screen built on trailing twelve-month math. The residential ranking now covers fifteen names.

    Retail and Gaming: Record Occupancy With No Supply

    Simon Property Group (83), Regency Centers (81) and Federal Realty (80) lead a nineteen-name retail sector whose fundamentals are the strongest in twenty years for a simple reason: almost no new shopping centers have been built since 2008, and the ones that exist are full. Simon runs 96 percent occupancy at the malls, Regency and Federal own grocery-anchored and mixed-use centers in the highest-income trade areas in the country, and all three carry A- or BBB+ ratings. The sector average of 66 is dragged down by the long tail of small-cap shopping center owners, several of which are now targets: Whitestone REIT was acquired by Ares for $1.7 billion in cash this year and SITE Centers is selling its remaining assets and distributing the proceeds as irregular special dividends.

    Gaming REITs are a two-name sector, VICI Properties (82) and Gaming and Leisure Properties (76), with the highest average score of any sector after data centers and the highest yields among investment-grade names, 7.8 and 8.5 percent. The structure explains both: triple net master leases on casinos with 100 percent occupancy, escalators tied to inflation, and tenants (Caesars, MGM, Penn) that cannot move. VICI is the largest owner on the Las Vegas Strip. For income investors comparing a 7.8 percent yield on a BBB- balance sheet against a 5.9 percent yield on Realty Income’s A-, the grade difference (82 against 87) is the price of tenant concentration.

    Self-Storage, Towers, Timber and the Specialists

    Public Storage (85) is the fifth A grade and the only one in a sector that has spent two years absorbing post-pandemic oversupply. Its A rating is the highest in the entire REIT universe, and it used that balance sheet in July to close the acquisition of National Storage Affiliates, taking the sector from six public names to five and adding roughly 1,000 properties. Extra Space (78) and CubeSmart (73) follow. Storage move-in rates have stabilized after two years of decline, and with the sector’s development pipeline down sharply, the consolidators are positioned for the recovery.

    Towers are a three-name sector where American Tower (81) and SBA Communications (76) carry the grades and Crown Castle (62) carries the lesson: a 90 percent AFFO payout ratio and a fiber business it is unwinding earned it a C despite a 6.3 percent yield. Timber is Weyerhaeuser (72) and Rayonier (71), the latter having absorbed PotlatchDeltic and trimmed its dividend slightly afterward. Iron Mountain (75) and Lamar Advertising (74) lead the specialty group, and Safehold (61), the ground lease REIT, remains the sector’s most interesting structure and its least loved stock. Each of these has a dedicated sector ranking with the live data behind the grade.

    Office and Hotels: Where the D Grades Live

    Office is the sector the bifurcation analysis on this site predicted and the grades confirm. Eighteen names average 58, but the spread is the story: Cousins Properties (74), BXP (72) and COPT Defense (70) own the trophy Sunbelt, gateway and government-secured assets where leasing has recovered, while the commodity end of the sector is in liquidation-adjacent territory. SL Green, Manhattan’s largest office landlord, reset its annual dividend from $3.10 to $2.47 and moved to quarterly payments to preserve capital for reinvestment. Franklin Street Properties halted its dividend after January, reported a $16.6 million second-quarter loss and trades near 35 cents. Piedmont has not paid a common dividend since February 2025. None of this is a recovery; it is a sorting, and the private buyer of office should read the D grades as a list of where the distressed sellers are.

    Hotels tell a similar story with better economics at the top. Host Hotels (78), Ryman Hospitality (75) and Apple Hospitality (72) are the graded leaders in a fourteen-name sector averaging 58. Host pays a modest regular dividend and returns the rest as year-end specials, which is the honest way to run a lodging REIT through a cycle. At the bottom, Braemar Hotels has not paid a common dividend since December 2025 and trades below $2. Hotel REITs are operating businesses wearing a real estate wrapper, and the grades weight balance sheet strength precisely because operating leverage cuts both ways.

    Mortgage REITs Are a Credit Book, Not a Landlord

    Thirty-two mortgage REITs make up the largest sector by count and the lowest by grade, averaging 51 with an average yield above 14 percent. That yield is the market’s estimate of how much of the dividend is real. Rithm Capital (68), Starwood Property Trust (66) and Annaly (63) lead because they are diversified originators and servicers rather than pure levered bond funds, and even they carry C grades. The 2026 casualty list is concentrated here: Apollo Commercial Real Estate Finance adopted a plan of liquidation and paid a $3.75 initial liquidating distribution in July; Arbor Realty cut its dividend 43 percent to $0.17 alongside impairment losses; KKR Real Estate Finance cut 60 percent; Franklin BSP cut 44 percent; Ready Capital cut to a token penny.

    The relevance to a CRE operator is direct. These are the lenders on the bridge loans and transitional assets that private sponsors borrowed against in 2021 and 2022, and a mortgage REIT cutting its dividend is a mortgage REIT working out loans. The mortgage REIT ranking is, read one way, a map of which lenders are still originating and which are managing a runoff book. For a borrower with maturing debt, that distinction matters more than the yield. BestCRE’s capital markets advisory exists in part because the answer changes quarter to quarter.

    The 2026 Scorecard: Nine Cuts, Six Acquisitions, Four Liquidations

    Set against the 59 REITs paying a higher regular dividend than at the end of 2025, the other side of the ledger from the REIT Rankings dividend safety tracker reads as follows for 2026 to date: nine dividend cuts (Alexandria, SL Green, Community Healthcare Trust, Arbor, Franklin BSP, KKR Real Estate Finance, Ready Capital, AFC Gamma, Orchid Island), three suspensions (Franklin Street, Braemar, Piedmont), four companies in liquidation or wind-down (Apollo Commercial, Aimco, Elme, SITE Centers) and six taken out by acquisition or merger (National Storage Affiliates, Sila, Whitestone, Modiv, AvalonBay and Equity Residential). Alexandria’s cut, from $1.32 to $0.72 per quarter, is the notable one: a life science landlord that had never cut in its public history reducing its dividend 45 percent to preserve capital through a leasing downturn.

    Both lists are true at once, and together they are the thesis of this article. Forty of the 59 raisers are A and B grades whose cost of capital reopened in 2026; the cuts, suspensions and liquidations are almost entirely C and D grades whose cost of capital never did. The acquisitions sit in between: reasonable portfolios trapped in subscale public vehicles, bought by the well-capitalized (Public Storage, Global Net Lease, the merged Vivmark) or by private capital (Blue Owl, Ares) that could pay net asset value when the public market would not. The narrowing discount to net asset value and the M&A wave are the same phenomenon seen from two sides. The grading pipeline behind these numbers reprices all 161 names four times each trading day and flags every dividend change the day it happens, which is how a list like this stays current without a research department.

    How to Use the Grades If You Buy Buildings, Not Shares

    Three uses follow from the sector-by-sector picture. First, the grade of the largest REIT in your asset class sets the floor on your cap rate. When Realty Income can earn 7.8 percent on a car wash with a 5.4 percent bond, it will keep buying car washes until the spread closes, and the quote you receive from a broker is downstream of that arithmetic. Second, the grade of the REIT that owns assets like yours tells you who your exit is and what they can pay; a sector whose leaders are A and B grades has a deep bid for stabilized product, while a sector whose leaders are C grades (office, hotels, mortgage) does not, whatever the headline yield suggests. Third, the D grades and the liquidations are a sourcing list. Aimco, Elme, SITE Centers and the office names selling assets to deleverage are motivated sellers with public timetables.

    The public REIT market has spent four years as a discount to private real estate and is spending 2026 closing that gap. The companies closing it are the ones with the grades to do so, and they are already in the room at every auction that matters. Read the grades before you bid against them.

    BestCRE exists to map commercial real estate AI, capital and investment intelligence honestly: the platforms worth paying for, the markets worth entering and the capital structures shaping where money is moving. Coverage spans 20 sectors of commercial real estate. If you are deploying capital, advising clients, or building in CRE, this is the resource built for you.

    Frequently Asked Questions

    What is a REIT grade and how is it different from a dividend yield?

    A REIT grade is a composite score of a real estate investment trust’s financial durability, produced by weighting dividend safety, balance sheet strength, portfolio quality, growth and valuation into a single number from 0 to 100, banded A (85 and above), B (70 to 84), C (55 to 69) and D (below 55). Dividend yield is simply the annual dividend divided by the share price, and it rises when the price falls, which is why the highest-yielding REITs are frequently the most stressed. Of 161 REITs graded by REIT Rankings as of September 2026, the five A grades yield between 1.5 and 5.9 percent, while the 32 mortgage REITs average a yield above 14 percent and a grade of 51. A grade answers whether the dividend is likely to be paid; a yield only reports what it would be if it were.

    How does a REIT’s cost of capital affect cap rates on private real estate?

    A REIT with an A- credit rating can issue ten-year unsecured bonds near 5 percent and equity at or above net asset value, then buy property at 7 to 8 percent cash yields and keep the spread. As long as that spread exists, the REIT keeps buying, and its bid becomes the price at which similar assets trade. In net lease, the four largest REITs bought more than $3 billion of single-tenant property in the second quarter of 2026 alone. A private buyer with a 6.5 percent mortgage cannot outbid a landlord whose blended cost of capital is 5.5 percent for the same building, so the cap rate on a Dollar General or a Kroger in a secondary market is set by Realty Income’s balance sheet rather than by local demand. When the REIT’s cost of capital rises, as it did from 2022 to 2024, the bid disappears and cap rates widen.

    Which REIT sectors saw the most acquisitions and liquidations in 2026?

    Residential, storage, healthcare and retail. Equity Residential and AvalonBay merged in August 2026 into Vivmark Residential, the year’s largest REIT transaction at roughly $51 billion of equity value. Public Storage closed its acquisition of National Storage Affiliates on July 22. Blue Owl took Sila Realty Trust private for $2.4 billion in cash, Ares acquired Whitestone REIT for $1.7 billion, and Modiv Industrial merged into Global Net Lease. On the liquidation side, Aimco and Elme Communities (both apartments), SITE Centers (retail) and Apollo Commercial Real Estate Finance (mortgage) are winding down and distributing proceeds. The pattern is consistent: subscale public companies whose portfolios were worth more to private buyers or larger REITs than their shares implied, which is what a closing gap between public and private values produces.

    Are data center REITs still the best way to invest in AI real estate demand?

    For public market investors they are the most direct way, and the grades support it: Equinix (84) and Digital Realty (78) give data centers the highest average sector score (81) in the ranking. Development pipelines in the sector are roughly seven times their 2019 level, against a 40 percent decline everywhere else, and the pipeline is largely pre-leased to hyperscale tenants. The constraint is power interconnection rather than capital, and the two public landlords hold the utility relationships and land positions that new entrants lack. The caveat is valuation: at 2.1 percent, Equinix’s yield is the second lowest in the ranking, so the return depends on continued growth rather than income. Prologis, an industrial REIT, is developing data centers on its own logistics land with existing power, and represents the indirect route.

    How can accredited investors and family offices access the healthcare real estate the REITs are buying?

    Through the public REITs directly (Welltower, Ventas and American Healthcare REIT are the highest-graded), or through private fund structures that acquire medical office, outpatient and senior housing assets in the secondary markets where the public REITs’ cost of capital does not reach. The distinction is cap rate: Welltower and Ventas buy at 5.5 to 6.5 percent in primary markets, while private vehicles targeting the same tenant credits in secondary markets acquire at 7 to 8 percent, with the depreciation and 1031 exchange benefits that REIT shareholders never receive. Healthcare is the largest REIT sector by market value at roughly $278 billion, and the 2026 take-private of Sila Realty Trust at $2.4 billion showed private capital paying full value for portfolios public investors had discounted. Minimums, liquidity and reporting differ substantially between the two routes, and the choice depends on whether income, tax treatment or liquidity matters most.

    Related reading: Best CRE Data Centers: Why Power Is the New Location · Best CRE Industrial Real Estate: The Electrical Spec Premium · CRE AI Hits the Balance Sheet: $199B in REITs Prove It

PRIME 7.00%FED FUNDS 3.88%5-YR UST 5.00%10-YR UST 5.19% ▼SOFR 30D 3.87%Updated Oct 16, 2026
Talk to a CRE Capital Advisor
Sizing a deal? | Curated capital network Tell Us About Your Deal (307) 439-0410